In a nutshell: if a bank buys a “tokenized” bond or other financial asset on the blockchain, Pontes helps the asset transfer and the payment in euros happen simultaneously and securely. This reduces the risk that one party delivers the asset without receiving the financial consideration, which is known as “delivery versus payment” settlement.
The phrase “credit risk to zero” was intended to be a slightly over-simplified: the point is that using central bank money greatly reduces counterparty risk related to settlement funds, but it does not eliminate all possible risks such as operational, technical, or legal risks.
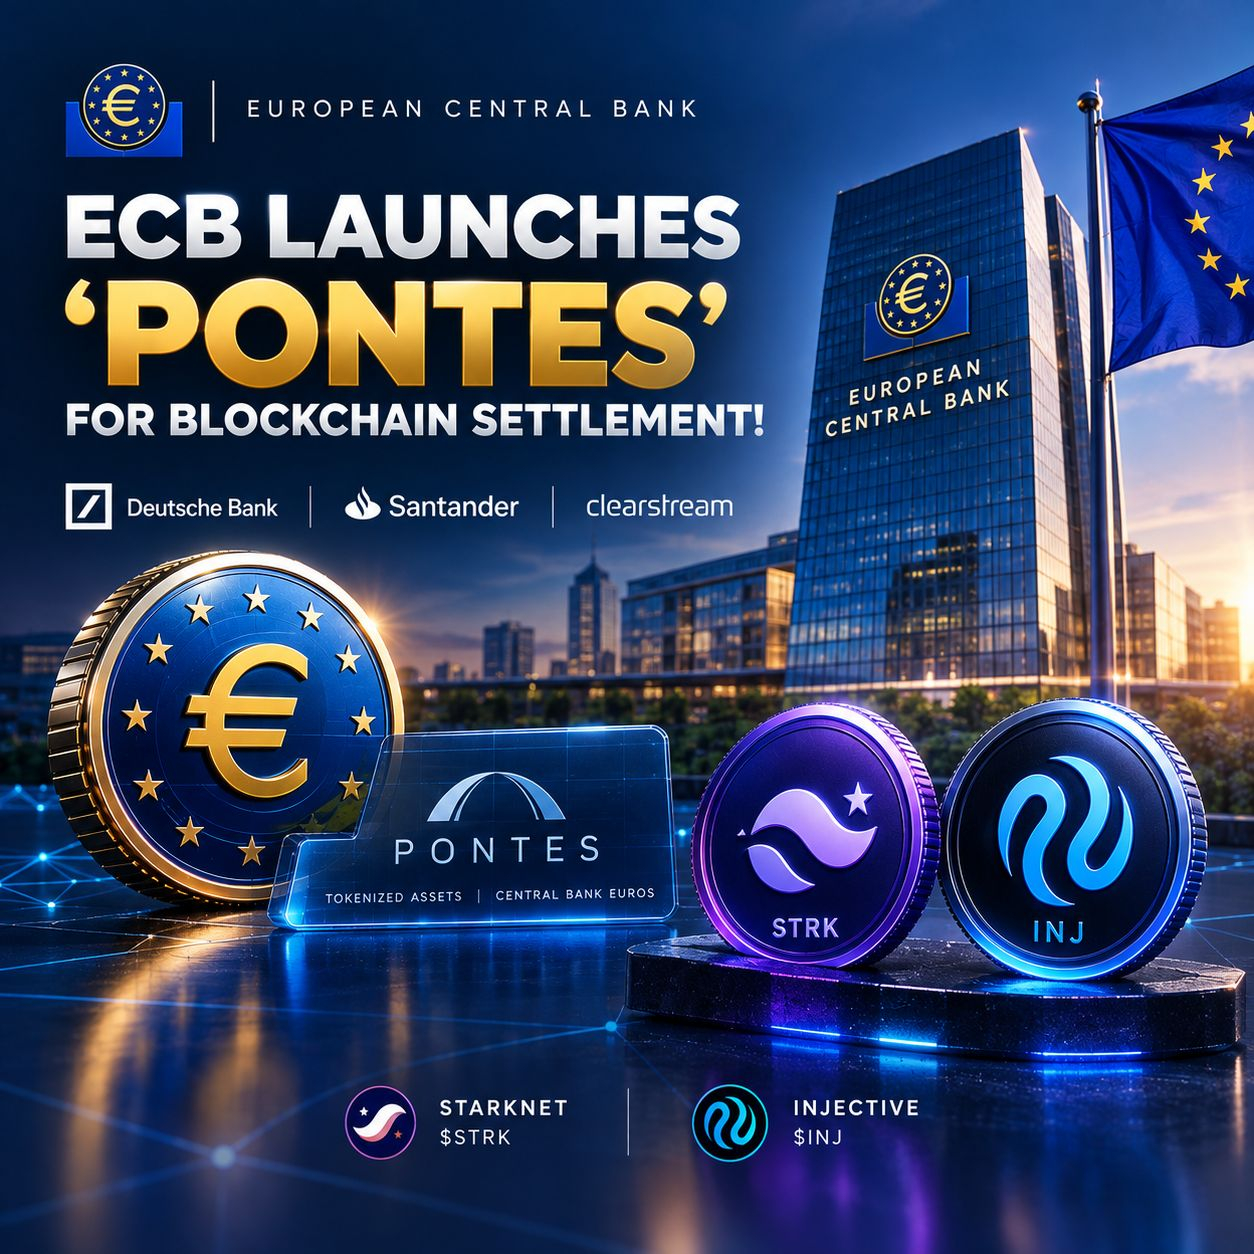
And the publication is correct in essence: the Eurosystem launched Pontes on 21 September 2026, and entities such as Deutsche Bank, Santander, and Clearstream joined the initial group. The European Central Bank also began preparatory work to invest a small portion of its own funds in tokenized securities, in order to gain practical experience; this is not an indication that it will buy cryptocurrencies.
The phrase “credit risk to zero” was intended to be a slightly over-simplified: the point is that using central bank money greatly reduces counterparty risk related to settlement funds, but it does not eliminate all possible risks such as operational, technical, or legal risks.
And the publication is correct in essence: the Eurosystem launched Pontes on 21 September 2026, and entities such as Deutsche Bank, Santander, and Clearstream joined the initial group. The European Central Bank also began preparatory work to invest a small portion of its own funds in tokenized securities, in order to gain practical experience; this is not an indication that it will buy cryptocurrencies.