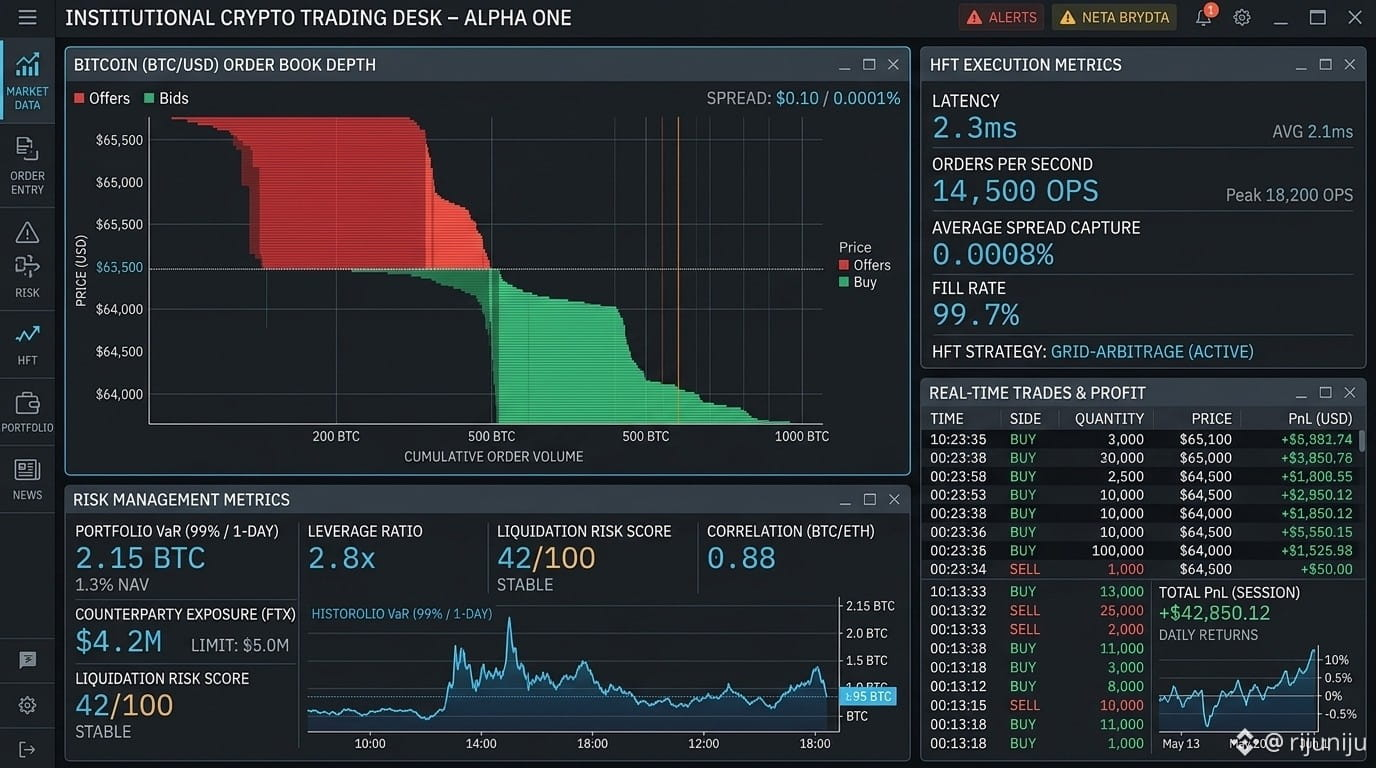
Dashboard Analysis
Continuous monitoring reveals an important dichotomy: while institutional demand via ETFs and the reduction of reserves on exchanges support a long-term bullish structure, the Fear & Greed Index at 75 indicates that the retail market and leveraged derivatives are overextended, increasing the probability of volatility in the short term.
2. Trading Infrastructure and Execution Impact
Executing trades at the institutional level requires understanding the order book structure and controlling the implicit costs derived from slippage and market depth.
Execution Statistical Parameters (Institutional Trades)
Mid Bid-Ask Spread: 0.01% - 0.03% on Tier-1 exchanges (Coinbase Prime, Binance Institutional).
Average Slippage:
For blocks of 10 to 50 BTC: ~0.02%
For blocks greater than 200 BTC: >0.15% (requires algorithmic execution).
Recommended Execution Algorithms:
TWAP (Time-Weighted Average Price): To split large orders into regular intervals and minimize market impact.
VWAP (Volume-Weighted Average Price): To execute in proportion to the traded volume during hours of high liquidity.