0.98%, this is the average interest rate on personal deposits at Postal Savings Bank. Among the six largest banks, only one has fallen below 1%.
The figures come from each bank’s 2026 interim reports. Postal Savings’ rate dropped by 0.18 percentage points from the start of the year. Industrial and Commercial Bank of China and China Construction Bank are both 1.13%, Bank of China is 1.17%, Agricultural Bank of China is 1.12%, and Bank of Communications is 1.56%—all of them staying close to, but still on, the red line.
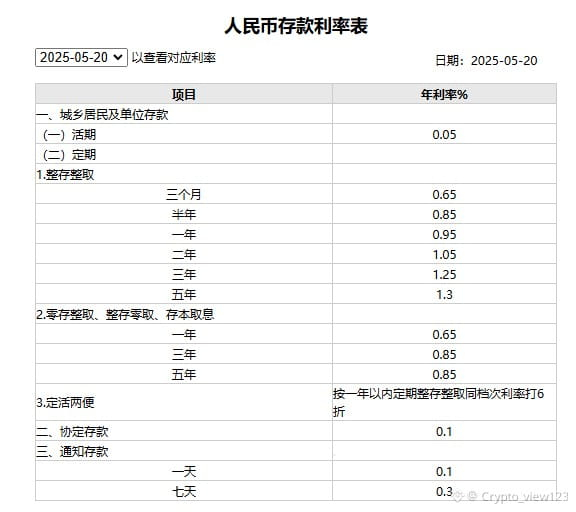
Demand deposits are 0.05%; ten years ago they were 0.35%. For 2025, the interest rates on time deposits are: one-year 0.95%, two-year 1.05%, three-year 1.25%, and five-year 1.3%. In early 2015, one-year time deposits were still 2.5% and five-year were 3.75%. Over a decade, the whole “live on interest” calculation has been replaced.
Now look at the average interest rates for time deposits: Industrial and Commercial Bank 1.69% (down 0.32 percentage points from the start of the year); China Construction Bank 1.67%; Bank of China 1.7%; Agricultural Bank 1.67%; Bank of Communications 2.02%; Postal Savings 1.24%. The declines are all around a few tenths.
The interest gap between time deposits and demand deposits is also getting thinner. In the past, putting money into a three-year term was a serious plan. Now a three-year term isn’t much different from a one-year term—so the option of trading on term length to earn more is getting narrower.
Money isn’t stupid. Since 2022, as deposit rates have been falling steadily, some people have moved into bank wealth-management products, and some have bought insurance—yet they’re still circling within the banking system. They just won’t keep their money sitting plainly in deposits.
On the other side, Bitcoin is now above $80,000. One side is under 1% in deposits; the other is something with much greater volatility. This multiple-choice question doesn’t need anyone to teach it. Back then, people who ran around for a few percentage points in interest spreads now run around for wealth-management platforms one by one.
With rates pushed down to this level, the most expensive thing is no longer risk—it’s leaving money where it does nothing.
#比特币突破8万美元大关 #bank deposits
The figures come from each bank’s 2026 interim reports. Postal Savings’ rate dropped by 0.18 percentage points from the start of the year. Industrial and Commercial Bank of China and China Construction Bank are both 1.13%, Bank of China is 1.17%, Agricultural Bank of China is 1.12%, and Bank of Communications is 1.56%—all of them staying close to, but still on, the red line.
Demand deposits are 0.05%; ten years ago they were 0.35%. For 2025, the interest rates on time deposits are: one-year 0.95%, two-year 1.05%, three-year 1.25%, and five-year 1.3%. In early 2015, one-year time deposits were still 2.5% and five-year were 3.75%. Over a decade, the whole “live on interest” calculation has been replaced.
Now look at the average interest rates for time deposits: Industrial and Commercial Bank 1.69% (down 0.32 percentage points from the start of the year); China Construction Bank 1.67%; Bank of China 1.7%; Agricultural Bank 1.67%; Bank of Communications 2.02%; Postal Savings 1.24%. The declines are all around a few tenths.
The interest gap between time deposits and demand deposits is also getting thinner. In the past, putting money into a three-year term was a serious plan. Now a three-year term isn’t much different from a one-year term—so the option of trading on term length to earn more is getting narrower.
Money isn’t stupid. Since 2022, as deposit rates have been falling steadily, some people have moved into bank wealth-management products, and some have bought insurance—yet they’re still circling within the banking system. They just won’t keep their money sitting plainly in deposits.
On the other side, Bitcoin is now above $80,000. One side is under 1% in deposits; the other is something with much greater volatility. This multiple-choice question doesn’t need anyone to teach it. Back then, people who ran around for a few percentage points in interest spreads now run around for wealth-management platforms one by one.
With rates pushed down to this level, the most expensive thing is no longer risk—it’s leaving money where it does nothing.
#比特币突破8万美元大关 #bank deposits