State a fact that many people are unwilling to accept. At this stage, my conclusion derived from the company valuation method is: CRCL’s reasonable price range is $65–$95.
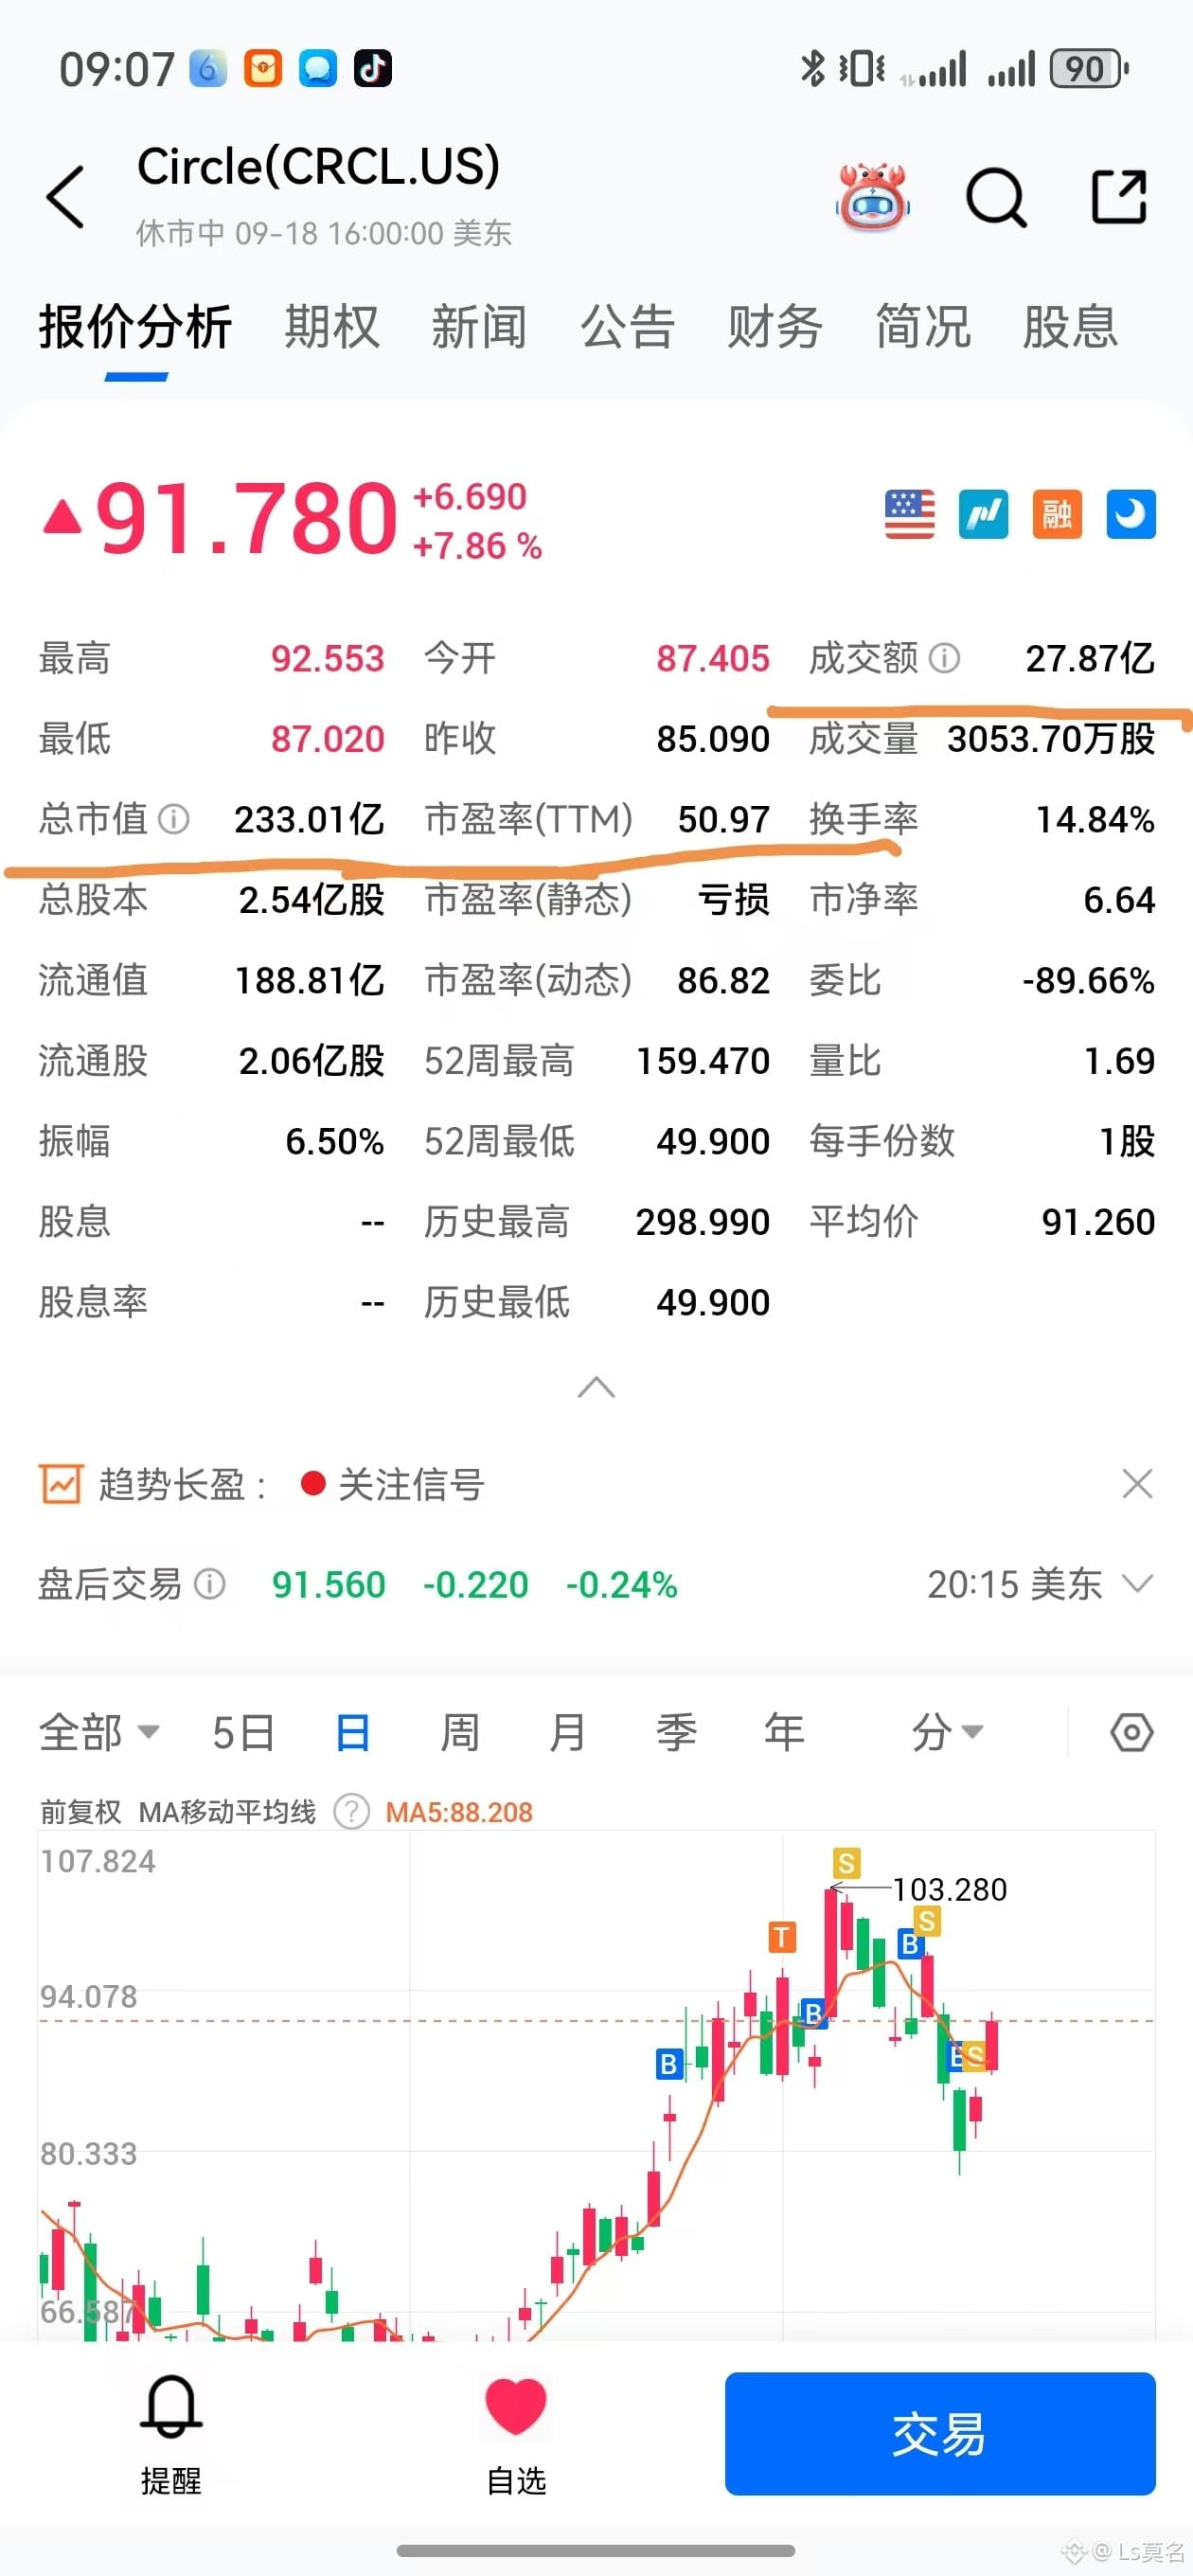
Currently, CRCL is about $91, with a market cap of $23.5 billion. I won’t think it’s cheap just because it fell from $159. I’ll use $65–$95 as a relatively reasonable benchmark valuation for now, and treat around $60 as a buy zone with a greater margin of safety. If, in the future, Arc, the payment network, and non-interest income really take off, then I’ll raise the valuation center of gravity—not buy into those dreams today.
Raising interest rates is good for CRCL. When interest-rate spreads narrow, it’s still profitable: half or more of the earnings go to coin. So, if the company’s valuation is going to be considered well, even if it drops to a low of $60, its intrinsic value can still grow.
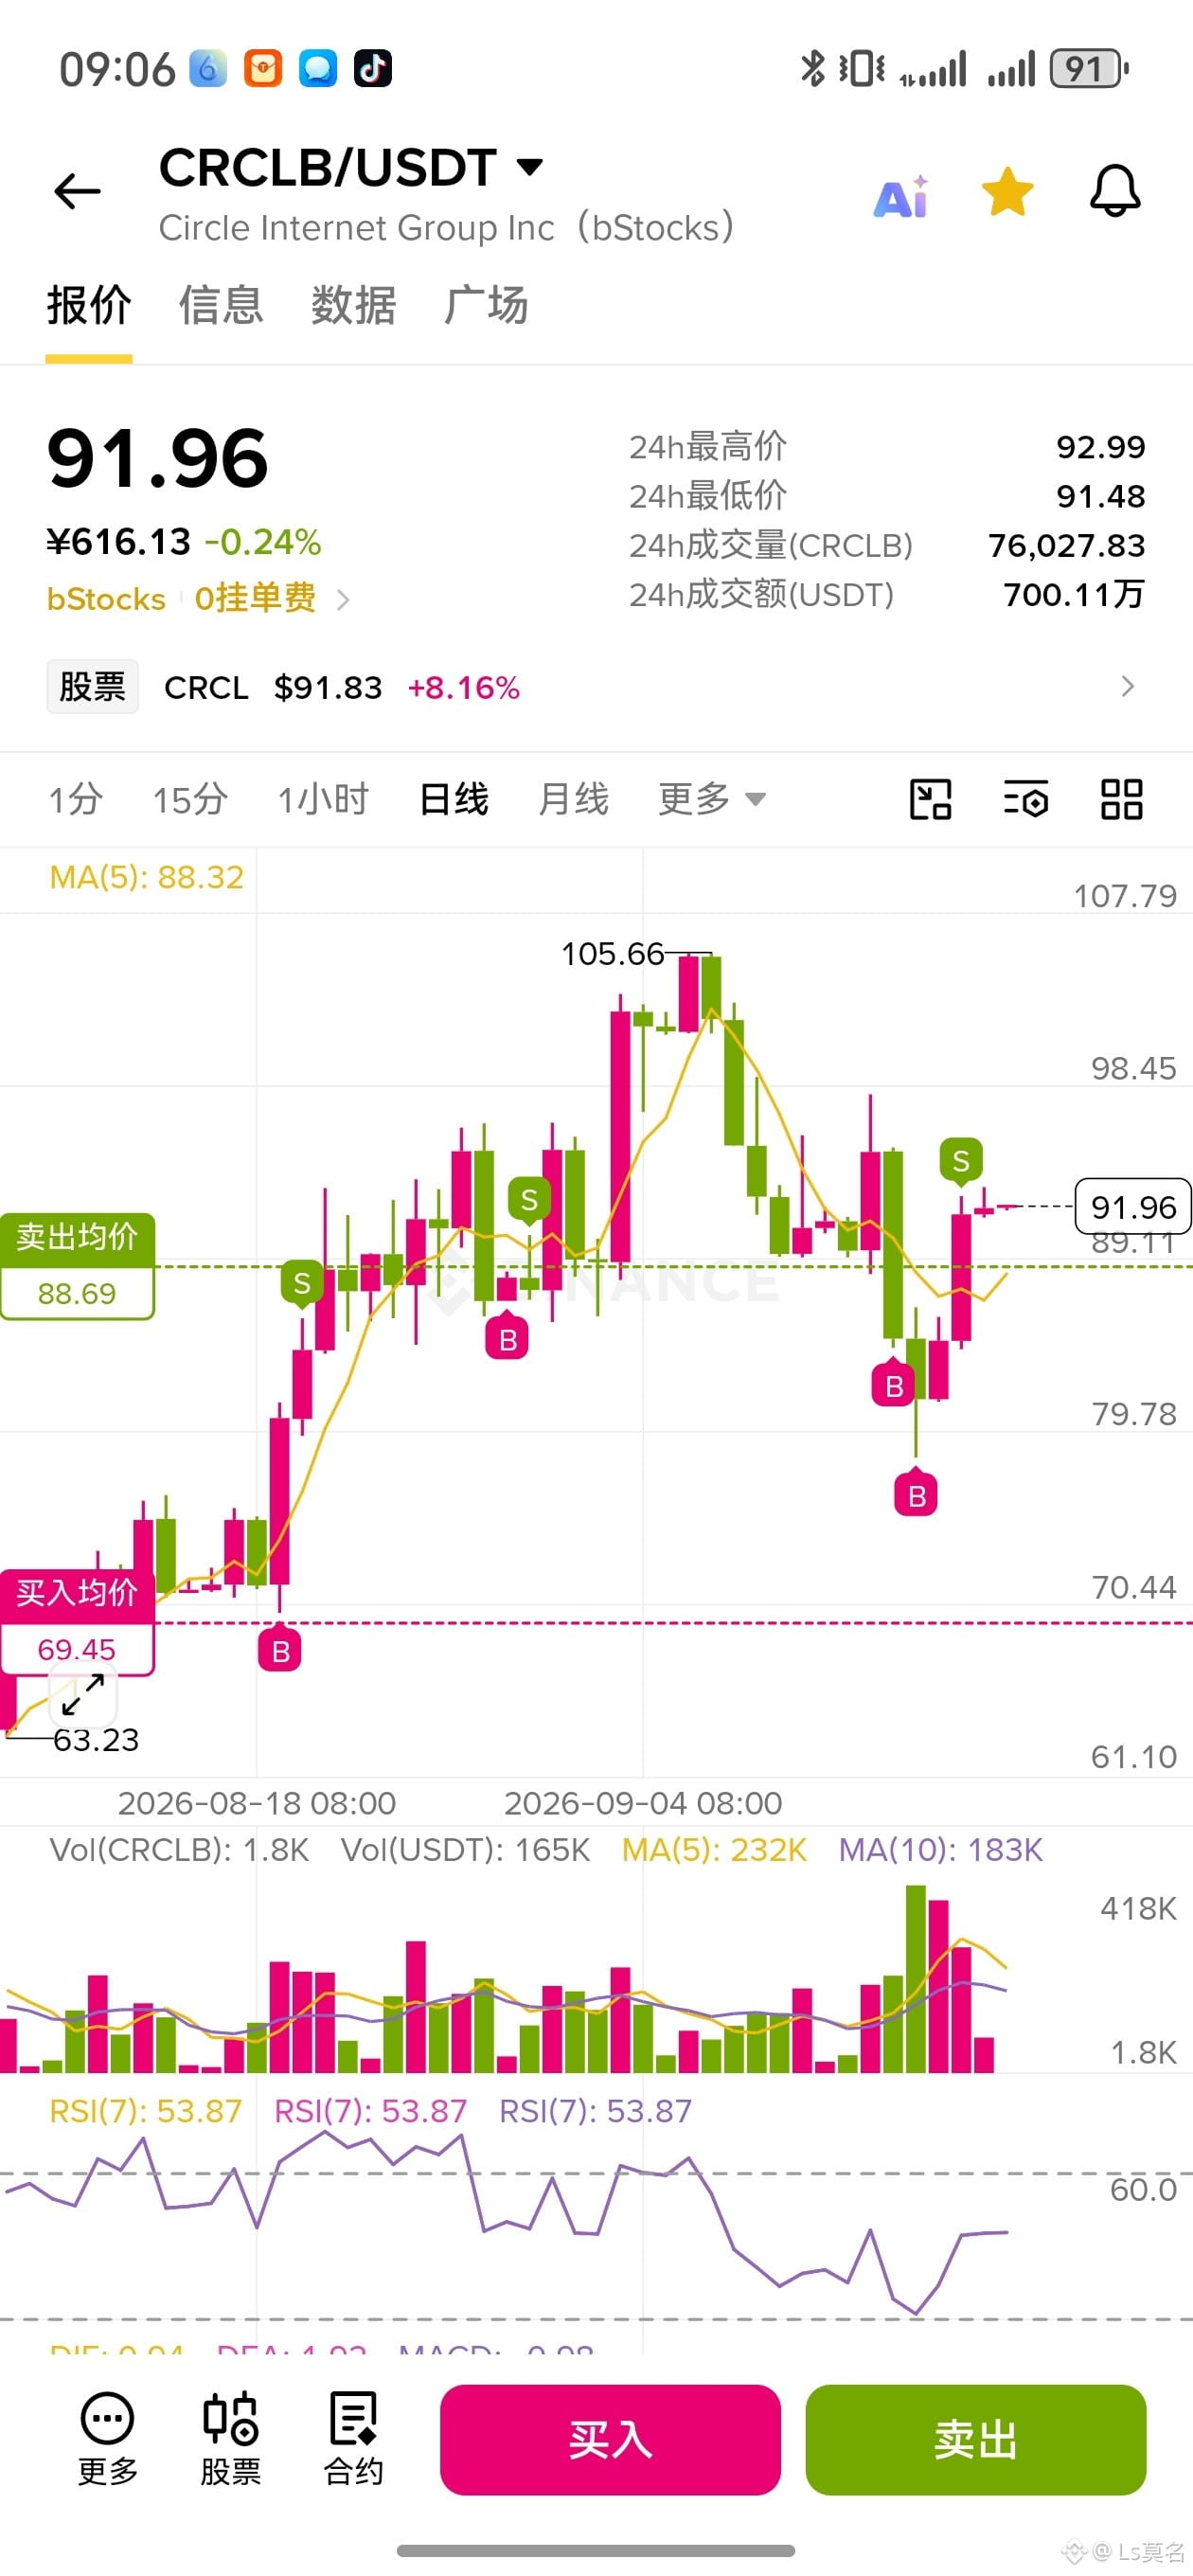
At this stage, therefore, selling high and buying low between $60 and $90 is best—comfortable, and with very low risk.
Currently, CRCL is about $91, with a market cap of $23.5 billion. I won’t think it’s cheap just because it fell from $159. I’ll use $65–$95 as a relatively reasonable benchmark valuation for now, and treat around $60 as a buy zone with a greater margin of safety. If, in the future, Arc, the payment network, and non-interest income really take off, then I’ll raise the valuation center of gravity—not buy into those dreams today.
Raising interest rates is good for CRCL. When interest-rate spreads narrow, it’s still profitable: half or more of the earnings go to coin. So, if the company’s valuation is going to be considered well, even if it drops to a low of $60, its intrinsic value can still grow.
At this stage, therefore, selling high and buying low between $60 and $90 is best—comfortable, and with very low risk.