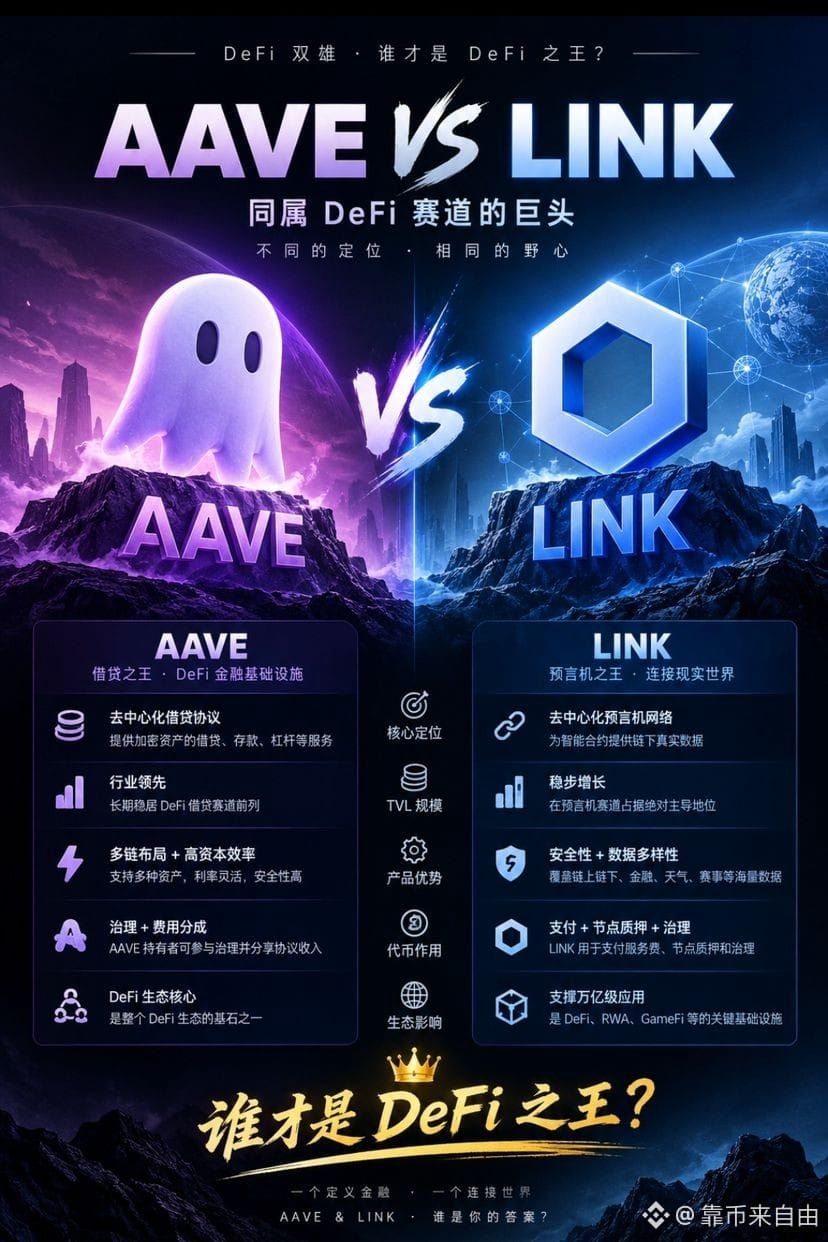
$AAVE and $LINK , both are super giants in the DeFi space. Why does almost everyone think LINK has a bigger upside potential❓
This is dangerous: when most people believe a project will go up, it’s more likely to blow up—on the contrary, the one that’s underestimated may actually take off 🛫
The reasons people currently favor LINK are, without exception, that LINK is the biggest “computer” for RWA.
If RWA is to be built, LINK’s oracle computation is required. In the oracle space, it’s basically only LINK and others.
There are 5 quadrillion in real-world assets globally. Even if only 1% gets tokenized and put on-chain, that’s 0.05 quadrillion. Given current chain trends: ETH is old money’s favorite and the first major on-ramp for RWA; SOL is the fast experiment for tech people; BNB enters with its user advantage and a CEX positioning curve—absolute three-way domination ❗️
But regardless of who becomes the final RWA king, LINK will be a beneficiary, which means its upside potential is huge and it’s strongly favored.
The catch is this: as a “service provider,” LINK is indispensable—but that doesn’t mean it can keep going up 📈
After all… the 0.05 quadrillion pie is split among three parties. That’s not that much, and it doesn’t even reach the amount represented by the current bull coin…
Consider project $BABY , which serves the bull coin. Just because the bull is awesome doesn’t mean the service provider can also fly. Moreover, LINK’s market cap is already quite high; it no longer has room for massive growth. Even if RWA is implemented, it could only rise to around 30U—at most ❗️
On the other hand, AAVE is a truly undervalued good project ❗️
AAVE’s positioning is “on-chain bank,” or put simply, the biggest lender on-chain.
Here’s a piece of counterintuitive knowledge: the global lending market is not inferior to real-world assets (RWA) by much.
The total amount of RWA is 0.5 quadrillion, while the global lending market is as high as about 0.36 quadrillion.
RWA is “expectations”—for projects that can actually be brought to life. Lending is a mature business that has been walked for thousands of years ❗️
More importantly, the global economic environment is worsening, and the early signs of financial crises are now a consensus.
You can see this by looking at the domestic employment environment: when the economy worsens, growth in the lending market becomes inevitable.
And one more point: AAVE’s market cap is still small. In the lending market, AAVE is still a younger brother among brothers—but on-chain, it’s the #1.
This kind of contrast will inevitably lead to AAVE having a burst breakout ❗️