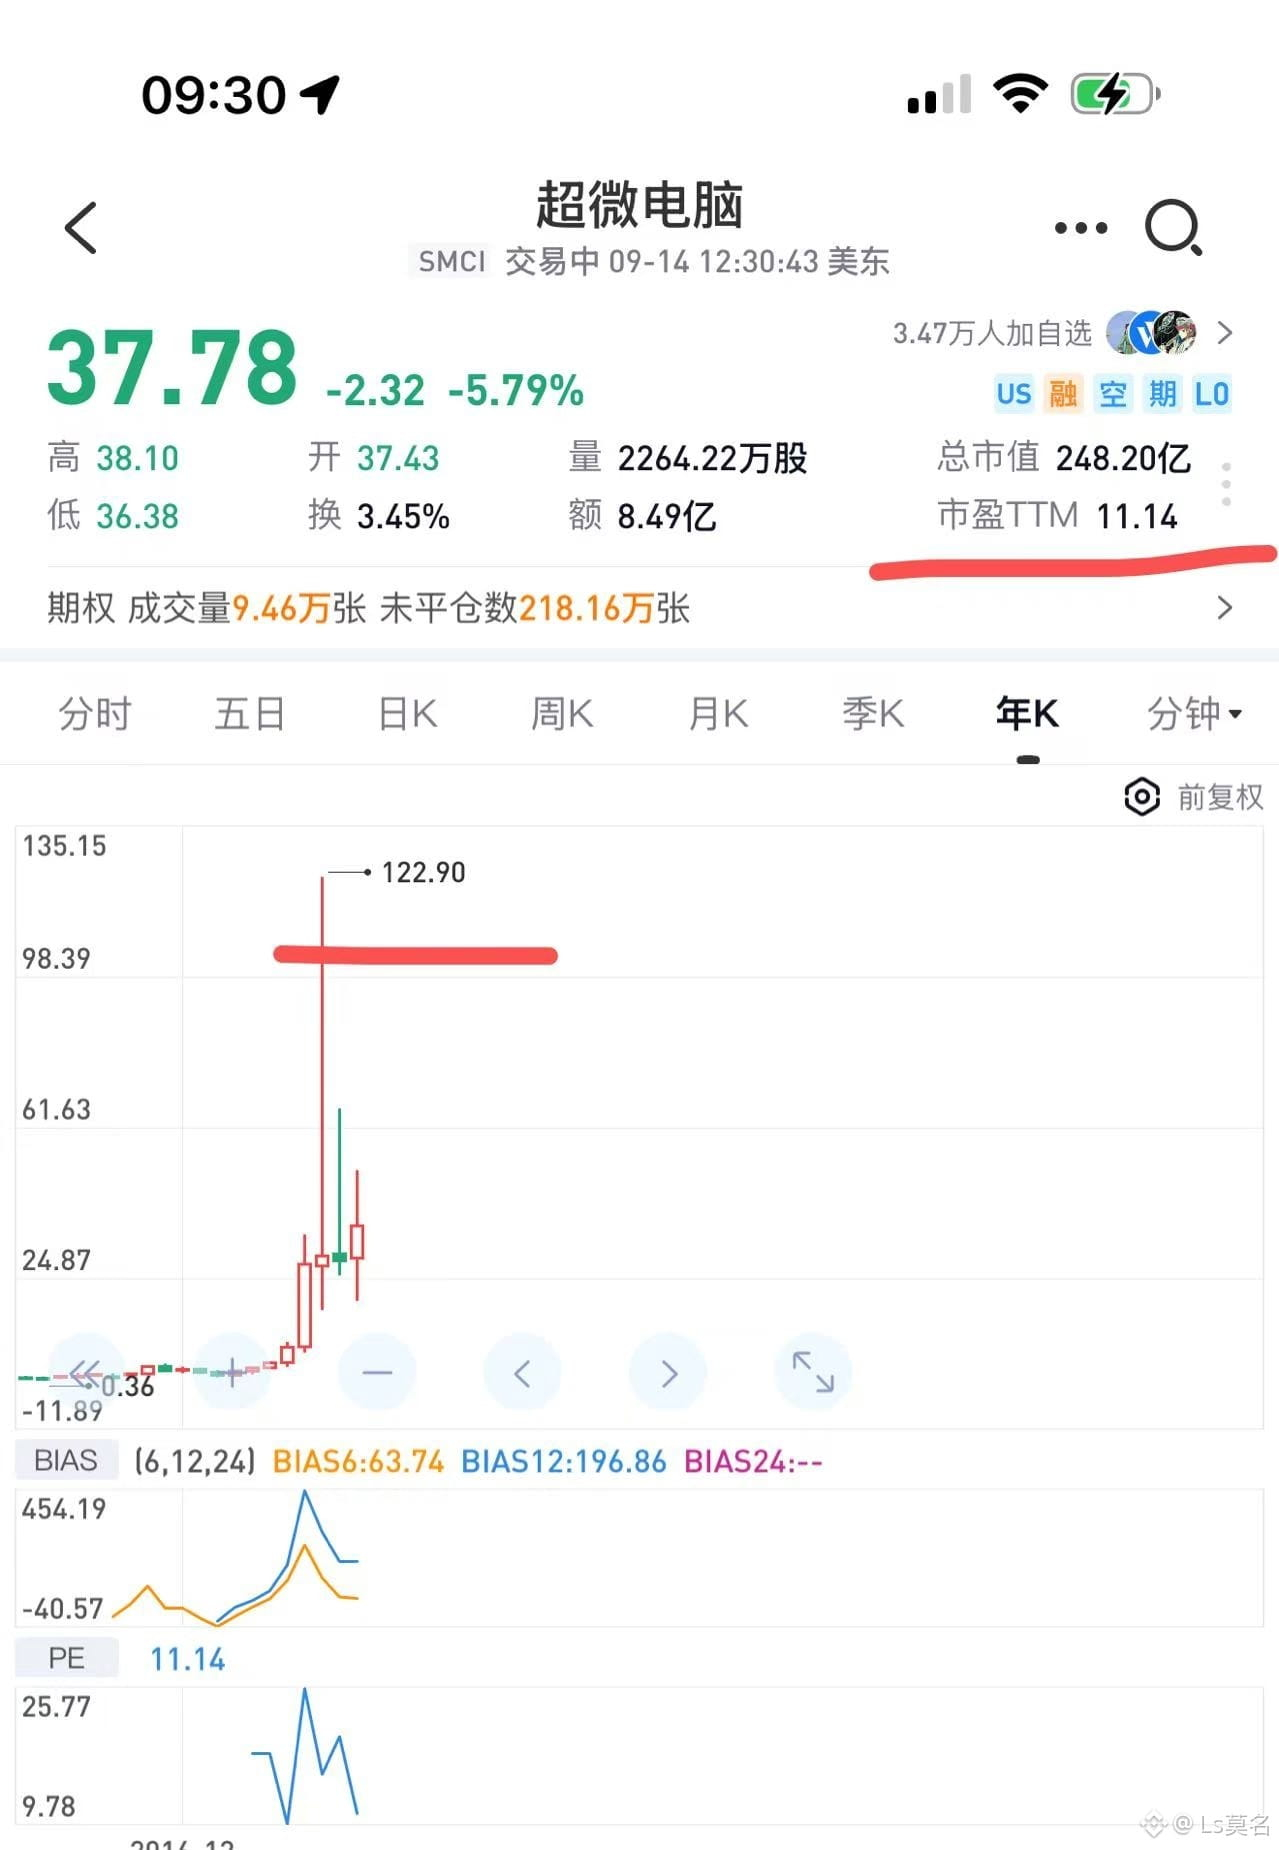
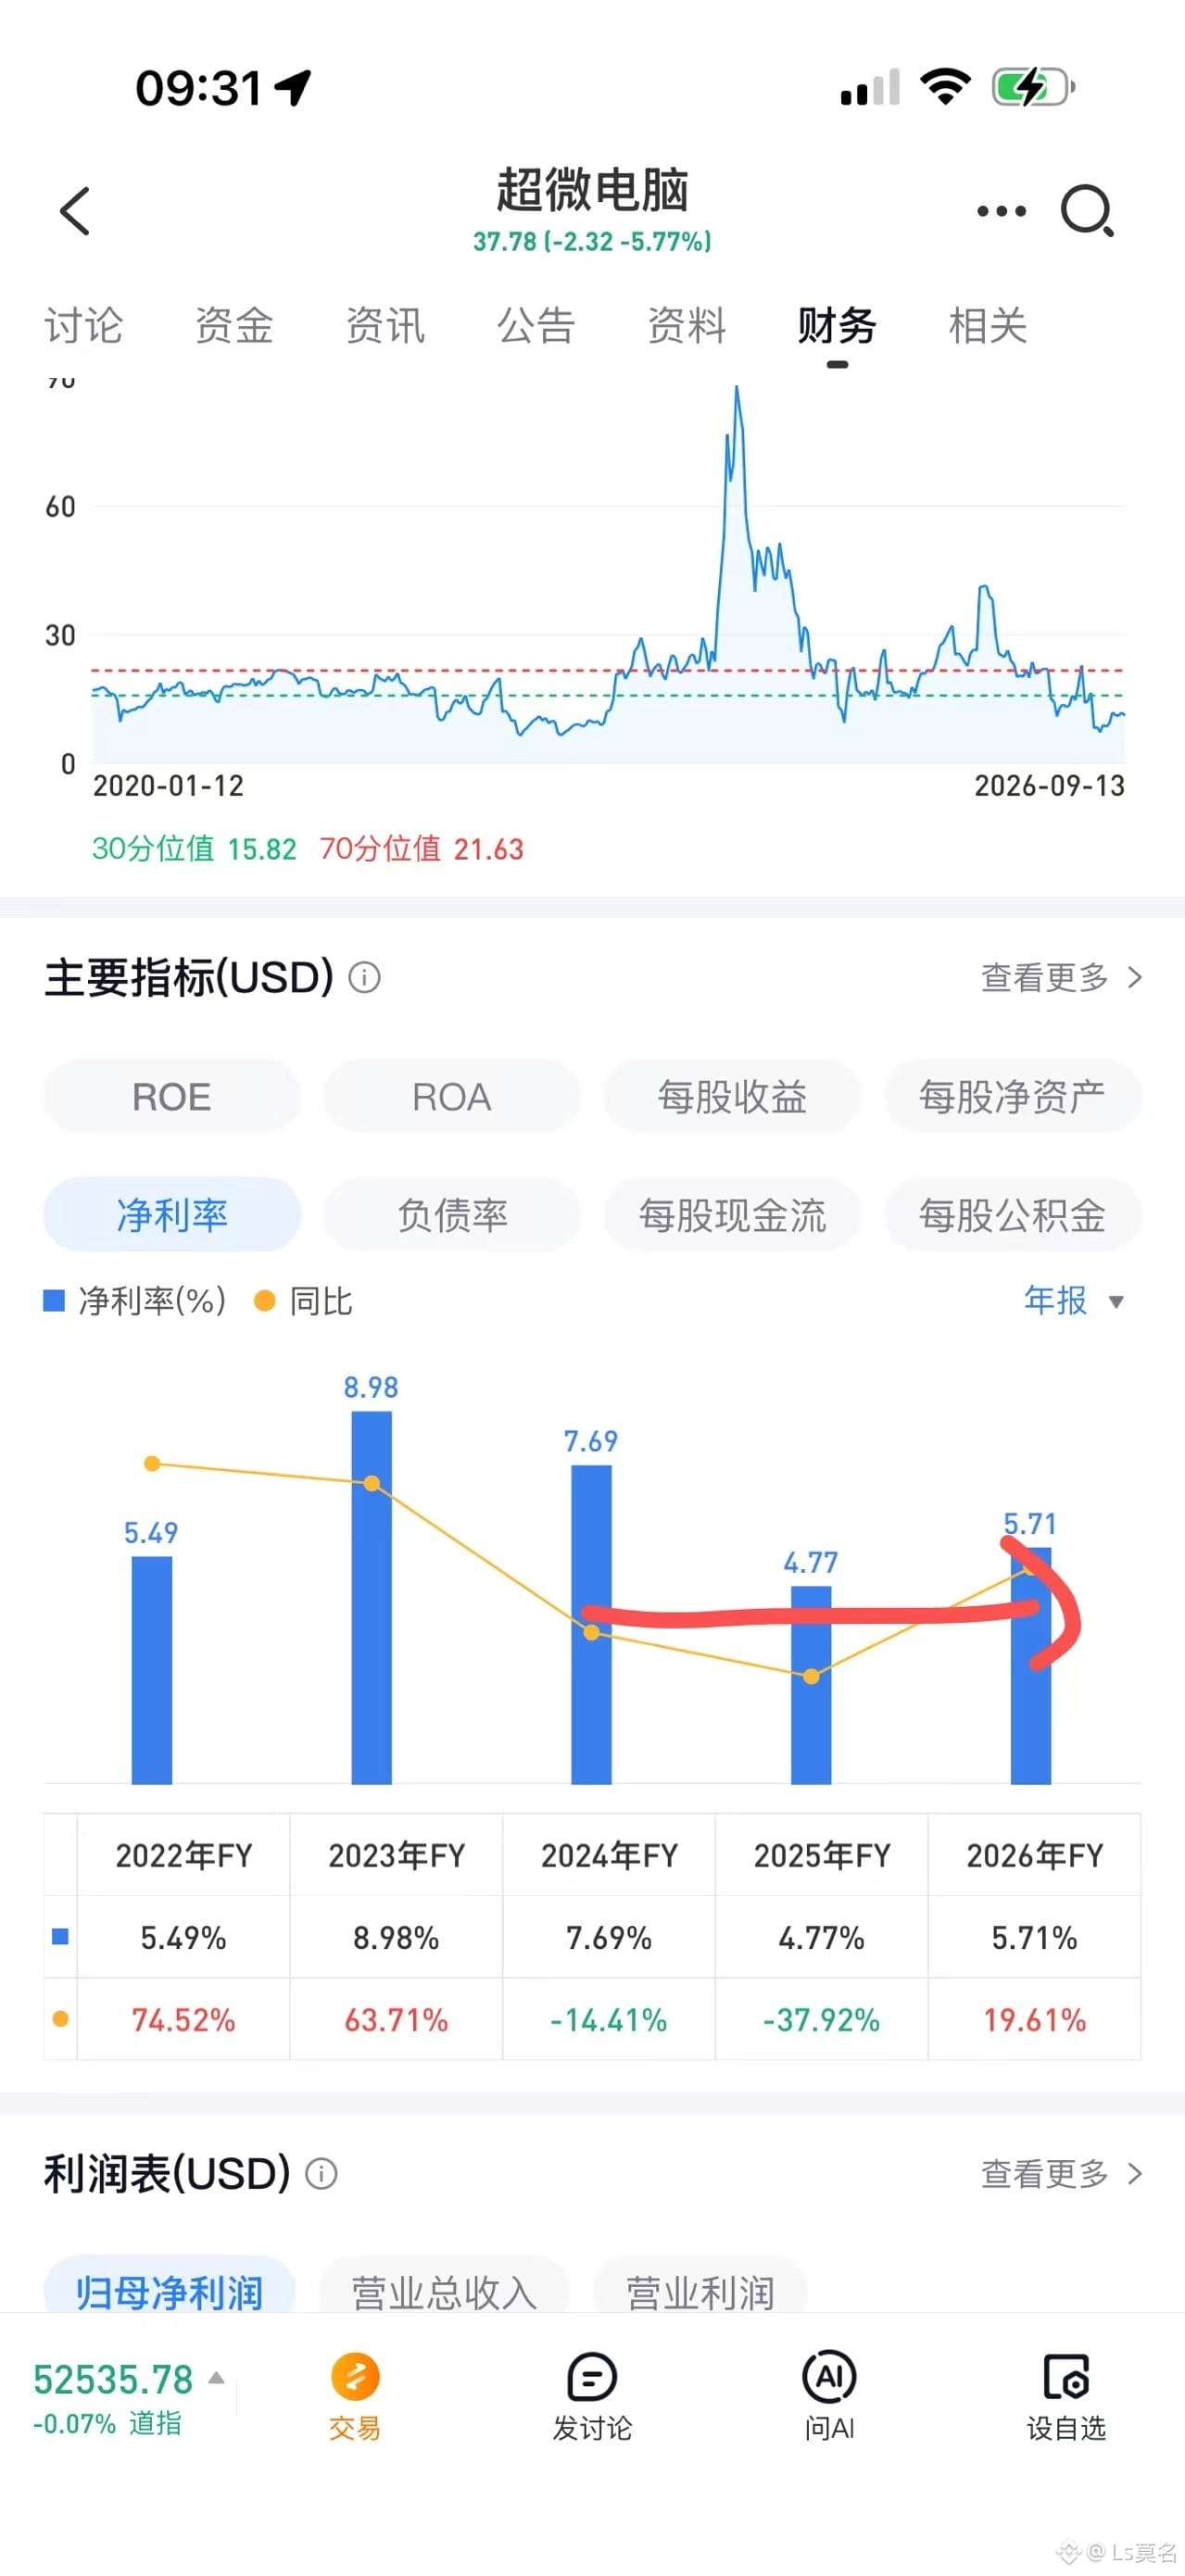
It’s best not to touch SMCI. The first company has always had integrity issues; multiple management teams over the years have encountered problems. Second, the profit margin is too low—it’s basically just a computer assembly company. Third, with the same valuation, you might as well consider storage; at least the moat is deep enough.

Post
--
Disclaimer: Includes third-party opinions. No advice. Binance AI may be used without guarantee. See T&Cs.