
Most people looking at $PYTH are still thinking about it as an oracle token. I think the more interesting story is what Pyth is becoming underneath the token.
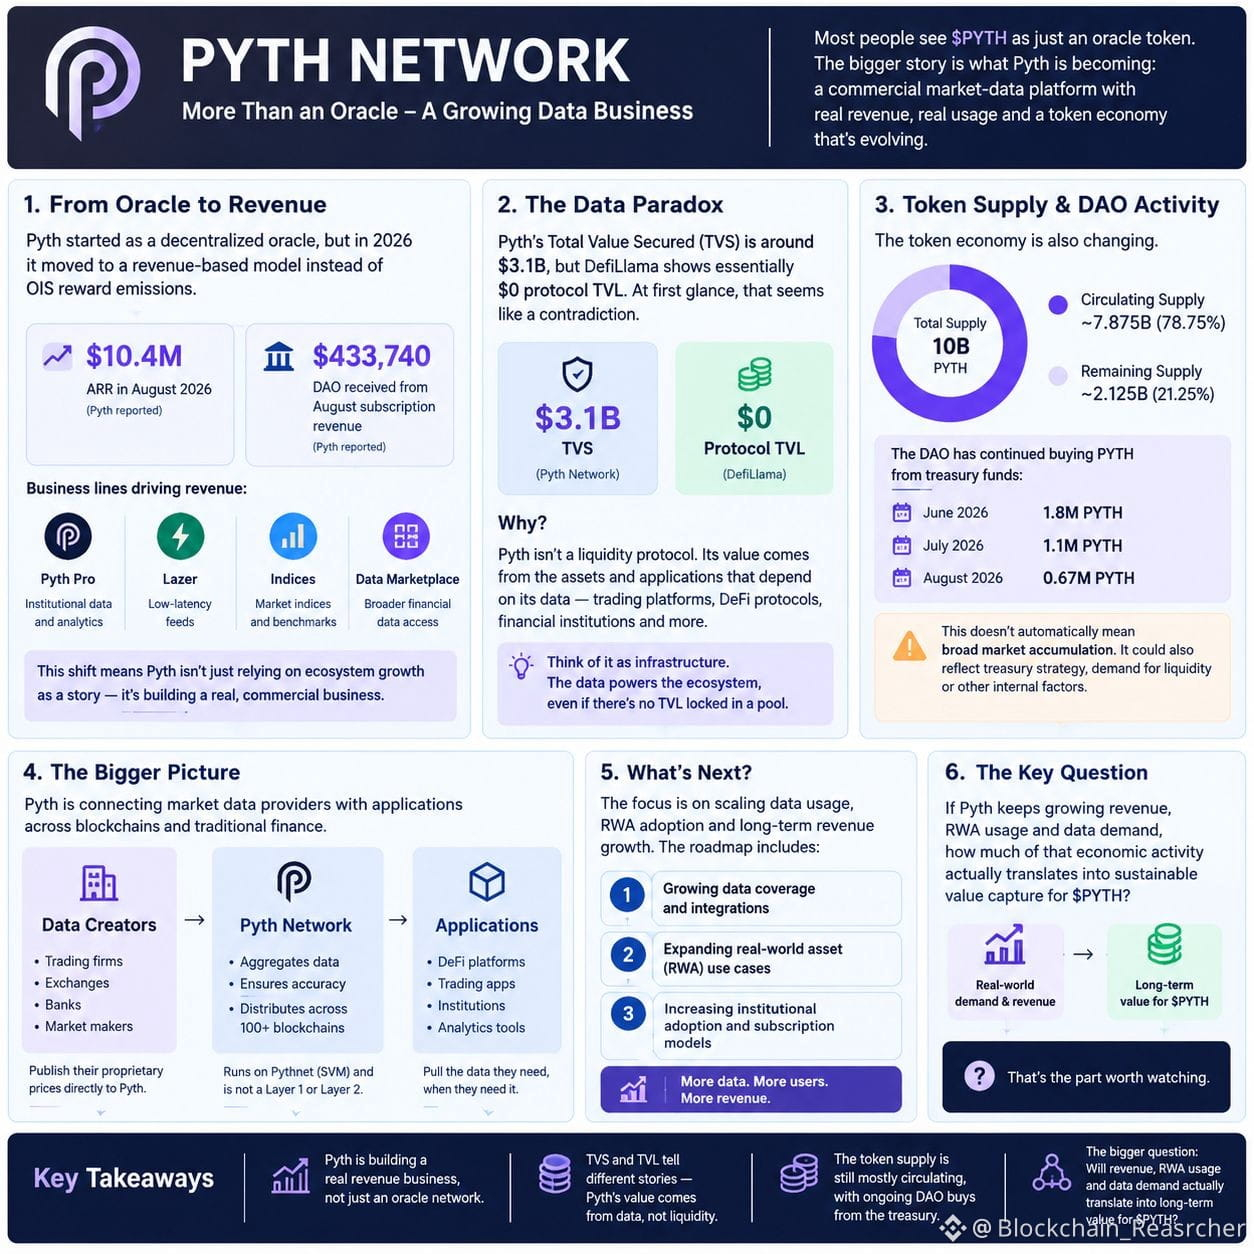
The clearest shift is economic. In 2026, Pyth moved away from OIS reward emissions and toward a revenue-based model. Pyth reported more than $10.4M in ARR in August, while its DAO received $433,740 from August subscription revenue.
That matters because Pyth is no longer relying only on ecosystem growth as a narrative. It is building a commercial market-data business around Pyth Pro, Lazer, Indices and its broader data marketplace.
Then there’s the part many traders overlook: Pyth’s TVS is around $3.1B, while DefiLlama shows essentially $0 protocol TVL. That sounds contradictory until you understand the mechanism. Pyth isn’t primarily a liquidity protocol. Its value comes from the assets and applications depending on its data.
The token side is changing too. Circulating supply is about 7.875B out of 10B, while the DAO has continued buying PYTH from treasury funds — roughly 1.8M in June, 1.1M in July and 0.67M in August.
But that doesn’t automatically mean broad market accumulation.
The bigger question for me is simple: if Pyth keeps growing revenue, RWA usage and data demand, how much of that economic activity ultimately translates into sustainable value capture for
$PYTH @Pyth Network #Pyth
The clearest shift is economic. In 2026, Pyth moved away from OIS reward emissions and toward a revenue-based model. Pyth reported more than $10.4M in ARR in August, while its DAO received $433,740 from August subscription revenue.
That matters because Pyth is no longer relying only on ecosystem growth as a narrative. It is building a commercial market-data business around Pyth Pro, Lazer, Indices and its broader data marketplace.
Then there’s the part many traders overlook: Pyth’s TVS is around $3.1B, while DefiLlama shows essentially $0 protocol TVL. That sounds contradictory until you understand the mechanism. Pyth isn’t primarily a liquidity protocol. Its value comes from the assets and applications depending on its data.
The token side is changing too. Circulating supply is about 7.875B out of 10B, while the DAO has continued buying PYTH from treasury funds — roughly 1.8M in June, 1.1M in July and 0.67M in August.
But that doesn’t automatically mean broad market accumulation.
The bigger question for me is simple: if Pyth keeps growing revenue, RWA usage and data demand, how much of that economic activity ultimately translates into sustainable value capture for
$PYTH @Pyth Network #Pyth