

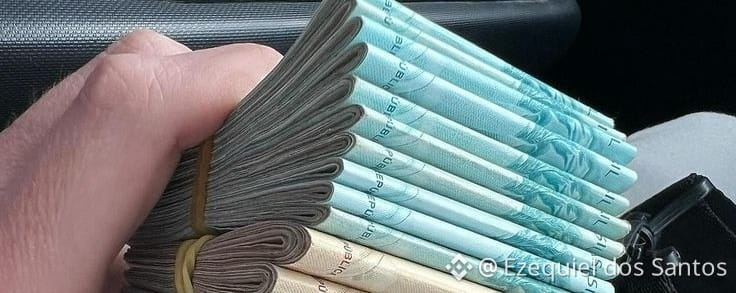
We’re living through the final years of paper money. If you’re under 30, it’s very likely your children will never hold a 50 reais bill as something normal.
Part 1: The slow, silent death of physical money
It wasn’t Bitcoin that started this. It was convenience.
In Brazil, the turning point has a name: Pix. For 64.9% of those surveyed, Pix is already the preferred payment method, ahead of cash, which was mentioned by 55.7% of people. The Central Bank has already been talking about contactless Pix to further speed up its use in physical commerce.
And the official narrative has changed. The Real Digital project, Drex, isn’t presented as a technological curiosity. The proposal is to gradually replace physical currency, even though technically Drex doesn’t replace physical money—it expands the ways the real can be used in digital environments.
This isn’t just Brazil. It’s global:
• 134 countries are exploring or developing CBDCs, covering 98% of global GDP • 72 countries are already in advanced phases, in pilot or development • 94% of central banks are working on some form of digital money • 3 countries have already actually launched them: Bahamas, Jamaica, and Nigeria • By mid-2025, there were already 137 countries representing 98% of global GDP exploring CBDCs
Why do governments want this so badly? Three reasons: cost, control, and sovereignty.
Printing, transporting, and protecting money costs billions. Digital money is traceable, taxable, and programmable. You can create an allowance that can only be spent on food, or a tax that’s automatically collected. And in a world where stablecoins from American companies threaten monetary sovereignty, having a digital real is a matter of state.
But there’s the other side that we pretend not to see: "If the only way to receive an allowance or pay a bill is via Pix, then anyone who doesn’t master that technology is automatically excluded." The end of physical money leaves millions behind, and that’s especially true in the interior of Pará and in the North, where the signal fails but the 10-rupee bill still works.
Part 2: AI won’t steal your job. It will change what it means to have one.
Every industrial revolution killed blue-collar jobs and created mental jobs. AI’s revolution is the first to kill mental jobs.
The IMF was direct: nearly 40% of global employment is exposed to AI. In advanced economies like the US and Europe, exposure reaches 60% of jobs, while in emerging markets—including Brazil, China, and India—exposure is 40%, and in low-income countries it’s 26%.
The ILO confirms the same order of magnitude: 1 in every 4 jobs will be transformed by artificial intelligence, with administrative functions suffering the biggest impacts, due to the theoretical ability of AI to automate many of those tasks.
And it’s not theory. Just in 2026, nearly 130,000 technology professionals lost their jobs, due to the deep reorganization of functions caused by AI.
Who is most at risk?
Professions with a high proportion of normalized and repetitive tasks, such as administration, customer support, writing, accounting, translation, software development, or graphic design.
The philosopher Luc Ferry was more apocalyptic: "About 300 million jobs will disappear because of artificial intelligence, and the world will go through massive unemployment."
But the story has nuance. A new ILO study shows that generative AI isn’t yet causing mass layoffs, but will reconfigure the professional lives of about 80 million people just in Southeast Asia. Half of the exposed jobs may see productivity increased, and the other half may have entire tasks taken over.
The crucial difference: before, automation replaced hands. Now, it replaces mid-level brains.
Part 3: When the two revolutions meet
This is where it gets really interesting—and a little scary.
Imagine in 3 years:
1. Your salary doesn’t fall in reais into your account. It falls in programmable Drex into your digital wallet at the Central Bank. 2. Your boss is an AI that assigns tasks, measures your productivity in seconds, and automatically pays you for completed micro-tasks. 3. The tax has already been withheld at the source; the housing allowance can only be spent on housing, and your credit score is updated in real time.
Programmable money + automated work = an algorithmic capitalism.
For companies and government, it’s perfect efficiency. For the worker, it’s the loss of the two protections we’ve had over the last 200 years: the anonymity of cash money and the bargaining power of irreplaceable human labor.
The IMF has already warned that AI will likely worsen global inequality. Whoever knows how to program AIs and hold digital capital gains a lot. Whoever does repetitive cognitive work loses.
And Brazil is in the middle of the storm. We’re leaders in digital payments, but with 40% of jobs exposed and little structured reskilling.
Part 4: And now? Three possible scenarios
There’s no going back. But there is a choice.
Scenario 1: The Great Exclusion
CBDCs become a tool for total control; AI replaces without reskilling. Physical money disappears before digital inclusion arrives. Result: a two-tier economy.
Scenario 2: The Great Redistribution
Countries implement a Universal Basic Income funded by taxes on automation and on CBDC transactions. Drex and Pix become the platform to pay that income instantly. Human work shifts to care, creativity, and AI supervision.
Scenario 3: The most likely—Chaotic Adaptation
We won’t have a single plan. We’ll have lawyers using AI to handle 10x more cases, designers turning into AI directors, app drivers turning into operators of autonomous fleets. Physical money won’t be banned by law—it will just become irrelevant and expensive to use. The project trying to prevent the extinction of paper money in Brazil shows that the political debate has already started.
What you can do today, in practice:
• Stop thinking in terms of "profession" and start thinking in terms of "skills that AI doesn’t replicate well": complex judgment, real empathy, creativity with a human context, and knowing how to ask better questions than the AI. • Understand programmable money. Not as an investment, but as infrastructure. Learn how to use Drex, Pix, stablecoins. Anyone who doesn’t understand the new financial pipeline will pay an expensive toll. • Become hybrid. The future job isn’t "replaced by AI"—it’s "enhanced by AI." The accountant who uses AI eliminates three accountants who don’t.
The end of money as we know it isn’t about the end of value. It’s about the end of the anonymity of value.
AI’s impact on jobs isn’t about the end of work. It’s about the end of predictable work.