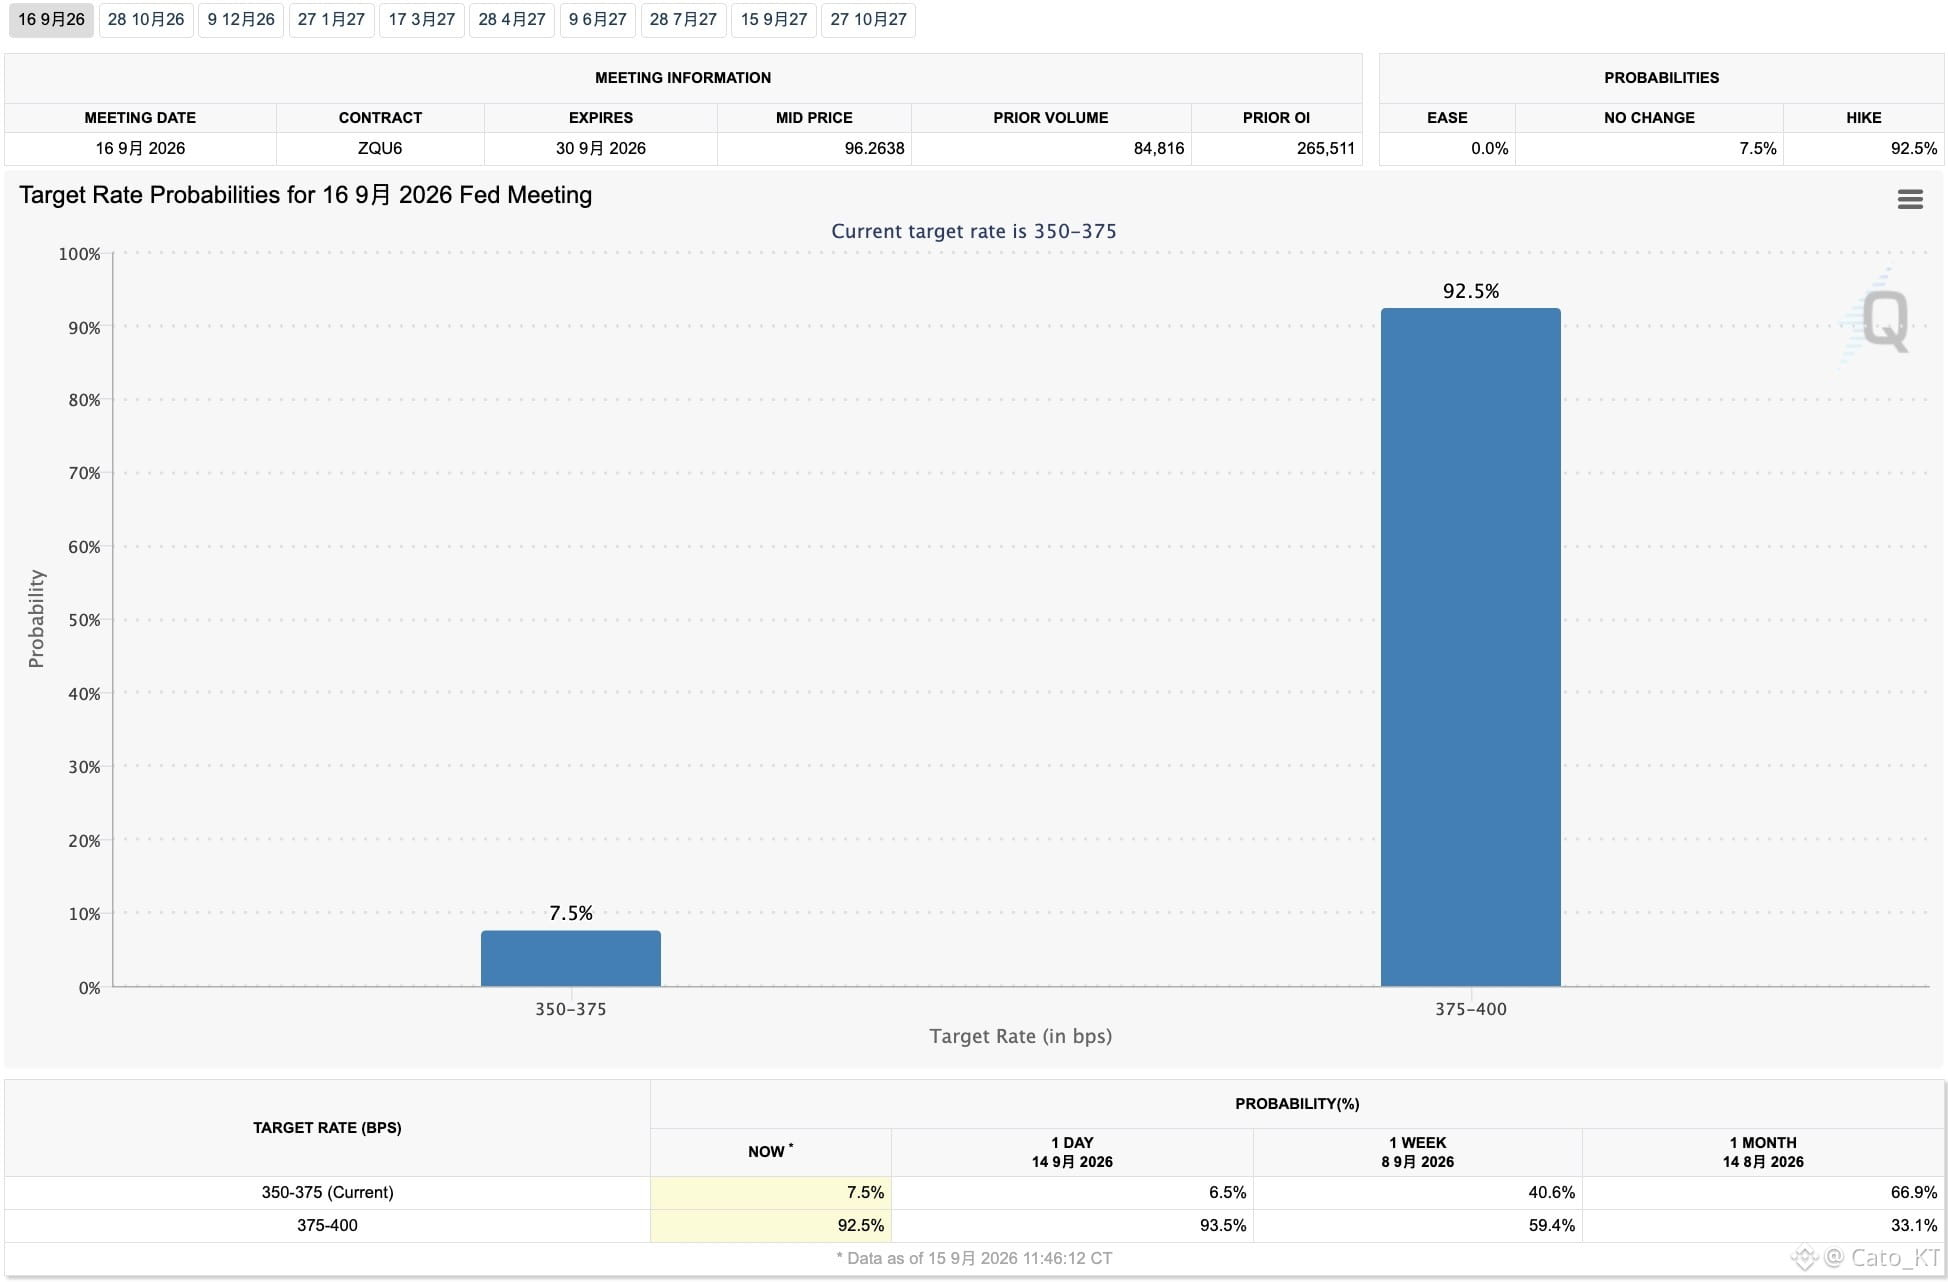
Before the rate decision meeting, the odds of a September rate hike have been pushed up to over 90%, essentially locking it in by probability. Next, it’s not about whether the hike is confirmed, but about how the market behaves after the hike is actually carried out.
Tomorrow night, the 25bp hike is set to be confirmed. US stocks and #Bitcoin will dip slightly and then rebound. After the “bad news” shoe drops, the focus shifts to the rebound pattern—then we’ll watch for remarks by Mr. Waller.
A hawkish hike: in the future, rate-hike expectations rise further; bond yields are suppressed; high oil prices; and a global rate-hike convergence—all of which could push risk markets to delever even more, with volatility and prices falling.
A dovish hike: rate-hike expectations weaken in the future. Risk markets may rebound in the short term, but afterward they still have to face the constraints brought by rising bond yields, credit/credit-risk concerns in bond markets, high oil prices and high inflation expectations, and liquidity limitations caused by the narrowing range of the US–Japan rate spread.
So looking at it this way, it doesn’t seem like things are broadly optimistic. Although subsequent uncertainty doesn’t necessarily mean risks will definitely materialize 100%, these risk factors will become “pits” that suppress risk markets. Risk markets need to eliminate these risks one by one!
All the uncertainties revolve around one core factor—high oil prices. After the hike is implemented, if we still see a triple selloff across equities, bonds, and FX, why wouldn’t Trump not TACO? #美联储加息是否已成定局
Tomorrow night, the 25bp hike is set to be confirmed. US stocks and #Bitcoin will dip slightly and then rebound. After the “bad news” shoe drops, the focus shifts to the rebound pattern—then we’ll watch for remarks by Mr. Waller.
A hawkish hike: in the future, rate-hike expectations rise further; bond yields are suppressed; high oil prices; and a global rate-hike convergence—all of which could push risk markets to delever even more, with volatility and prices falling.
A dovish hike: rate-hike expectations weaken in the future. Risk markets may rebound in the short term, but afterward they still have to face the constraints brought by rising bond yields, credit/credit-risk concerns in bond markets, high oil prices and high inflation expectations, and liquidity limitations caused by the narrowing range of the US–Japan rate spread.
So looking at it this way, it doesn’t seem like things are broadly optimistic. Although subsequent uncertainty doesn’t necessarily mean risks will definitely materialize 100%, these risk factors will become “pits” that suppress risk markets. Risk markets need to eliminate these risks one by one!
All the uncertainties revolve around one core factor—high oil prices. After the hike is implemented, if we still see a triple selloff across equities, bonds, and FX, why wouldn’t Trump not TACO? #美联储加息是否已成定局