

Binance’s brothers and sisters—crypto professional traders’ weekly macro battle manual is here again
Crypto professional traders’ weekly macro battle manual September 14, 2026 to September 20, 2026—super central banks week: the U.S. Federal Reserve, the Bank of England, the Bank of Japan, and China—August economic data
This week is the restart of the rate-hike cycle—CME FedWatch’s pricing for the September rate hike probability has surged from 36% two weeks ago to 86.5% (unchanged at 13.5% if it stays put). The target range is 3.50%-3.75% → 3.75%-4.00%. #The Fed Chair is already #Kevin Warsh (hawkish). The August core CPI month-over-month at 0.3% beating expectations by “the last puzzle piece.” This isn’t a bet on whether they will raise rates—it’s a bet on how many times they’ll raise rates, and whether it’s a cycle.
Ø, benchmark pricing (required every Sunday night—this is the anchor for all quant strategies)
Variable current value; key changes this week BTC/USD ≈ 77,440 (9/14 morning, +0.3% on the day) tightly at the 38.2% #Fibonacci 76,380 core support 76,380 (38.2% retracement of the June low 57,766 → Aug high 82,130), real market average below 76,600; break below = deeper retracement; key resistance 79,600 (50-week moving average) → 82,000–82,800 (weekly dual resistances) ETF average cost 82,465 2-year US Treasury at 4.63% Decisison eve leading indicator 10-year at 4.97% >5.0% ; headwind for BTC: US Dollar Index DXY 98.90 Rate hikes → DXY up → BTC under pressure Brent crude oil >$100 → oil up → inflation expectations up → indirect pressure on BTC Weekly increase about 9% Source of the inflation chain BTC and gold 90-day correlation +0.56 (highest since 2020) Tailwind: the stagflation-hedge narrative BTC vs Nasdaq 100 correlation ≈ 0 This round’s “equity-crypto decoupling”
Three iron laws (determine all positions for this week):
Correlation between BTC and real rates: -0.72. A 25bp hike was already priced in by 86%. “Shoes landing” volatility is usually only ~1.0x (weaker than 2.0x for Nonfarm payrolls and 1.8x for core CPI). The real killer is forward guidance. “One hike = bearishness exhausted; opening a cycle = systemic selloff.” BNY: “If Waller says ‘we have more work to do,’ it’s not good for markets.” BTC has extremely limited room to operate around 76,380; frequent testing = support exhaustion.
1. Daily battle map + quant thresholds
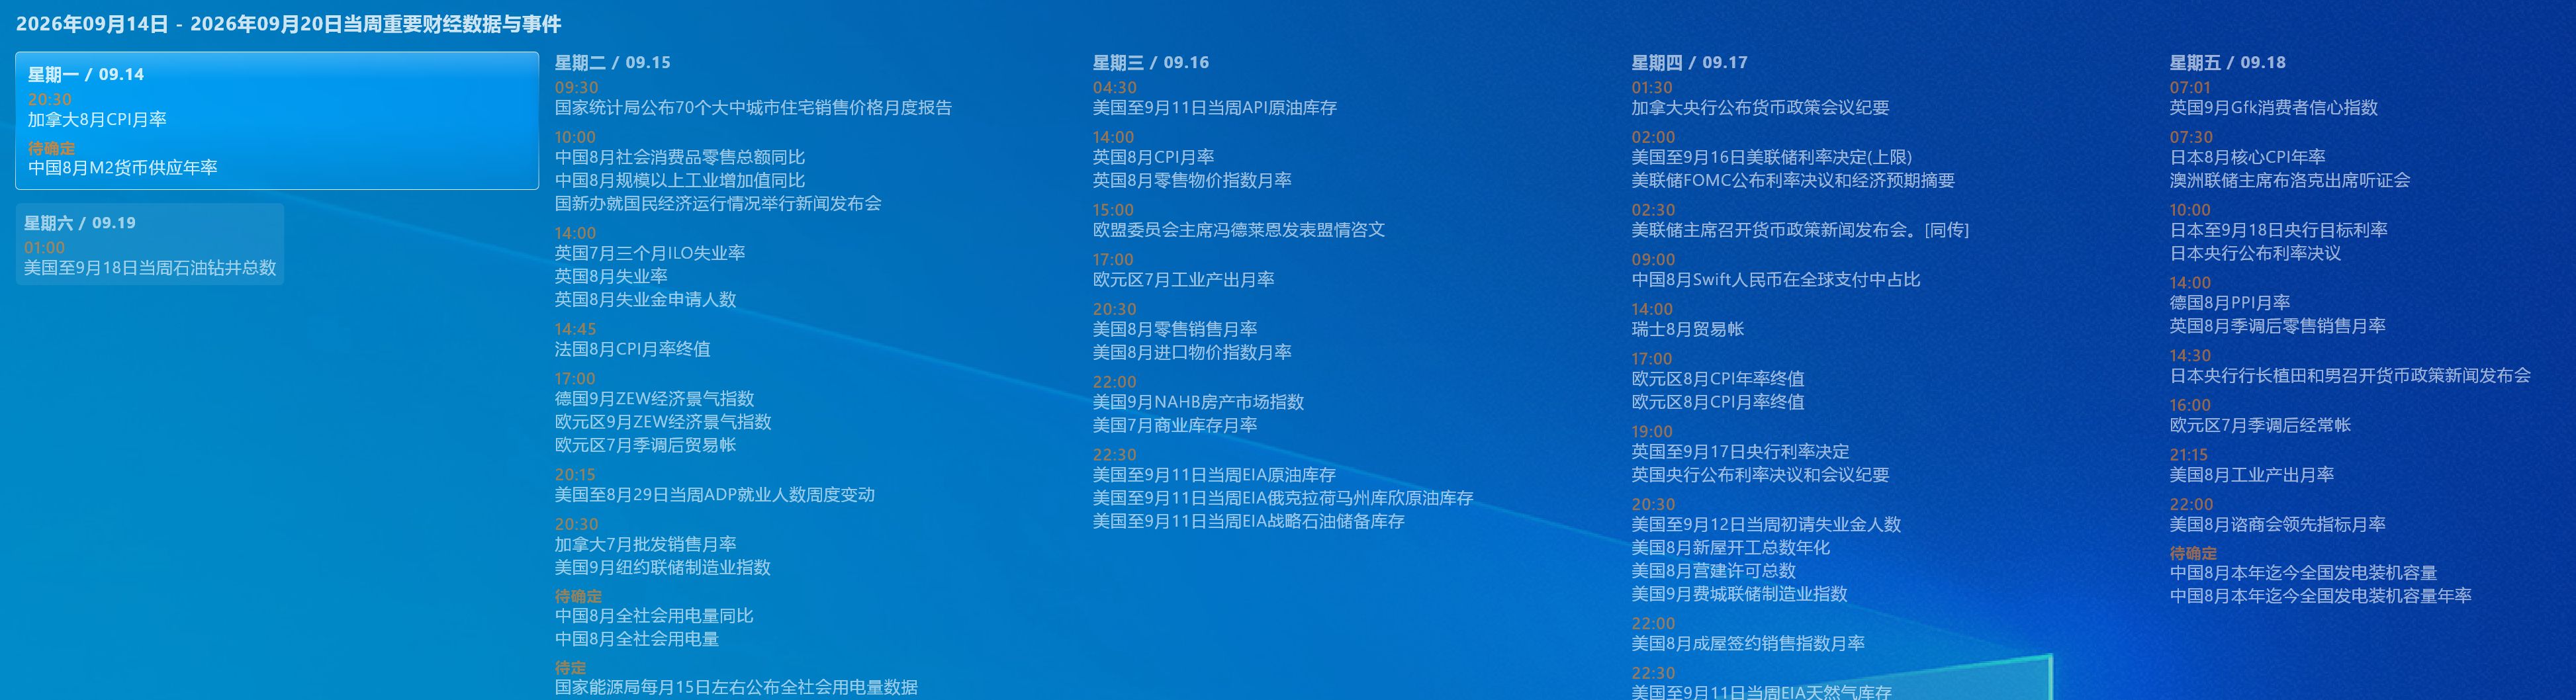
Monday 9/14 | PMI sets the tone + briefing from the State Council Information Office
20:30 Canada Aug CPI MoM: goods-currency inflation, indirectly affecting the USD TBD China Aug M2 YoY: market expectations 7.6%–7.7% (prior 7.7%); credit is weak (estimated new loans only 100–500 billion RMB, lower YoY increase) Background: 15:00 briefing from the State Council Information Office policy routine; 09:30 Australia RBA Chair Brock hearing (the chart’s 9/15 items; note time-zone conversion)
# Quant rule: If on Monday BTC holds 76,380 and stays above/firm over MA5 (77,135), maintain a neutral position. If during the Asian session BTC breaks below 76,380 due to M2 missing expectations and fails to reclaim within 15 minutes → cut longs to 30%, move stop-loss lower.
Tuesday 9/15 | China Aug real economy (09:30/10:00—major items) + Canada Central Bank meeting minutes
09:30 Canada Aug CPI MoM 10:00 China Aug retail sales / industrial value-added above designated size / State Council Information Office national economic briefing
Market expectations: retail sales YoY 0.8%–1.0%, industrial value-added 4.6%–4.8%, cumulative fixed-asset investment -7% China CPI has already rebounded to 0.8%, PPI 3.8%
14:00 UK 3-month ILO unemployment rate (July) / unemployment rate (August) / unemployment benefit claimants 17:00 Eurozone 9月 ZEW economic sentiment index / July seasonally adjusted trade balance 20:15 US weekly ADP employment change for the week ending Aug 29 (this week the ADP methodology has changed—note comparability) 20:30 Canada July wholesale sales MoM / US September New York Fed manufacturing index 14:45 France August CPI MoM final
Key linkage: China data weak + M2 trending down → pressure on RMB-denominated assets → capital outflows during the Asian session → BTC likely faces early-session pressure; however, with expectations for Chinese easing heating up, there’s a long-term liquidity tailwind.
Quant rules: If China’s data broadly misses expectations, BTC should first test the 76,380→74,800 zone in the early session; if retail sales >1.0% and industrial value-added >4.8%, treat it as risk-on support.
Wednesday 9/16 | API+EIA crude oil + US retail + State of the Union address + before the rate decision—last data
04:30 US weekly API crude oil inventories for the week ending Sep 11 14:00 UK Aug CPI MoM / Retail Price Index MoM → determines the divergence in the BoE vote for 9/17 15:00 von der Leyen delivers State of the Union address (geopolitical risk premium) 17:00 Eurozone July industrial production MoM 20:30 US Aug retail sales MoM + import price index MoM ⭐
Retail sales are the consumption/inflation chain: strong results strengthen the rate-hike-cycle narrative → bearish for BTC
22:00 US Sep NAHB housing market index / July commercial inventory MoM 22:30 EIA crude oil inventories + Cushing + strategic petroleum reserves ⭐
Brent oil is already 100+; if EIA shows another draw, oil price ↑ → inflation expectations ↑ → indirect pressure on BTC
⚠️ The next day 02:00 Fed rate decision (upper bound) → after Wednesday 22:30 you must de-lever; no holding overnight high-leverage positions.
Quant rule: If EIA shows a large draw and oil breaks above the prior high → can short BTC into the Fed decision. If retail sales > expectations → the probability of a rate-hike cycle increases.
Thursday 9/17 | Super Day: Fed decision + Bank of England + Initial jobless claims (the biggest potential volatility source this week)
01:30 Canada Central Bank monetary policy meeting minutes ⭐ 02:00 Fed FOMC rate decision + Economic Projections (SEP/dot plot) 02:30 China Aug Swift RMB share of global payments 14:00 Switzerland Aug trade balance 17:00 Eurozone Aug CPI YoY/MoM final 19:00 Bank of England interest rate decision (expected to keep 3.75%, unchanged) (July already had 3 votes for a hike) ⭐ 20:30 US initial jobless claims / Aug housing starts / building permits / Philadelphia Fed manufacturing index 22:00 US Aug existing home sales contract signings 22:30 EIA natural gas inventories Fed Chair press conference (live interpretation)
This is the core of everything this Monday. Three-tier scenarios (weighted by probability in advance):
Scenario trigger conditions | BTC immediate reaction | Response strategy A. Dovish rate hike (benchmark, 45%) +25bp; statement emphasizes “one-off”; dot plot shows no further hikes—price drops first then rises; bearishness is exhausted; target retest 79,600→82,800. Before the decision, go long with a light position; add on a break above 82,800. B. Hawkish rate hike (35%) +25bp + “we have more work to do” + dot plot raises terminal rate; a breakdown leads to a selloff—if 76,380 is lost → 73,500 → 69,980. Clear longs before 02:00; on breakdown, chase shorts / buy puts. C. Unexpected hold (~20%)—keep unchanged. Short squeeze + explosive rally; ride the move to 82,800–86,000 with call options for protection; don’t short naked.
Quant hard rules:
Leverage cap: ≤2x for the full week; cut to 1x before the close on 9/16, or hedge. Disable market orders around 02:00—use limit orders with wide slip tolerance. Buy 9/19 expiry put options or straddles (event protection); cost is included in position sizing. Test “true breakout” with three indicators: Coinbase USD premium >0.3% sustained for 48h + exchange BTC net inflow negative for 3 straight days + spot active buy orders >68%.
Friday 9/18 | Bank of Japan + global central banks on the same day
07:01 UK Sep Gfk consumer confidence 07:30 Japan Aug core CPI YoY ⭐ 10:00 Japan target interest rate (to Sep 18) + rate decision: markets are almost fully pricing a 25bp hike to 1.25% (highest in 31 years), with some bets on 50bp 14:00 Germany Aug PPI MoM / UK Aug seasonally adjusted retail sales MoM 14:30 BOJ Governor Ueda Kazu news conference 16:00 Eurozone July seasonally adjusted current account ⭐ 21:15 US Aug industrial production MoM / 22:00 Conference Board leading indicators MoM → verify whether the economy is “hard/soft”
Transmission of Japan’s rate hike: JPY strengthens → carry trades unwind → global risk-asset liquidity tightens → BTC under pressure. Overnight index swaps price the September rate-hike probability at nearly 100%.
Quant rule: If BOJ unexpectedly +50bp → USD/JPY plunges → BTC in Asia likely follows lower. Set a bounce-long order in advance at 73,500.
China 9/18 TBD: Aug power generation installed capacity YoY (energy-chain narrative, weak impact)
Saturday 9/19 | wrap-up
01:00 US total number of oil rigs drilled for the week ending Sep 18 (low impact, but weekend thin liquidity + needle risk)
2. This week’s quant framework (can be executed directly)
Position matrix (by scenario probability)
Time-slot benchmark position note: Mon–Wed 20:30 neutral, 40–50% for data-driven battles; don’t chase. After Wed 22:30 until Thu 02:00: ≤20% or hedge. Before the decision: stay flat / buy protection. After Thu 02:30: execute A/B/C by scenario in trend, not against it. After Fri’s BOJ? (as written: 日银) close: 30–40% to close carry-trade. Saturday reduce leverage. Weekend liquidity is thin.
Key levels (BTC/USD)
Strong resistance: 86,000 (ETF breakeven) Medium resistance: 82,000–82,800 (weekly two resistances) Weak resistance: 79,600 (50-week MA) Current price: ≈77,440 Support: 76,380–76,600 (38.2% Fib + real market average) Strong support: 73,500 / 69,980 (cost basis of short-term holders) Deep support: 62,000–65,000 (long-term accumulation zone)
Cross-market monitoring dashboard (must open before/around decisions)
DXY (US dollar index), 2Y/10Y US Treasury yields, gold (correlated with BTC +0.56) USD/JPY (via BOJ transmission), Brent crude oil (inflation source) Nasdaq futures (correlation near 0, but extreme moves can still transmit)
Derivatives risk
Open interest about $53 billion; spot trading value only $4 billion. For every $1 of spot, it corresponds to $16.75 of leverage → easy to trigger cascading liquidations. The size of September options expiry is twice that of August; derivatives concentrated expiry means higher expiry pressure. If funding rates rise quickly = an early warning of new long inflows.
3. Professional trader Checklist
Leverage: ≤2x for the entire week; be flat for 30 minutes before/around the FOMC or use options hedging. Learn from the cautionary tale: 2,850 BTC were already liquidated. Time alarm: Wed 22:30, Thu 02:00, Thu 02:30 (press conference), Fri 10:00 (Bank of Japan). Protective tools: buy 9/19 expiry puts or straddles, cost ≤ 1–2% of position. Altcoin protection: when BTC volatility >3%, altcoins often see liquidity dry-up style crashes—remove non-essential orders. Black swan playbook:
Oil prices surge again (Brent >105) + hawkish dot plot = double kill → hold stablecoin ammunition. BOJ +50bp → carry trade unwind → risk-off in Asia: Middle East / Hormuz Strait (this week shipping was attacked, oil up 9%) → gold and BTC may move in the same direction short term (risk-off hedge narrative).
Calibration signal (to verify whether the “digital gold” narrative is working): if gold rises and BTC falls, the narrative fails—switch to defense.
One-sentence summary: the 86.5% probability of “one more hike” was already priced in. You don’t make money by guessing outcomes—you make it from the phrasing in the 3-part sequence at 02:00 statement + dot plot + 02:30 press conference: whether it’s a one-off or a cycle, and lock directional risk with options. Only if you hold 76,380 do you have the right to talk about 82,800.
The above is a reference for organizing macro events and a quant trading framework; it does not constitute investment advice. Crypto markets are highly volatile—manage position sizing according to your own risk tolerance.