

The most ironic part of this news is that the attacker didn’t even use any advanced technology. Three steps—just three steps—and a “bank’s” collateral management authority was handed over to him.
On August 28, Avici, a Solana-based “on-chain new bank,” confirmed that it had been breached. Preliminary estimates place the losses between $600,000 and $1.02 million, affecting 125 user accounts. Its native token, AVICI, fell by about 39% in a day, and its current price is now down 96% from its all-time high. But behind these numbers, the real question is this: how could a project that controls other people’s card balances be so simply “upgraded” into giving an administrator access?
Three steps: from an external user to an administrator
When the attack path is laid out, it feels more like reading a vulnerability demo report than a real robbery.
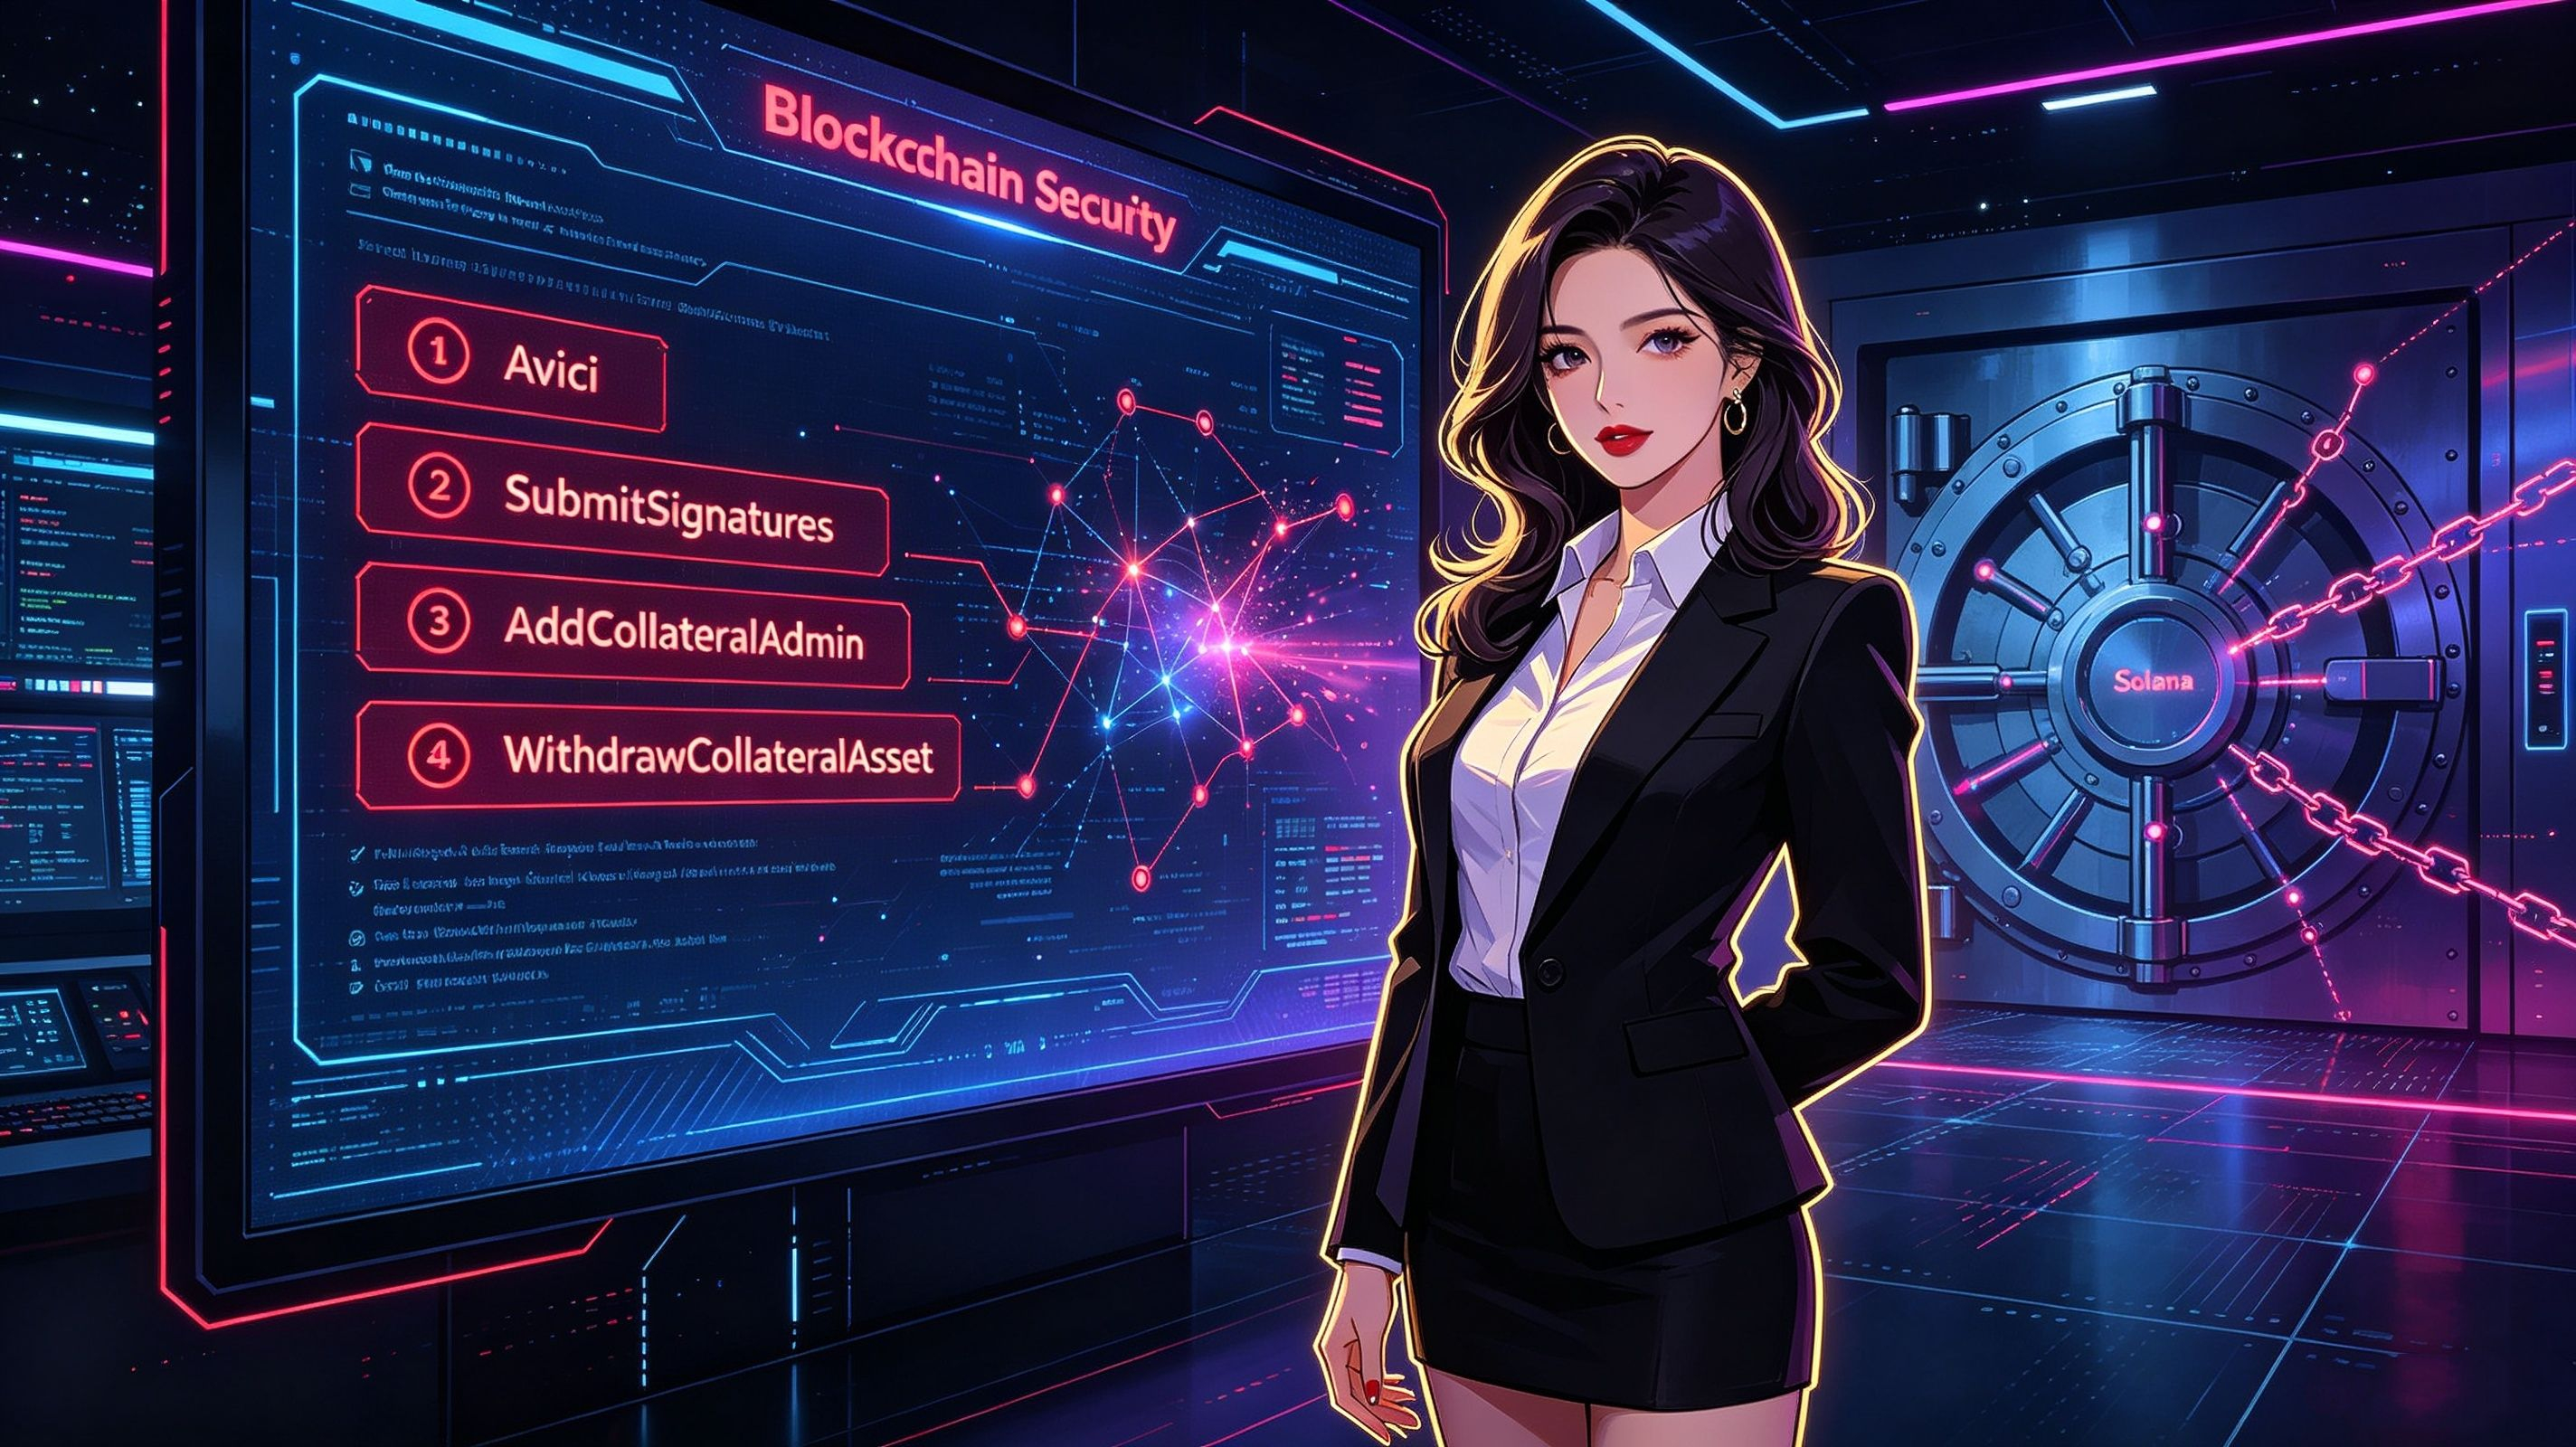
First, the hacker ran a SubmitSignatures function in Avici’s authorization program. Second, on the collateral program, they called AddCollateralAdmin. Third, using the newly obtained administrator privileges, they called WithdrawCollateralAsset and took the assets away.
In plain language: first they got a signature authorization, then they gave themselves administrator status, and finally they used that status to withdraw the collateral. No arbitrage, no flash loan, no oracle manipulation. It was simply a loophole in permissions: they walked in through the front door, opened the safe, and took the stuff away.
At the time, the attacker held about 10,005 SOL in the wallet, worth $1.07 million, plus $11,600 in stablecoins. On-chain analysts traced it and found that among the 125 affected accounts, the largest loss was 26,000 USDT, while the smallest was only 9 USDC. What does this mean? It means this was not a targeted strike against large holders, but a blanket sweep against everyone who kept money there. Retail users’ card balances disappeared in an instant.
Where did the money go? Almost no hope
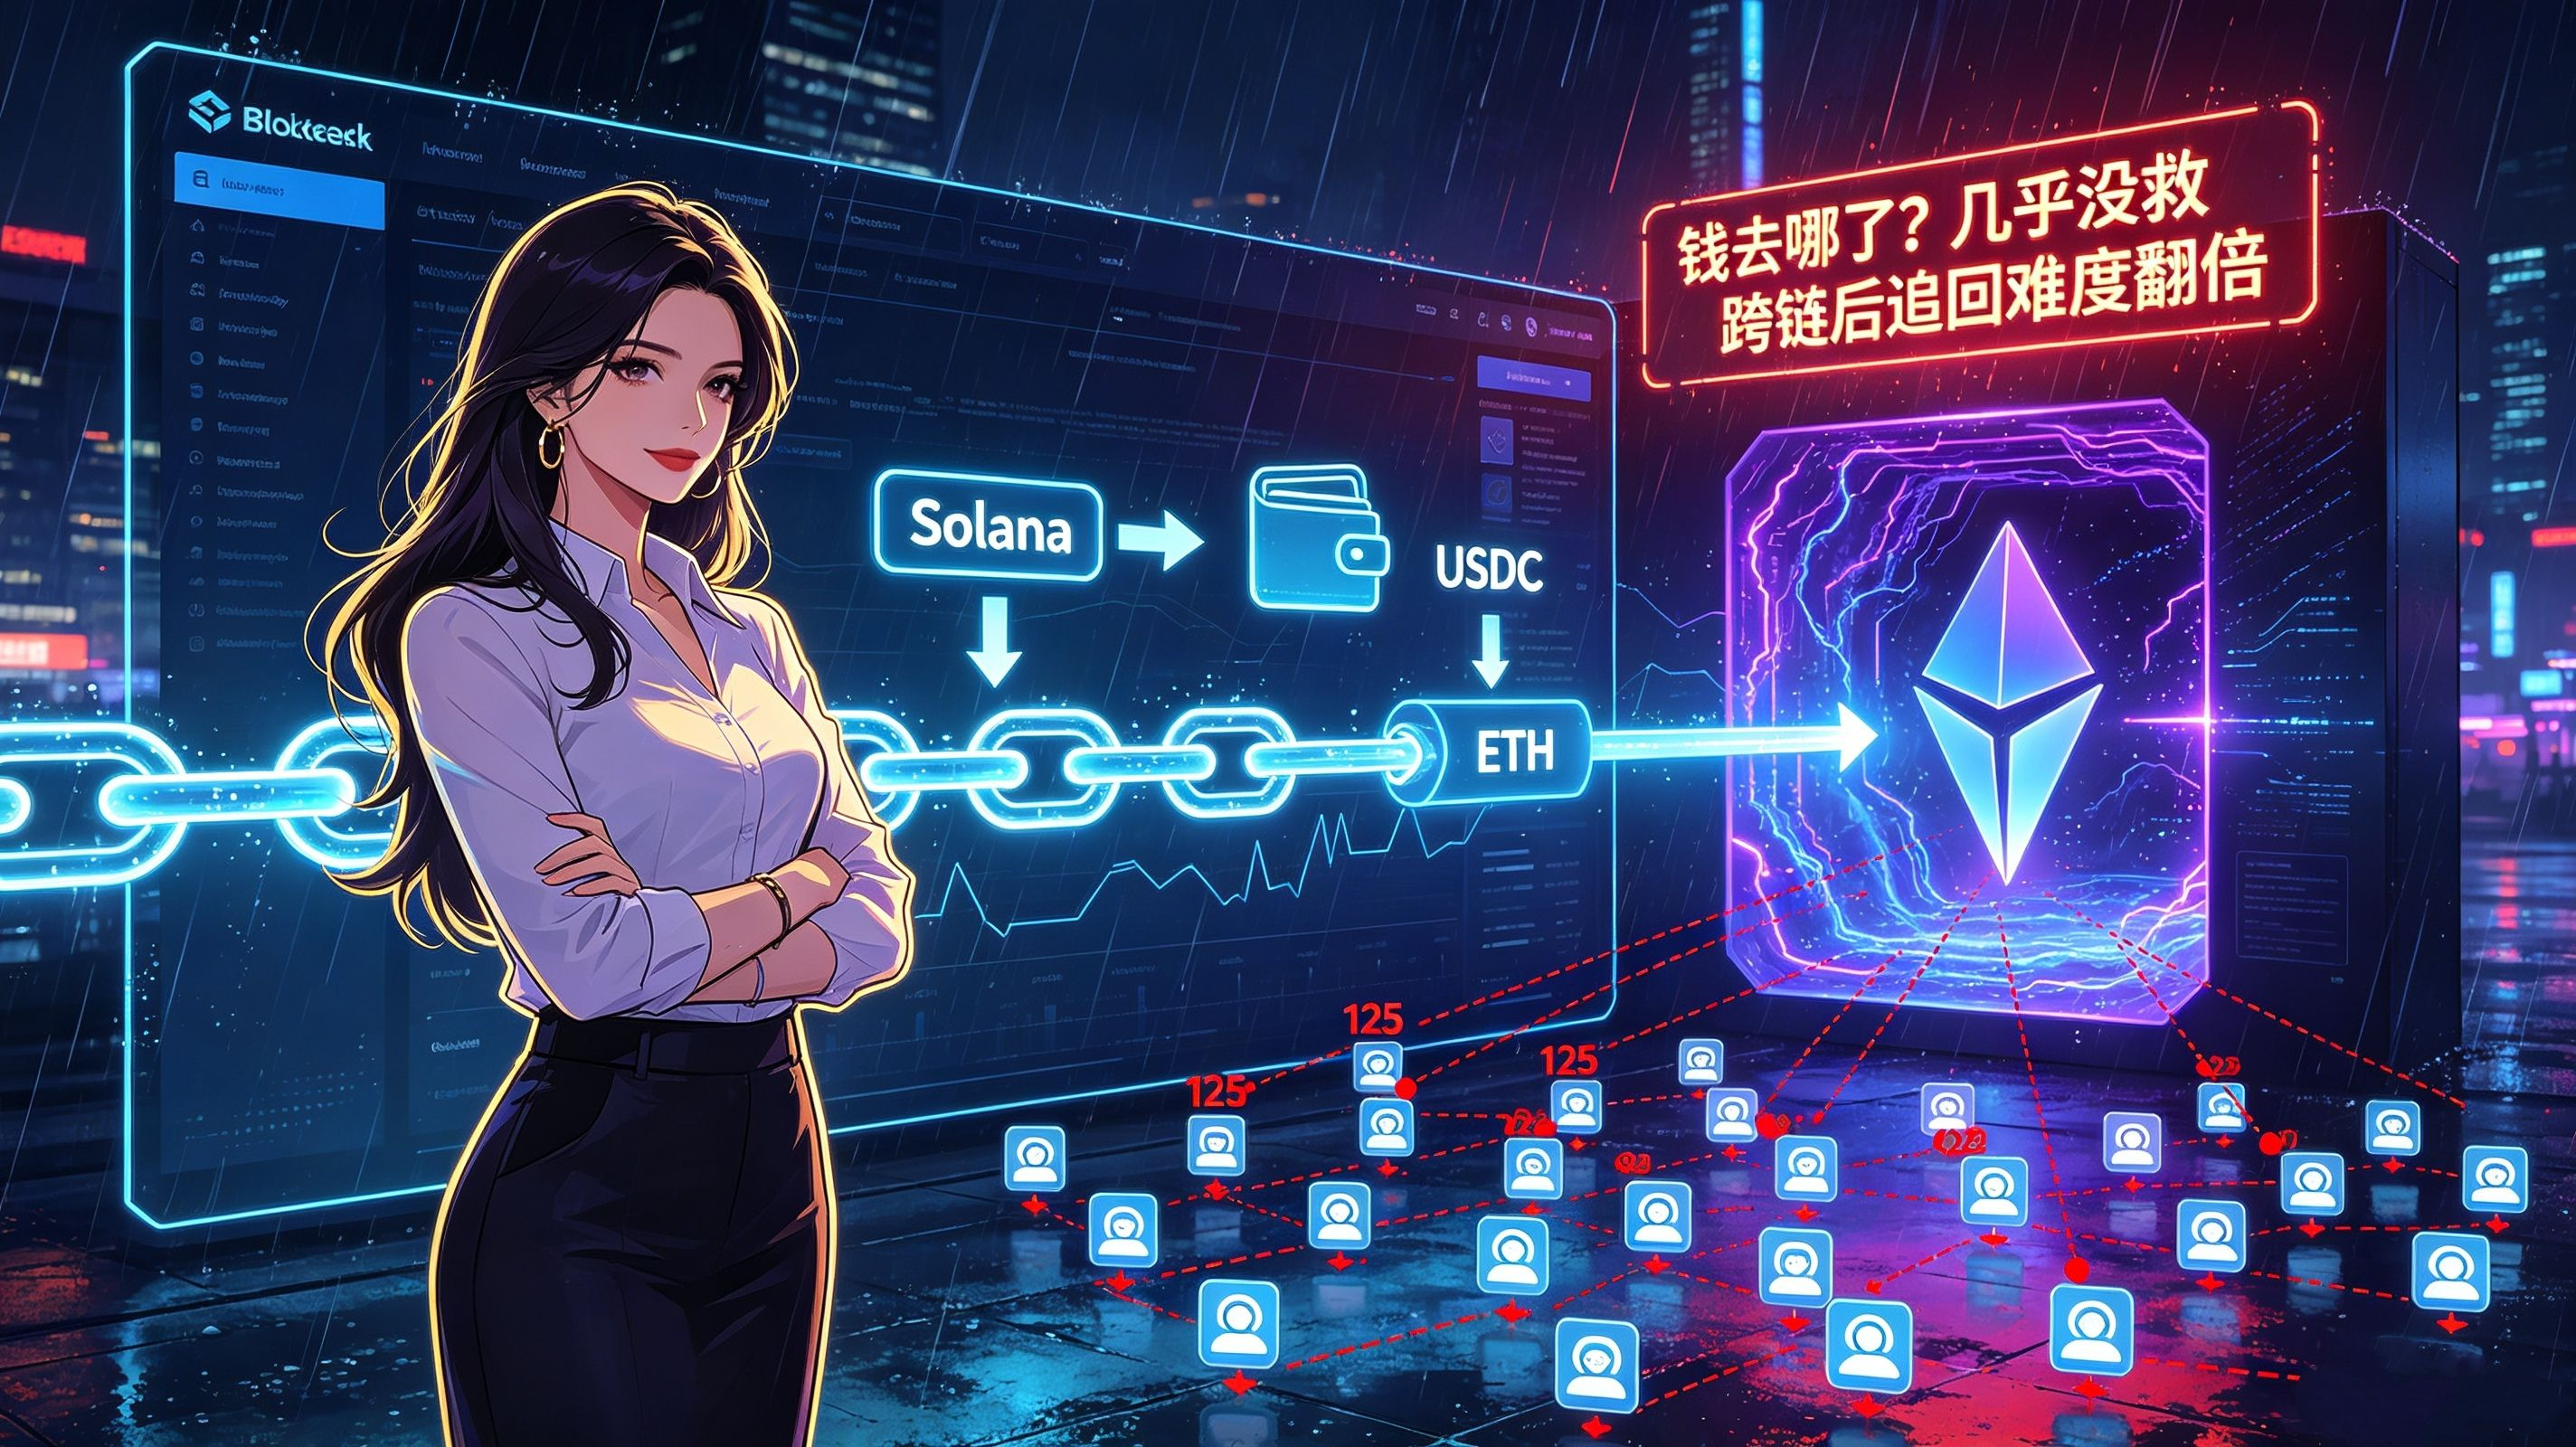
Monitoring by Onchain Lens also pieced together the fund flow: 10,000 SOL transferred out, swapped for about 1.02 million USDC, bridged over, converted into about 418 ETH, and finally left on Ethereum.
Seeing this path, the victim can basically give up hope. The attacker didn’t leave the funds on Solana, but switched chains at lightning speed. Cross-chain movement itself doubles the difficulty of recovery. Once the money becomes ETH and is mixed into the torrent of Ethereum, getting it back is about as hard as finding a needle in a haystack.
The market is more honest than anyone else: it stopped believing long ago
AVICI’s price reaction is closer to the truth than any announcement. It fell 39% in 24 hours, with the current price at $0.2175. And it had once touched $7.61 on November 26, 2025. What does a 96% drop mean? It means the market had already mostly abandoned the project before the hacker attack. The attack just punctured the last layer of paper.
What’s even more unsettling is the official response. Avici confirmed on X that there was a problem affecting card balance withdrawals, but didn’t mention the amount lost or whether there would be compensation. For the people behind the 125 accounts, losing money is already a fact; what really keeps them awake at night is another question: will this money ever come back?
The real trust crisis is hidden in the words “new bank”
The “on-chain new bank” narrative on Solana has been a rather lively theme in this cycle. Using crypto assets as backing to provide card balances for spending sounds like bringing banking onto the chain. But Avici used a textbook permission vulnerability to remind everyone: having the word “bank” in the name doesn’t mean having the bottom line of a bank.
Traditional banks are backed by deposit insurance, risk controls, and regulatory backstops; when something goes wrong, there are institutions to handle it. What about on-chain new banks? Assets are just a few collateral positions on-chain, and permissions are just a few smart contract functions. Once the permissions on those functions are exploited, there’s nothing left. No insurance, no fallback, no option where “the money doesn’t come back but the state compensates you.” Every cent you deposit is tied to the rigor of the contract. And Avici happened to prove one thing: its contract rigor was basically zero.
This isn’t an isolated incident; this week has been far too dense
If you look at Avici alone, you might think it was an accident. But when you pull this week together, you’ll find that the density and direction of attacks have changed.
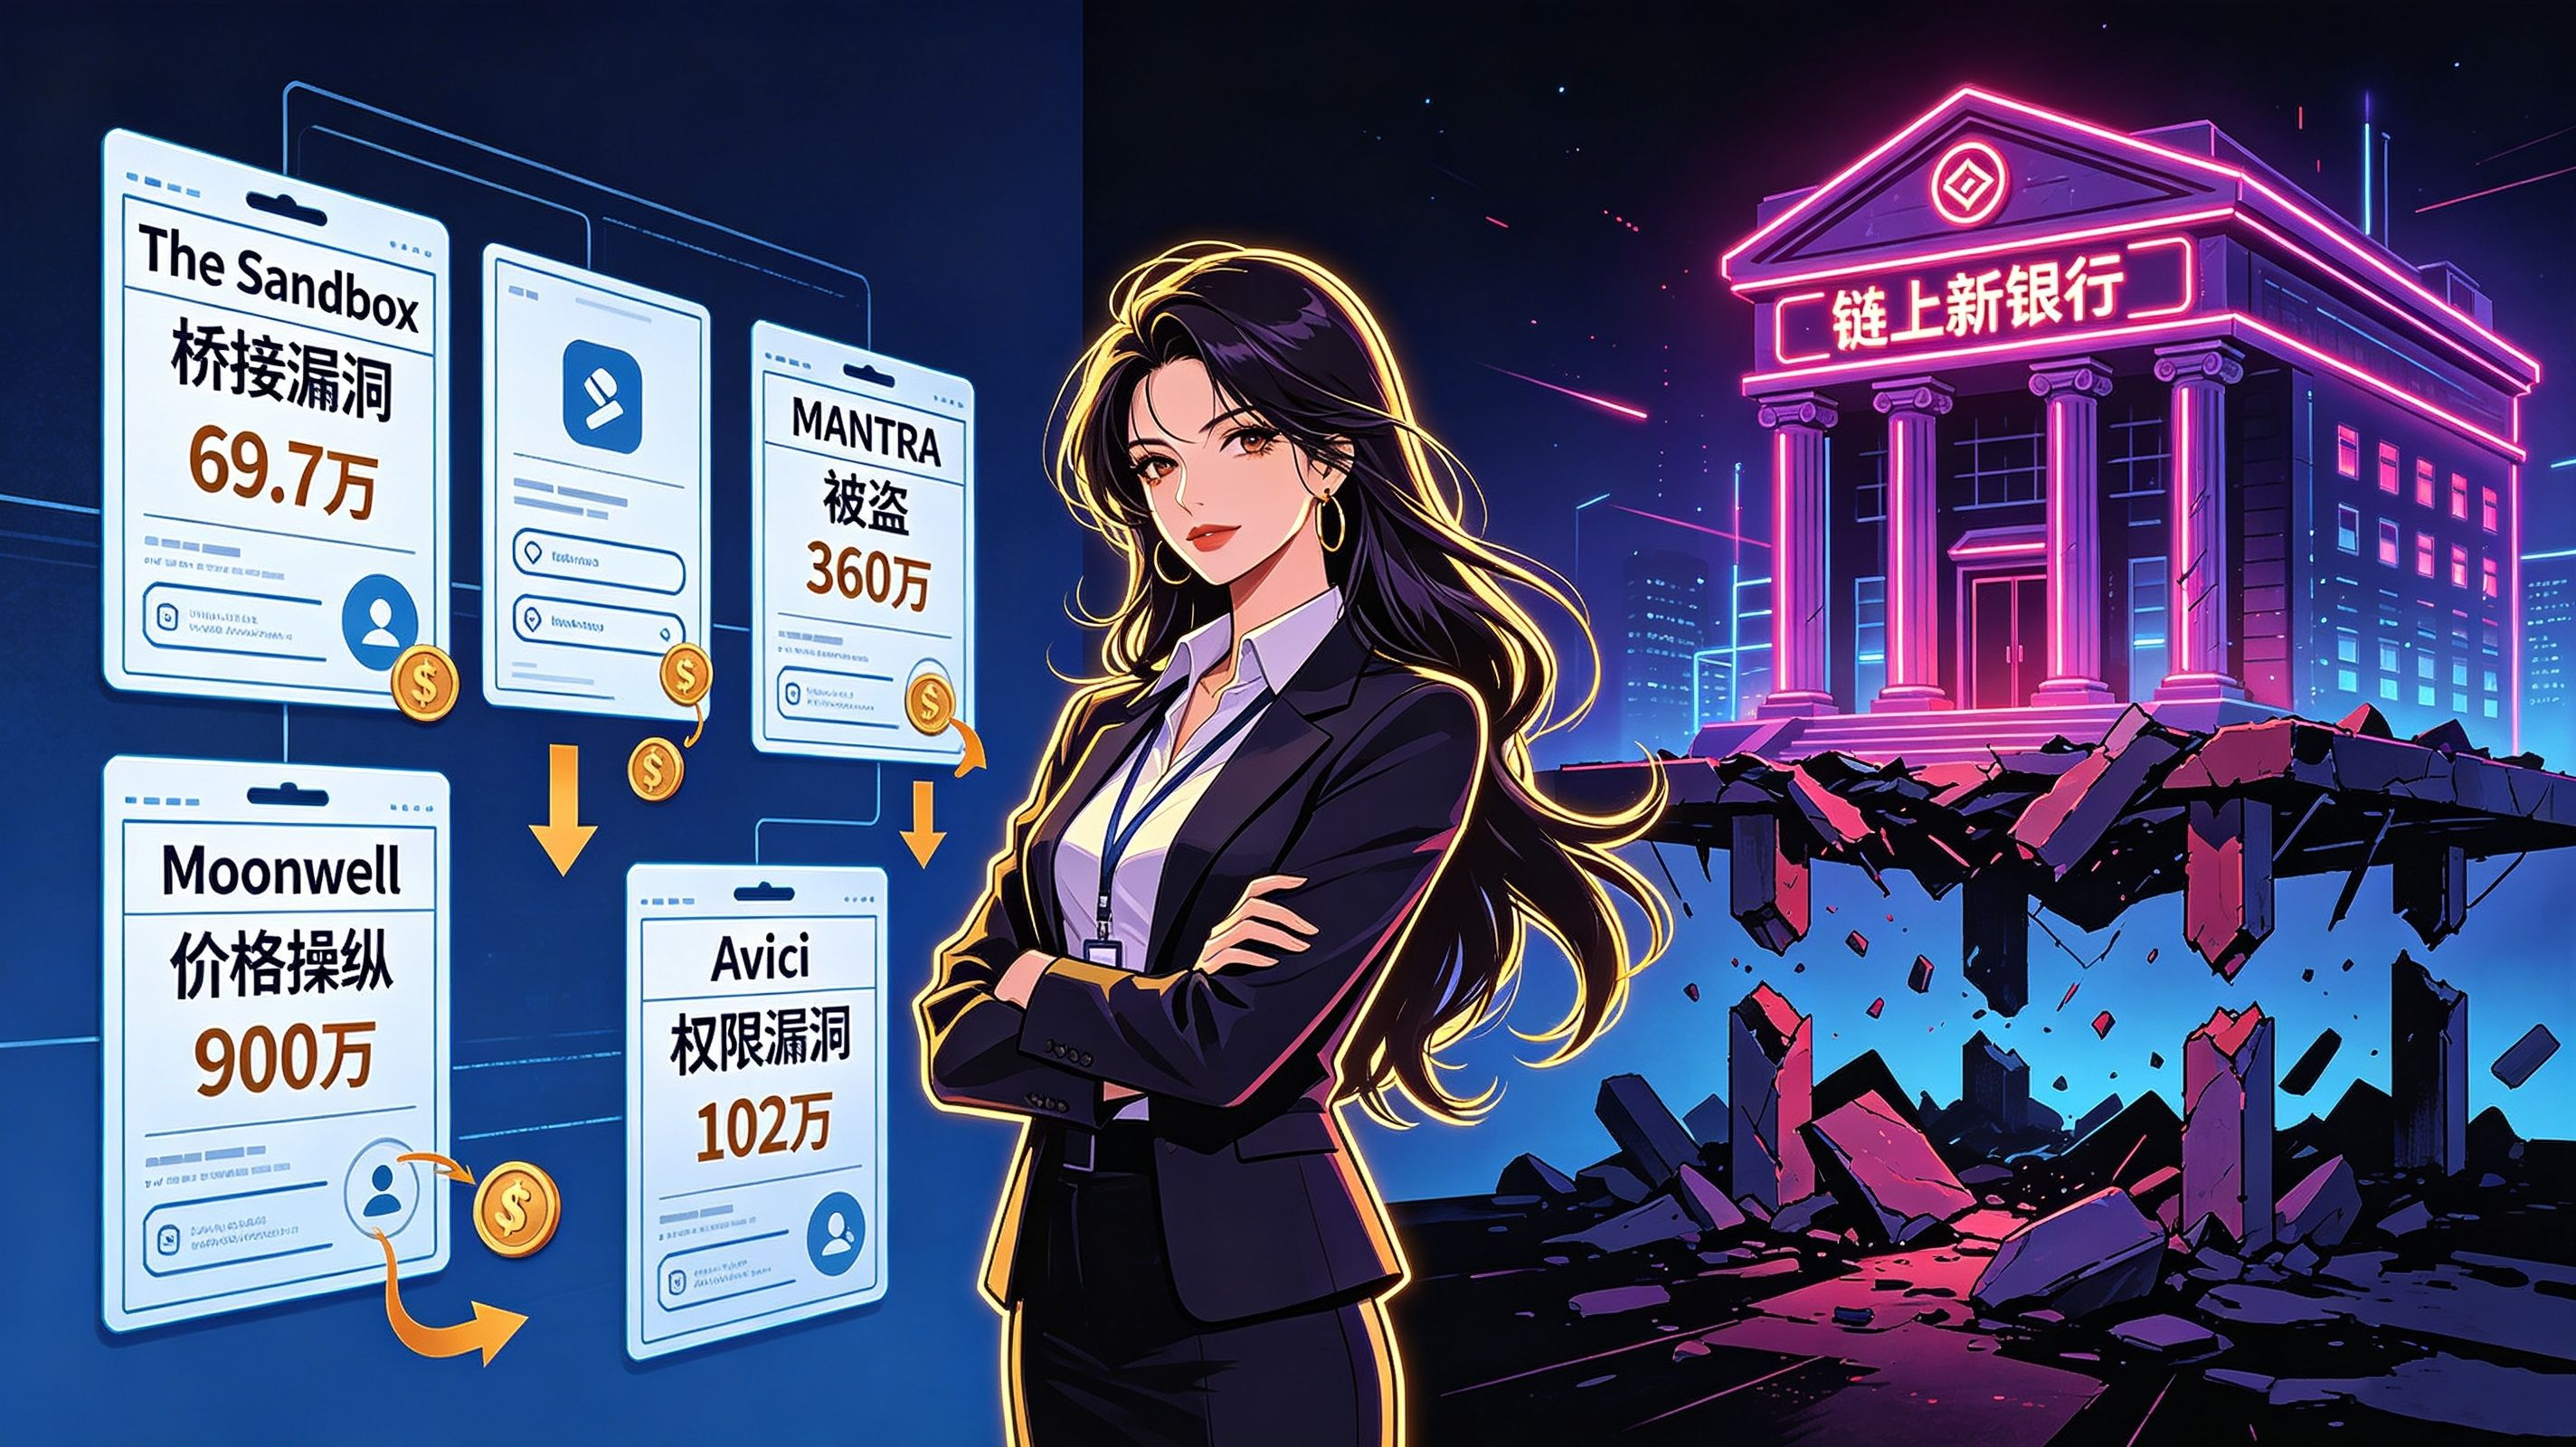
The Sandbox bridge vulnerability caused losses of about $697,000, but fortunately the project said it would compensate 1:1. MANTRA was stolen from for about $3.6 million, and no recovery plan was mentioned. The lending protocol Moonwell was hit by a price manipulation attack a few days ago, losing about $9 million. Then there’s Avici, at $1.02 million and 125 accounts.
The common thread in these events is that the targets are no longer just the big treasuries of a single protocol, but services that hold real funds for users—bridges, lending protocols, on-chain banks. The victims have shifted from “institutional money” to “retail demand deposits.” The social impact of that is far greater than the dollar amount alone.
So what is the real thing this news should make us remember?
It’s not just “another 1 million lost.” Losing 1 million in crypto happens every week. What should be remembered is that when a project calls itself a “bank” but can’t even protect administrator privileges, it’s more dangerous than a regular DeFi protocol. Because users have an innate trust in the word “bank,” and that trust makes many people relax their guard and put assets in places they shouldn’t.
For ordinary users, this is a very practical reminder: before putting money into any “on-chain bank,” first ask whether it has deposit insurance, a risk control system, and regulatory backstops. If the answer is all “no,” then at best it’s just a piggy bank with the word “bank” added on. When a piggy bank breaks, nobody will compensate you.
Whether Avici can boldly promise compensation like The Sandbox, or vaguely gloss over it like MANTRA, will be the final turning point for it. But the bigger question is left to the entire industry: when on-chain new banks compete to take over users’ card balances, whoever first builds a truly credible security and compensation system is the one deserving to keep using the name “bank.” Before that, the four words “on-chain bank,” no matter how nice they sound, are still just four words.
Risk warning: This article is only a compilation of information and an analysis of a security incident, and does not constitute investment advice. The Avici security vulnerability is still under investigation, and the loss amount, number of affected accounts, and compensation plan have not yet been finalized; AVICI is a highly volatile token, and its price has fallen sharply from its historical high. Other security incidents mentioned in the article are disclosed information, and actual losses and recovery progress are subject to official announcements. Please do not make any investment decisions based on this, and be mindful of the risks.