

On August 24, the U.S. Treasury launched a new round of sanctions against Iran, officially called “Economic Isolation Actions.” Treasury Secretary Bessent’s wording was very tough, saying they would “cut off all economic lifelines supporting this despotic regime.” What really has the crypto industry on edge is that this time, unusually, “digital assets” were also included within the scope of the sanctions.
But here’s the question: who exactly is being sanctioned? Is it Iran’s exchanges and money brokers—or the decentralized infrastructure that has no center, no KYC, and no address book? The Treasury didn’t say.
This “didn’t say,” is precisely the most dangerous part of the whole affair.
The secondary sanctions net is spreading wider and wider, but nobody is telling you where the boundaries are
First, let’s explain a concept. The core of this action is to expand “secondary sanctions” — even if you are not on the sanctions list, you could still be affected as long as you do business with a sanctioned entity. Simply put, it is a net that says, “Whoever does business with Iran, don’t even think about touching the U.S. dollar system.”
Traditionally, this net has covered industries like technology, gold, aviation, and shipping. Now, digital assets have been added. That means Iranian exchanges, shell companies, and brokers could all be targeted as long as they use on-chain funding channels.
But the Treasury did not make one thing clear: is the decentralized protocol itself a target? Nodes run all over the world, miners do not know for whom they are packaging transactions, and relayers do not know what they are forwarding. If these also count as “doing business with Iran,” then this net will cover the whole industry, no matter where you are and no matter whether you wrote the code.
Coin Center’s executive director, Peter Van Valkenburgh, used a very precise word to describe the Treasury’s statement — “fairly neutral.” Neither good nor bad, but ambiguous. It mentioned digital assets and intermediaries, but provided no details. For regulators, this kind of ambiguity is a toolbox; for the industry, it is a sword hanging overhead. You never know when it will fall, or on whose head.
The compliance that is actually being done is, instead, being ignored
Van Valkenburgh said something very practical on the podcast: if the authorities really want to act, the enforcement focus should be on “custodial institutions” — Iranian exchanges, shell companies, brokers, and fund networks. These institutions directly control funds and hold customer information, making them the most reasonable and workable leverage for sanctions.
The fact is, such compliance mechanisms have long existed at the fringes of the crypto market. Stablecoin issuers are already screening addresses, and app front ends like Uniswap are also cooperating with sanctions lists. Both Circle and Tether can freeze designated addresses. The transparency of public blockchains, on the contrary, makes the flow of sanctioned funds monitorable in real time.
In other words, what really should be regulated—and can be regulated—are entities with human intervention, not tearing down an ownerless network that simply cannot be dismantled. But the Treasury’s wording did not rule out the latter. It did not even give any signal that it does not intend to go after non-custodial infrastructure.
Why is the question of whether “writing code counts as a crime” more important than the sanctions themselves
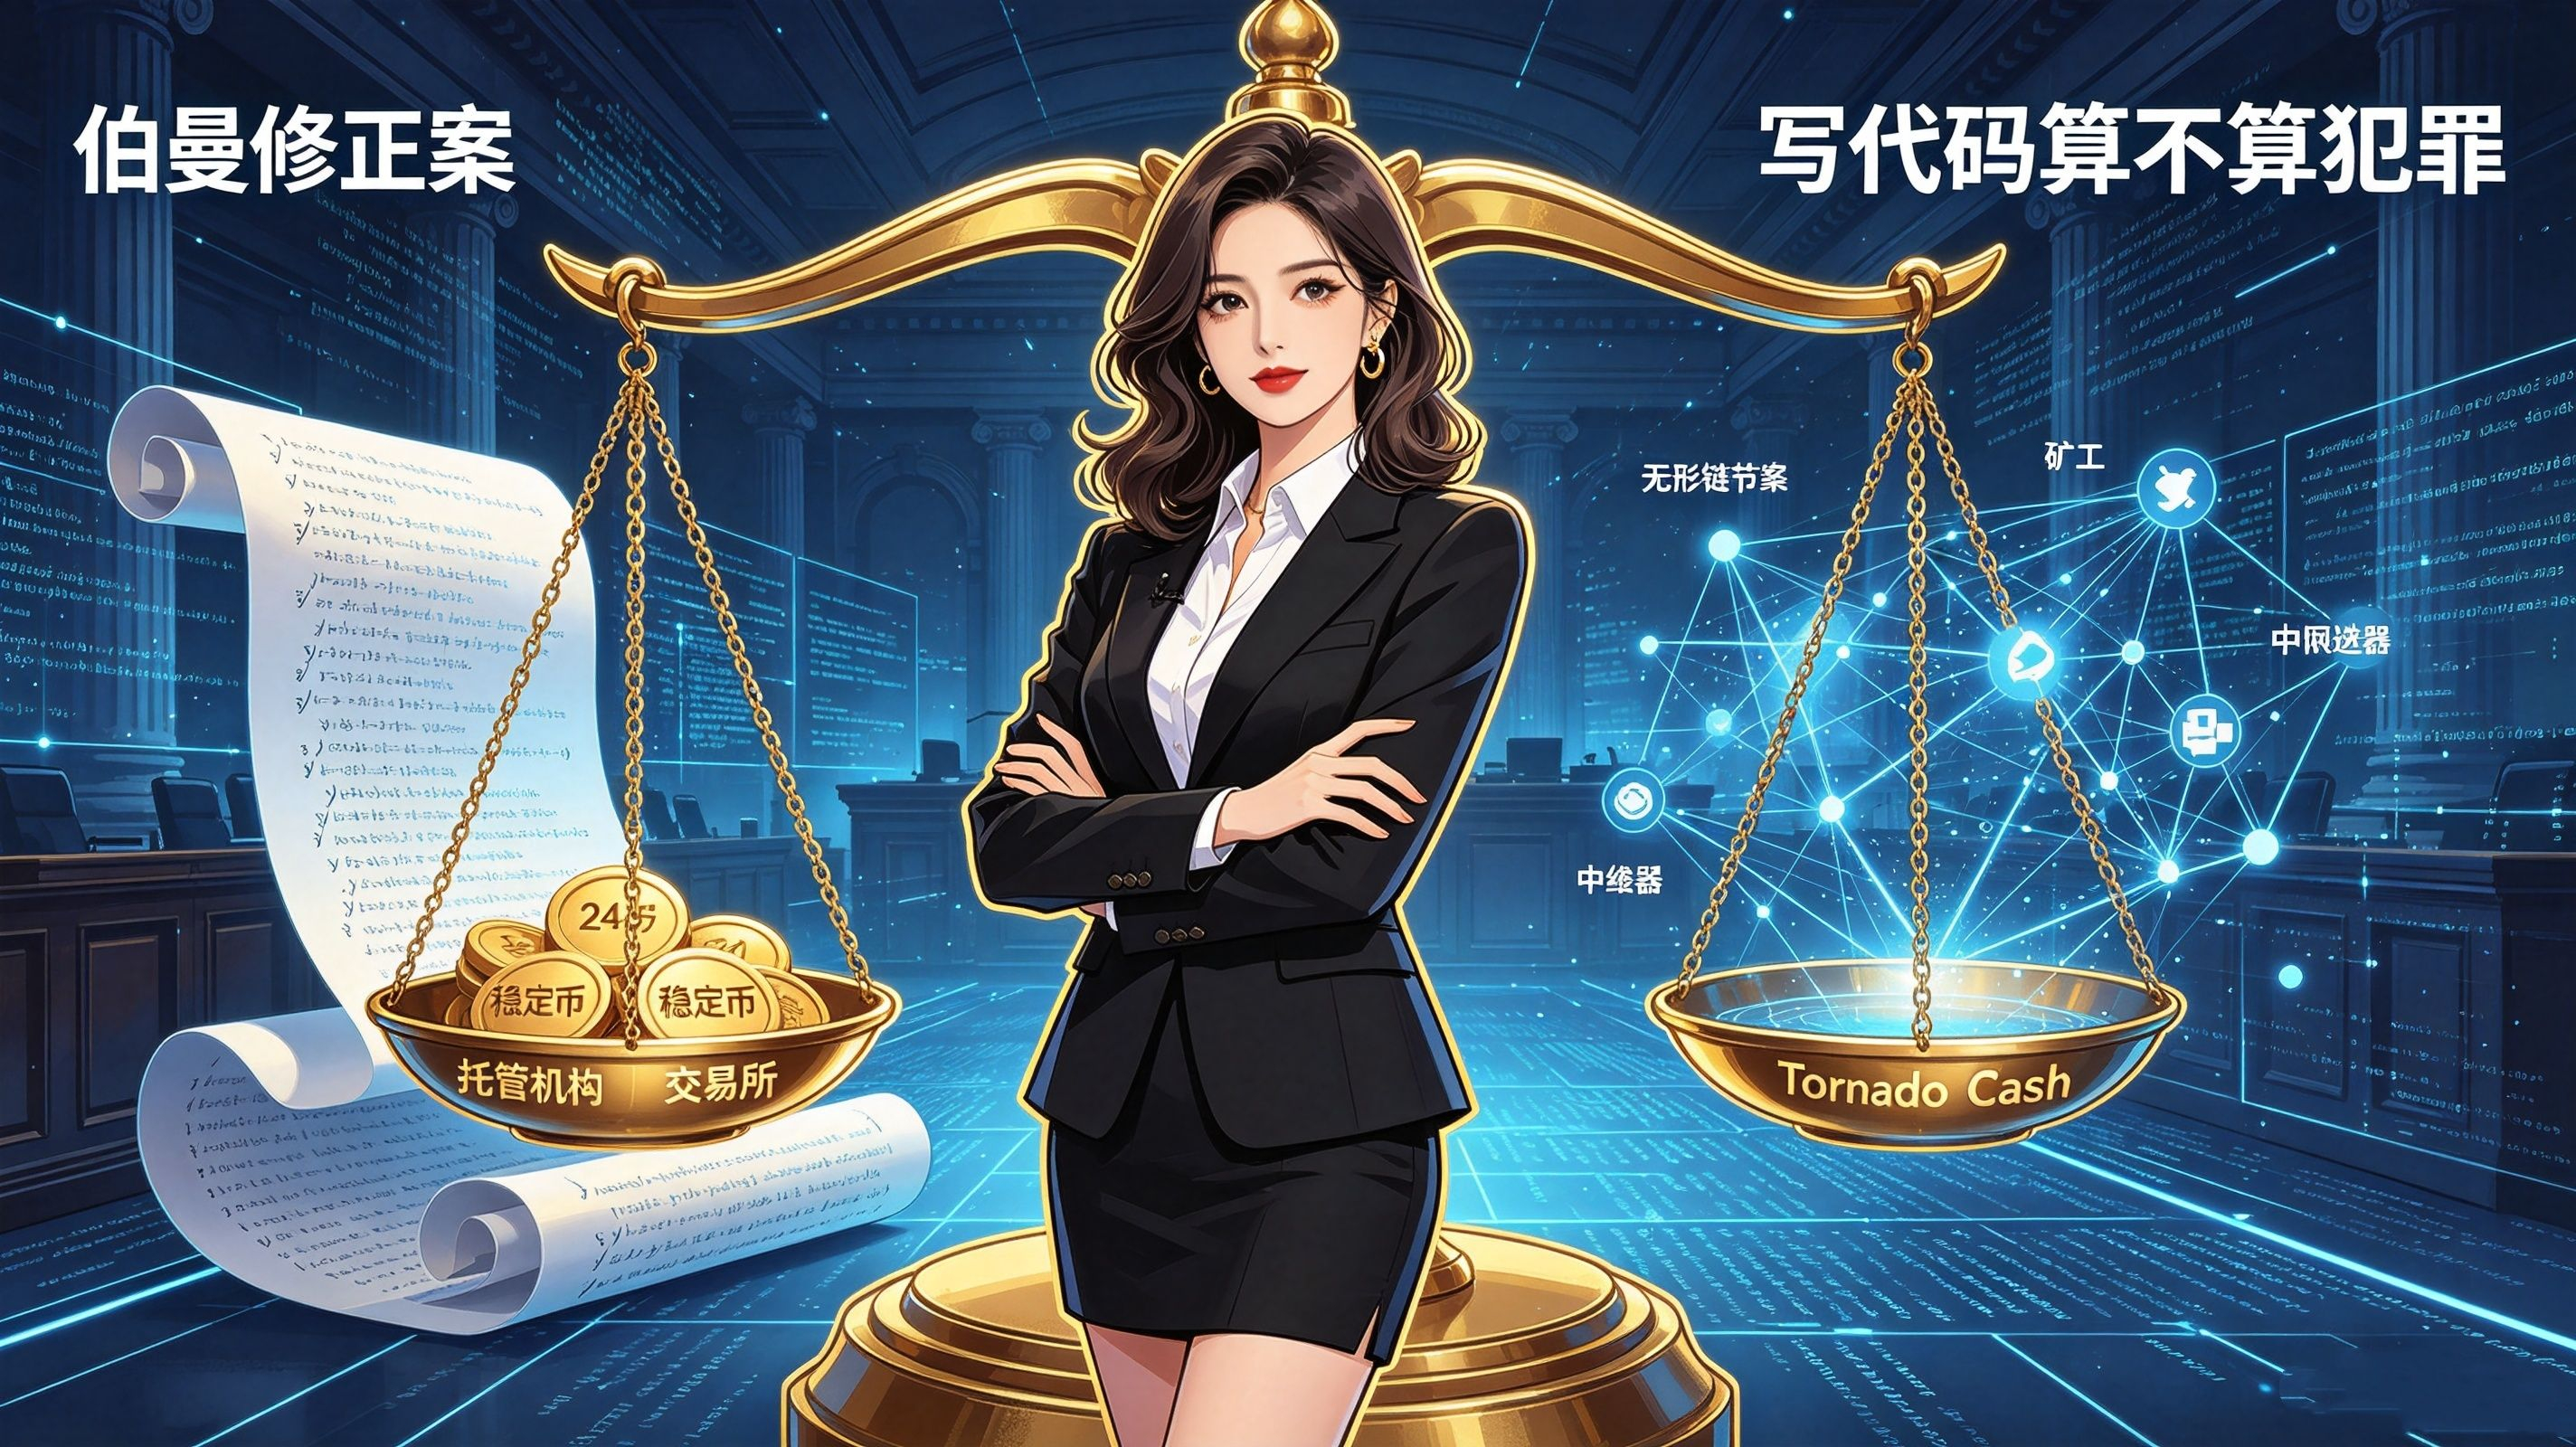
The most important legal concept for the industry to remember in this discussion is the Berman Amendment. This provision, added to U.S. sanctions law in the late 1980s, has a very straightforward purpose: to prevent the government from using sanctions power to restrict information and expression. In other words, sanctions law cannot be used to silence people.
Van Valkenburgh’s formulation is more precise. He says he is not arguing that “all blockchain transactions are protected speech,” but making a narrower and more powerful claim: the act of creating and sharing software is itself protected conduct.
The litmus test for this whole argument is the retrial of Tornado Cash developer Roman Storm. A developer wrote the code for a mixer, but did not directly participate in any money laundering. Should he be held responsible for third parties using the tool? Can the Berman Amendment hold up in a case like this?
If the answer is no, then everyone who writes code will bear the same shackle: if your tool is later used by someone else to do something bad, the responsibility falls on you. That means decentralized networks will no longer have any developers willing to go near them. If the answer is yes, then the Treasury’s deliberately unclear wording this time will have to be forced into clarity in court.
So, where exactly does the real bite of this statement lie?
It’s waiting for the industry to scare itself.
The Treasury does not need to move against nodes, relayers, or miners right now. It only needs to preserve room to act, and that is enough to make developers hesitate, drive capital away, prompt project teams to add KYC on their own, and push the boundaries of decentralization back inch by inch. No one wants to be the case that gets “tested.”
That is why “ambiguity” is more frightening than an “explicit ban.” An explicit ban can be debated, litigated, and overturned; ambiguity is like a leaky roof — you don’t know which tile will collapse first, so everyone in the house is just waiting.
Can decentralization be eliminated by regulation?
Van Valkenburgh’s answer is blunt: no. The enduring method should also be the American way — accept the existence of these new technologies, acknowledge that they cannot be locked down by regulation, and then build businesses on top of these networks as legally as possible. What should truly be constrained are those manned checkpoints: custodians, exchanges, front ends, and stablecoin issuers. Not the things that nobody can shut down.
What this news should really be remembered for is not that the sanctions list now includes the words “digital assets,” but that a public debate about what “on-chain infrastructure” actually counts as has officially begun. How the court rules, how the regulatory documents are written, and whether developers will be hauled into the dock — the answers to these questions will determine whether this industry can continue to exist under the name of “decentralization” over the next five or ten years.
At the end of the day, the Treasury can write “digital assets” into the sanctions scope, but it cannot write a boundary that makes people feel secure. Once that boundary is left to the courts and public opinion to fight over, no one side gets to decide it alone. For the industry, the real trouble is not the list itself, but the deliberate blank space left in that statement — it seems like it says nothing, but in fact it says everything.
Risk warning: This article is only a compilation of information and an analysis of compliance policy, and does not constitute investment advice. The U.S. Treasury sanctions on Iran and Coin Center’s views mentioned in the text are all based on media reports and policy interpretation. The relevant enforcement standards, whether decentralized infrastructure is included as a target, the progress of the Tornado Cash developer case, and similar issues all remain uncertain and will evolve with legislative and judicial developments. Please make your own independent judgment based on official information and assume all related risks yourself.