



Author: Predictefy
Compiled by: Deep Tide TechFlow
Deep Tide Introduction: In January 2026, the prediction market handled over $23 billion in nominal trading volume. Hyperliquid alone processed over $225 billion in the same month. Outcome trading could bring tens of billions of dollars in new trading volume to the prediction market.
Predictefy's analysis points out that the key to HIP-4 lies in integrating outcome contracts into the same margin framework as perpetual futures, allowing event trading to enter the same environment as other crypto derivatives.
This could bring tens of billions of dollars in new trading volume and open contracts to the prediction market in a short period of time. A conservative estimate suggests a monthly trading volume of $28 billion, a moderate estimate of $33 billion, and strong integration could reach over $40 billion.
The full text is as follows:
Prediction markets processed over $23 billion in nominal trading volume in January 2026. Hyperliquid alone processed over $225 billion in the same month. Outcome trades could bring billions of dollars in additional trading volume to prediction markets.
Prediction markets are growing rapidly, but they primarily operate independently. You can trade event outcomes, but these positions are not within the same system traders use to manage broader market risks.
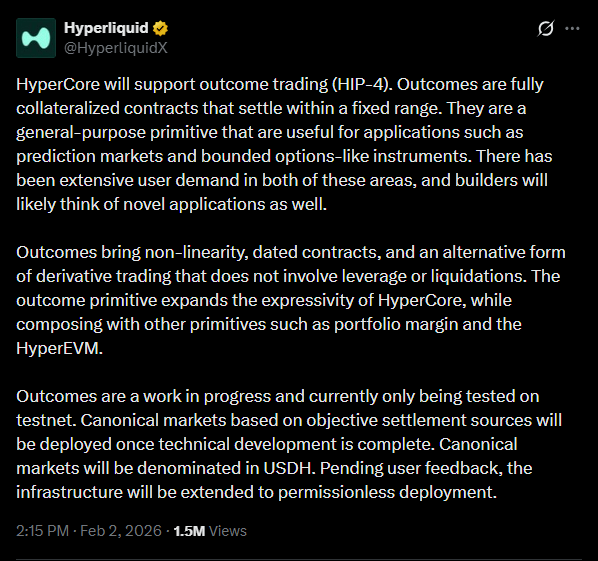
HIP-4 changed that. On Hyperliquid, outcome contracts share the same margin framework as perpetual futures, bringing event trading into the same environment as other crypto derivatives.
This could bring billions of dollars in additional trading volume and open interest to prediction markets in a short period. Here’s how it works.
Prediction markets have achieved considerable scale
Over the past year, prediction markets have surpassed niche activities.
Weekly trading volumes on major platforms often exceed $6 billion
The past month recorded approximately $23.8 billion in nominal trading volume
Market share remains concentrated, with platforms like Polymarket, Opinion, and Kalshi accounting for most of the activity
Despite this growth, prediction markets still primarily operate as independent venues. Event exposures, directional crypto exposures, and volatility exposures typically require separate platforms, collateral pools, and risk systems. This fragmentation limits capital efficiency and constrains the types of strategies traders can implement.
Outcome contracts introduce risk into core infrastructure
Outcome contracts introduced through HIP-4 have several defining characteristics:
Fully collateralized positions
Settlements occur within a fixed and bounded payment range
No clearing mechanism
Contracts based on events or time
Positions integrated into the same margin framework as perpetual futures
Binary contracts themselves are not new. The structural change is their integration into a unified derivatives engine. Event exposures can now share collateral with perpetual positions, allowing for risk management at the portfolio level rather than at the individual market level.
Enhanced capital efficiency
Previously, implementing event-driven strategies typically required traders to:
Deposit collateral on prediction market platforms
Deposit separate collateral for hedging on perpetual futures venues
Independently manage risk and margin across venues
This setup increases capital demand and operational complexity.
Using outcome contracts in a shared trading environment, event exposures and directional hedges can be managed together. A portfolio margin system can recognize offsetting risks, reducing overall margin usage. This aligns event trading with established derivatives risk management practices.
The current market size and trading volume growth potential
Prediction markets processed approximately $20-25 billion in monthly trading volume in January 2026 under today's isolated structure, with event trading situated outside the broader derivatives stack.
In contrast, Hyperliquid recorded over $225 billion in perpetual futures trading volume in the same month, with daily perpetual trading volume reaching the billions range. Derivatives liquidity pools are already much deeper than independent prediction market activity.
If HIP-4 enhances capital efficiency and makes event positions easier to hedge within the same system, trading activity could expand through structural turnover—more strategies operating on the same capital.
Conservative scenario suggests:
Partial adoption → $28 billion monthly prediction market trading volume
Moderate adoption → $33 billion
Strong integration → Over $40 billion
These estimates reflect strategic integration rather than speculative cycles, and do not account for the continuous monthly growth already observed in prediction market trading volume, which could push totals even higher.
Prediction markets begin to resemble options infrastructure
Outcome contracts introduction:
Non-linear payments
Event-driven settlements
Bounded risk characteristics
These features overlap with options-style exposures. This creates a foundation for the following:
Event volatility strategies
Structured products containing outcome positions
Systematic portfolios combining event and market risk
Protocols to build new products on top of outcome primitives
Prediction markets are shifting from being primarily narrative-driven to becoming components available within broader financial strategies.
Competitive landscape
Independent prediction market platforms retain advantages in brand awareness, liquidity depth, and simplicity. However, platforms that integrate event risk with perpetual contracts and other derivatives offer:
Shared collateral pool
Instant hedging within the same environment
Netting risk settlement at the portfolio level
Even a partial migration of higher-order trading flows could impact the concentration of capital-efficient and hedge-intensive activities.
Signals of adoption
Structural adoption will reflect in trading behavior, not just headline trading volumes:
Resulting positions paired with perpetual hedges
Uncleared contracts growth from macro and policy events
The emergence of vaults or structured strategies based on outcome exposure
Narrowing price spreads relative to independent prediction market venues
These signals indicate that outcomes are being used as financial instruments rather than isolated event trades.
Conclusion
Prediction markets have achieved scale but have remained structurally separate from the broader derivatives stack until now.
HIP-4 introduces a framework where event risk can coexist with perpetual futures within shared trading infrastructure. As this model develops, prediction markets may increasingly operate as components of diversified risk portfolios rather than independent betting venues.