#termmax @TermMax
#TermMax
$TMX
I long believed that fixed-rate and floating-rate lending were two competing models.
But precisely thanks to TermMax + Morpho, this picture has become more interesting.
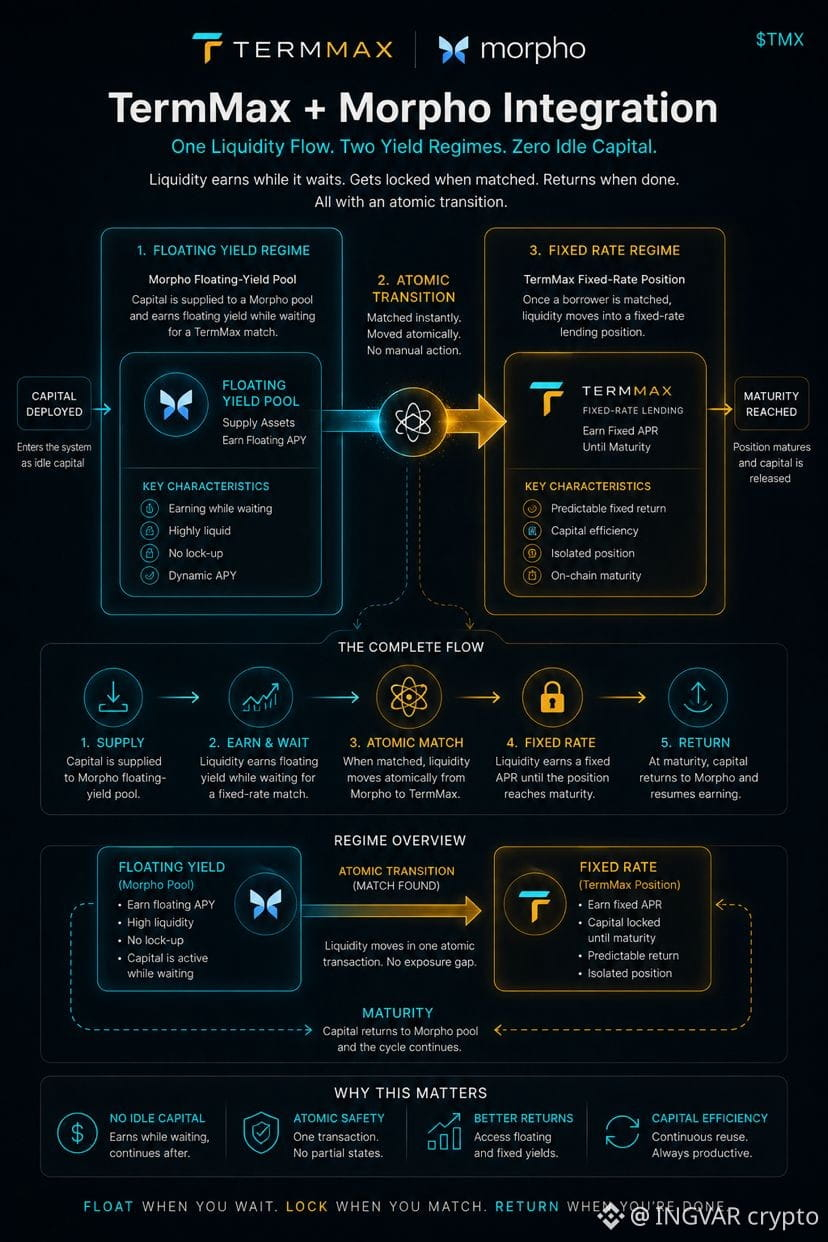
TermMax V2 uses Composable Base Yield.
The idea is simple:
while the capital hasn’t been matched in the fixed-rate market yet, it doesn’t have to sit idle.
In the Morpho integration model, unmatched capital can generate floating yield.
When the borrower takes liquidity, the capital atomically transfers from Morpho into a fixed-rate TermMax position.
And after maturity or repayment, it goes back.
So one position can combine two modes:
floating yield while the capital is waiting
fixed-rate yield once liquidity is matched.
And here I see a much more interesting idea than just “TermMax integrated with Morpho.”
It’s an attempt to connect the flexibility of floating markets with the predictability of fixed-rate markets.
Not either/or.
It’s like:
use floating when flexibility matters, lock fixed when certainty matters.
For developing DeFi fixed income, in my opinion, this is a much stronger concept.
$TMX