In the past few days I’ve seen a bunch of projects preparing to issue tokens, and it’s starting to annoy me a bit. I clicked in and looked around; most of them are still just telling a story. The one that seems to hold up in carving out a little space in the early window is apparently TermMax. As for the other options with time-including mechanisms, they haven’t run fully either—I can’t be bothered to nitpick further, so I just focus on TermMax.
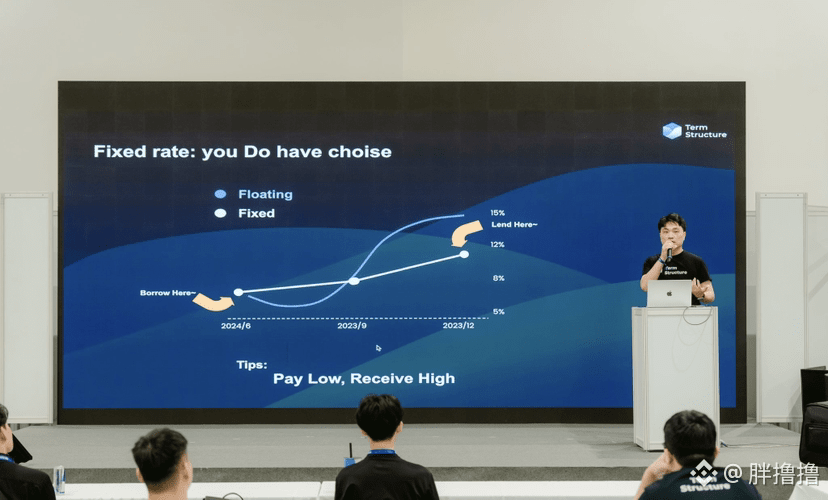
#TermMax Before this, I always thought TermMax was just a fixed-income product that locks interest rates. But after I separated FT and XT, I realized it’s not that simple. FT pins down the principal and the guaranteed returns, while XT throws the part that can be bet on into the secondary market and circulates it. Once TermMax is broken down like this, lending isn’t just about parking money there and waiting to collect interest.
@TermMax $ETH
Only after limit orders are embedded into TermMax did it start to feel a bit interesting. The party providing the funds writes its own minimum annualized rate; the borrower locks in the highest cost early; and in the middle they match on their own. Before, everything was pushed along by a unified rate. Now, at least you can use orders to have a say. TermMax doesn’t just smooth out volatility—it feels more like letting capital negotiate the price itself.
But I still don’t fully trust its liquidity. The order book isn’t deep enough; when the listed orders fluctuate a lot, it can easily turn into a prop. The interest rate locks in near-term uncertainty, but it can’t guarantee whether, in a couple of months, this cost is still worth it. Next I’ll watch whether orders on both sides of TermMax can actually connect—if large orders come in, will the slippage suddenly widen? And is XT truly reflecting real sentiment, or just drifting with the mood. Only if these hold up will I say that TermMax has moved capital efficiency forward a bit. It’s still early, so no rush to draw conclusions.