

Source: Xinhua Finance
Xinhua Finance, Beijing, August 20 (Hu Yuting): On August 20, the People’s Bank of China conducted a 7-day reverse repo with a maturity of zero. Given that 327.4 billion yuan of overnight reverse repos matured that day, the open market achieved a net withdrawal of 327.4 billion yuan.
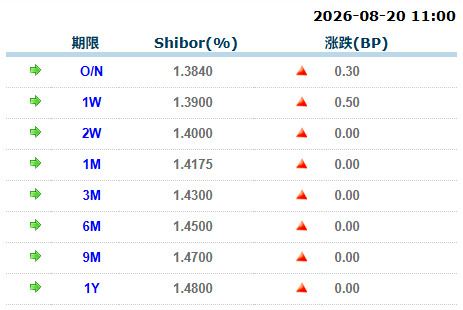
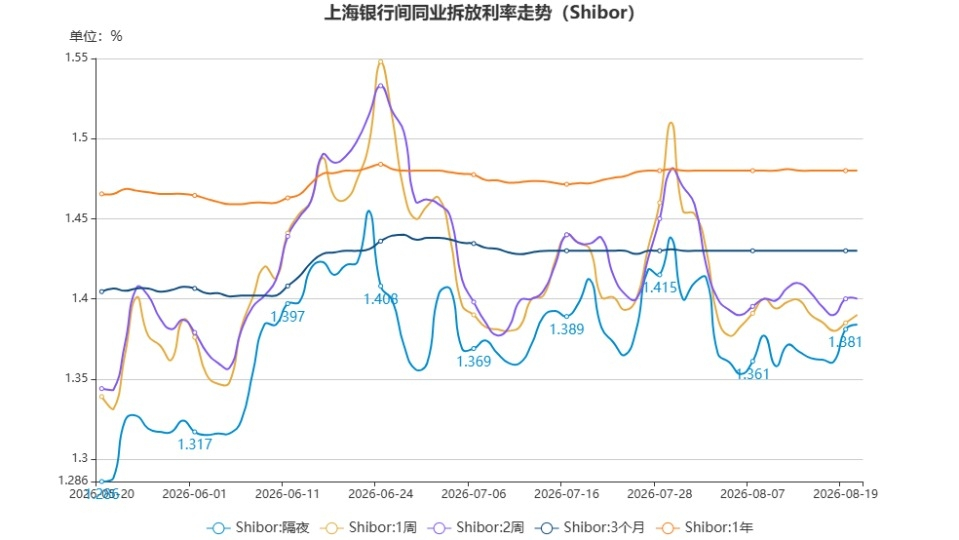
The Shanghai Interbank Offered Rate (Shibor) remained steady, with slight gains in short-tenor rates. Specifically, overnight Shibor rose by 0.3 BP to 1.3840%; 7-day Shibor rose by 0.5 BP to 1.3900%; 14-day Shibor was unchanged at 1.4000%.
Shanghai Interbank Offered Rate (Shibor) (August 20)
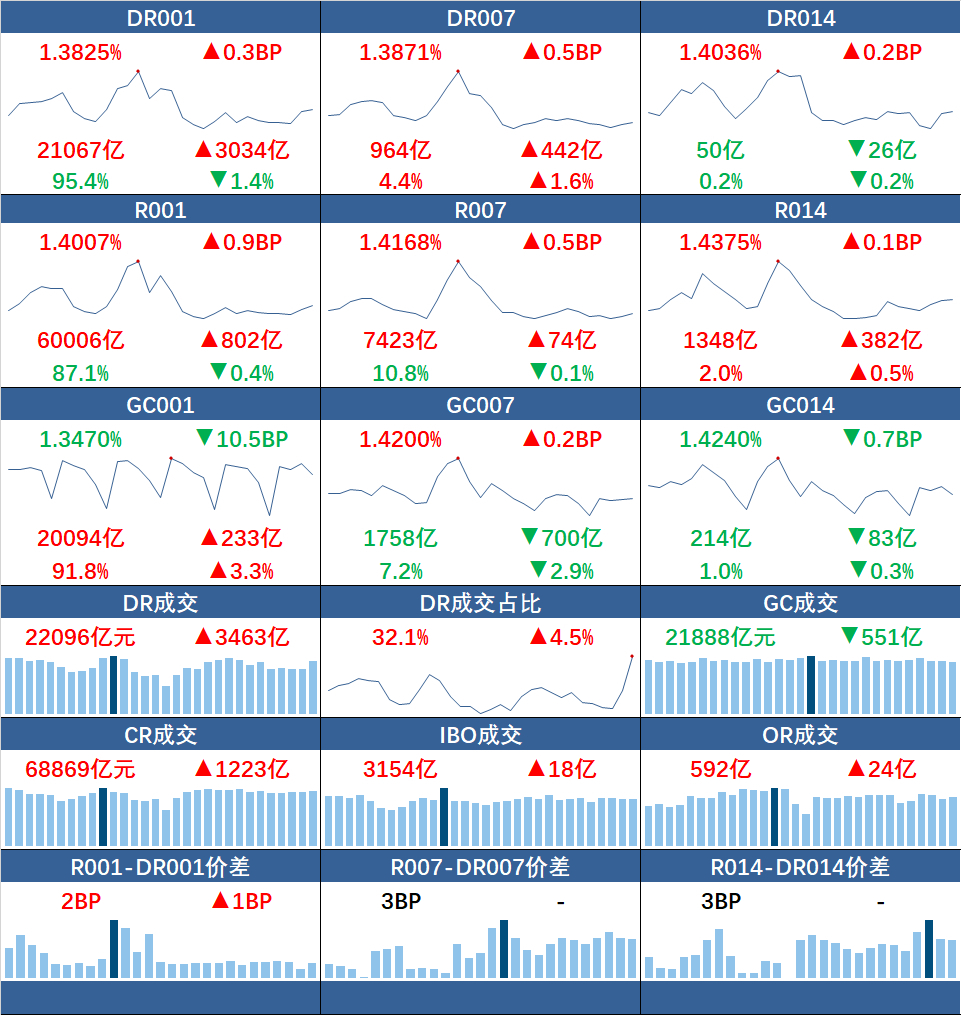
In the interbank collateralized repo market, both volume and prices of short-term products rose. The weighted average rate of R001 broke through 1.4%, with trading volume exceeding 6 trillion yuan, while the share of DR trading increased by 4.5 percentage points to 32.1%. Specifically, the weighted average rates of DR001 and R001 rose by 0.3 BP and 0.9 BP respectively, to 1.3825% and 1.4007%; their trading amounts increased by 303.4 billion yuan and 80.2 billion yuan respectively. The weighted average rates of DR007 and R007 rose by 0.5 BP each, to 1.3871% and 1.4168%; their trading amounts increased by 44.2 billion yuan and 7.4 billion yuan respectively. The weighted average rates of DR014 and R014 rose by 0.2 BP and 0.1 BP respectively, to 1.4036% and 1.4375%; their trading amounts decreased by 2.6 billion yuan and increased by 38.2 billion yuan respectively.
Money market interest rates (August 20)
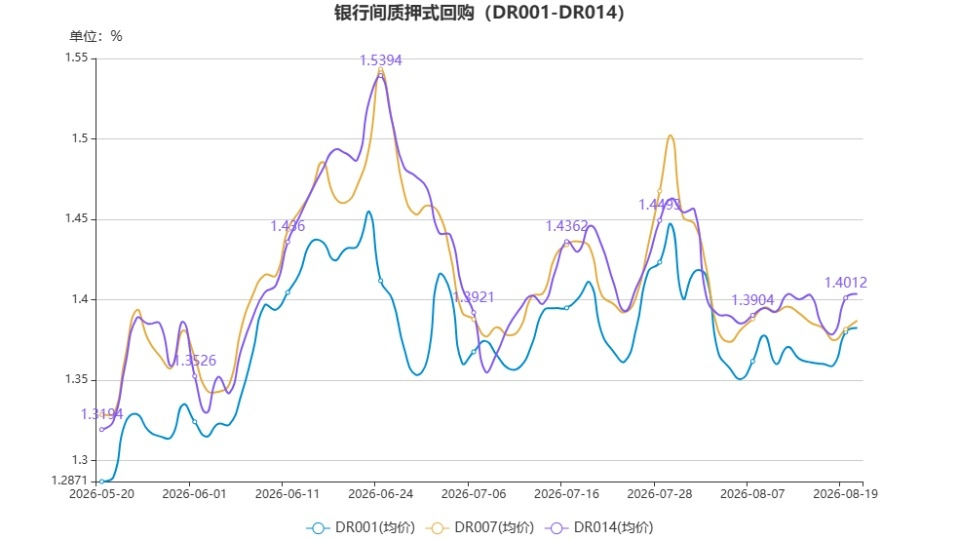
According to a money market broker trader at Shanghai International Money Brokerage Co., Ltd., on the 20th, liquidity in the early session was balanced; after the midday session it turned to slightly tighter than balanced, and there was no obvious easing by the close. In the early session, the成交 (trade) rates on funding moved up slightly from the previous day. Overnight repo-eligible deposit certificates traded in the range of 1.39%–1.40%; repo-eligible credit ofr supply in the range of 1.42%–1.43%. For 7-day non-bank repo-eligible deposit certificates, trades were around 1.41%; repo-eligible credit ofr in the range of 1.42%–1.43%. For cross-month maturities, 14-day repo-eligible trades were in the range of 1.42%–1.43%; non-bank repo-eligible credit ofr was in the range of 1.44%–1.45%. Subsequently, overnight rates continued to rise. Near midday, overnight repo-eligible deposit certificates’ trades rose to the range of 1.41%–1.42%. A small amount of cross-month repo-eligible trades occurred around 1.42%, and the market generally stayed balanced until the morning close. In the afternoon, liquidity maintained a balanced tone at the open: overnight repo-eligible trades were in the range of 1.40%–1.41%, while repo-eligible deposit certificates trades were around 1.42%. Around 2:30 p.m., demand for overnight repo-eligible deposit certificates concentrated at about 1.42%, while supply was in the range of 1.43%–1.44%. Near the close, bank demand increased, and the lowest overnight repo-eligible deposit certificate trade rate fell to 1.40%. Liquidity remained balanced but tighter than before until the close.
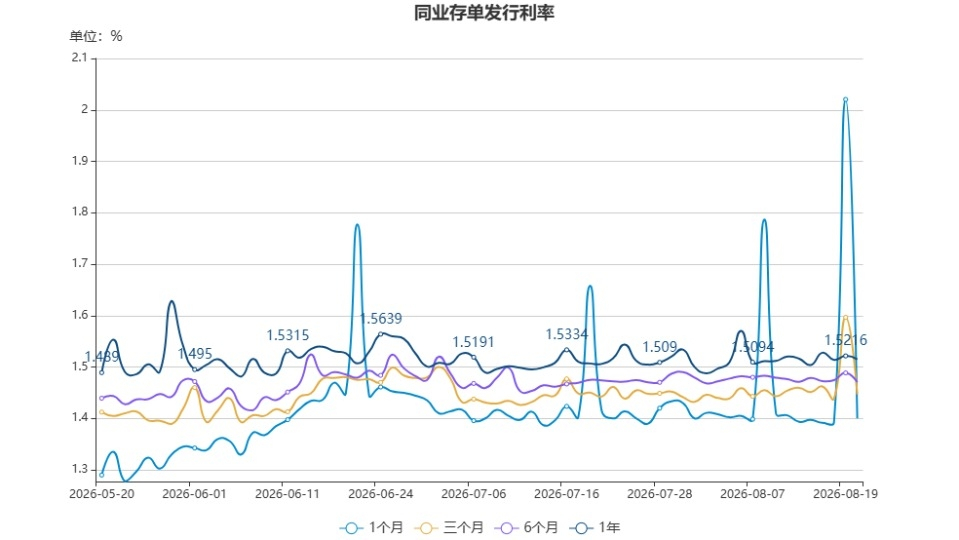
On the certificates of deposit (CDs) front, short-end secondary-market yields were basically unchanged from the previous day, while long-end yields saw narrow-range fluctuations. Specifically: the 1M national-share bank CDs ended the day at around 1.38%, flat from yesterday; the 3M national-share bank CDs ended around 1.4325%, up about 0.25 bp from yesterday; the 6M national-share bank CDs ended around 1.4575%, flat from yesterday; the 9M national-share bank CDs ended around 1.4725%, flat from yesterday; and the 1Y national-share bank CDs ended around 1.4775%, flat from yesterday. The spread between 1Y and 9M was 0.5 bp, unchanged from yesterday; the spread between 9M and 6M was 1.5 bp, unchanged from yesterday; the spread between 6M and 3M was 2.5 bp, narrowing by 0.25 bp from yesterday; the spread between 3M and 1M was 5.25 bp, widening by 0.25 bp from yesterday. The spread on the 1Y–1M curve was 9.75 bp, unchanged from yesterday. The spread on the 1Y–3M curve was 4.5 bp, narrowing by 0.25 bp from yesterday.
[Today's Focus]
? The People’s Bank of China will keep the one-year and five-year Loan Prime Rates (LPR) unchanged at 3% and 3.5%, respectively.
? According to research data obtained from within the industry, as of the end of 2025, the outstanding balance of trust plans allocated by insurance funds has declined to around RMB 800 billion, representing a year-on-year decrease of more than 20%. The outstanding balance of trust plans allocated by insurance companies first recorded negative growth in 2021, and has contracted for 5 consecutive years by 2025. The latest size has also fallen below one trillion yuan, marking the first such occurrence since 2017.
? Research by reporters has found that financial asset management companies have reached a strong consensus on gold’s role as a “stabilizer” and its value in asset allocation. They believe that within a multi-asset, multi-strategy framework, gold is an indispensable component, and going forward it will be allocated with a more flexible schedule, “buying on dips.”
Edit: Second Year Mountain