I read the @TermMax whitepaper three times, underlined and close-read it, staring at 2.2—the obscure details about “Physical Delivery and GT (Gearing Token) Collateral Liquidation.” The more I dig, the more interesting it seems.
Everyone’s tired of the “zero-coupon bond (FT) + floating yield (XT)” assembly story in the fixed-rate track. The public’s blind spot is that they only focus on the appearance of “fixed interest,” while ignoring the liquidity black hole caused by the liquidation mechanism under extreme market conditions. Traditional protocols rely on liquidators to auction off positions; in extreme conditions, they can end up getting immediately wiped (going through the book).
Translate TermMax’s mechanism into a real-life scenario:
It’s like you use your house as collateral to borrow money from a pawnshop. When the house price crashes and liquidation is triggered, the pawnshop doesn’t hire an intermediary to list the house for a low-price sale. Instead, it directly bundles the house’s property title certificate (GT NFT) and throws it to the creditor (Lender). On the surface, this eliminates bad-debt risk—but in reality, it shifts all the liquidity-discount risk to the creditor.
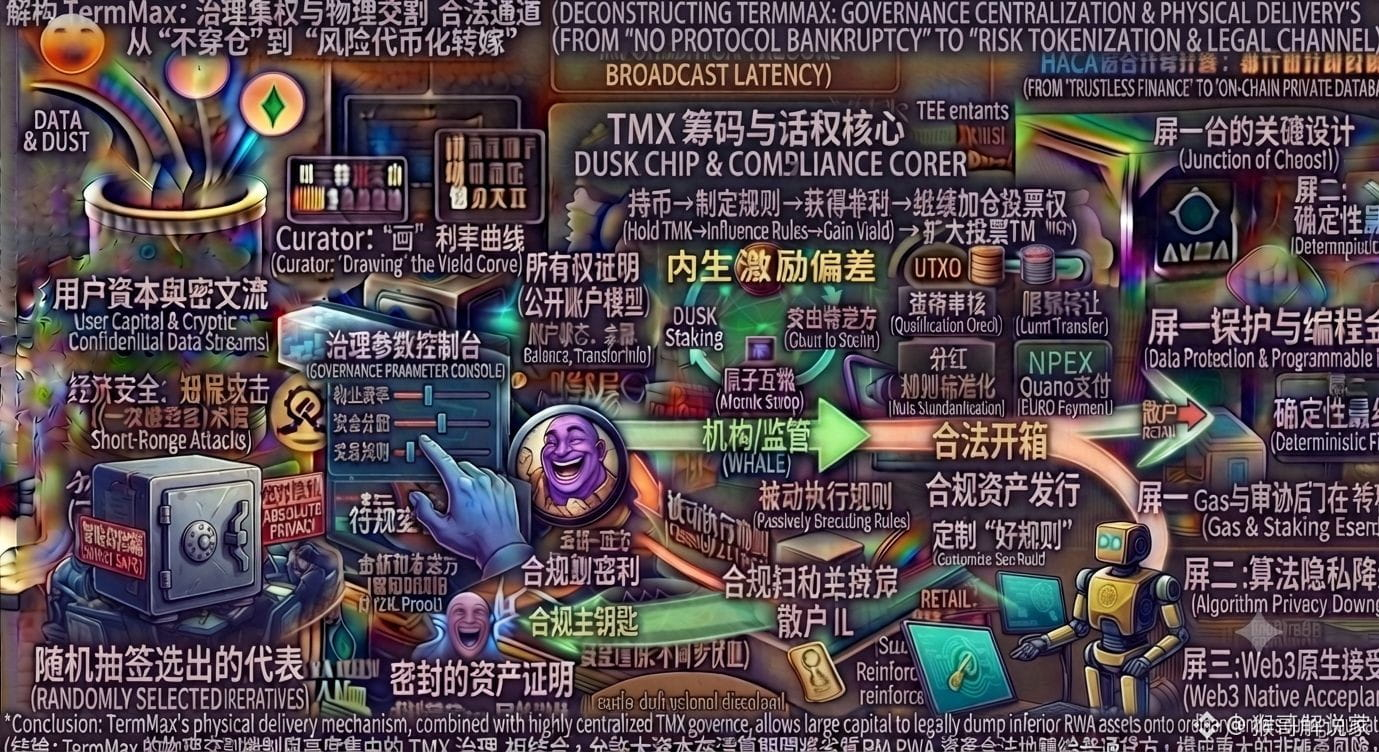
Here, the native token TMX plays a crucial role: it’s both the voting credential for proposal and parameter governance, and the underlying ecosystem layer used to pay Curator curation fees and for protocol orchestration. But if you go deeper into the underlying endogenous incentive misalignments, you’ll find that big holders can accumulate large amounts of TMX to gain governance power. With that, they can vote to modify certain high-risk RWA/small-coin pool Curator curation parameters and the liquidation/settlement thresholds. They use rules to move risky assets on-chain, borrow mainstream coins. Even if liquidation is triggered, they can dump the bad assets onto ordinary borrowers through “physical delivery,” and then use the profits to further increase their TMX voting power in a feedback loop.
TermMax packages leverage (GT NFTs) with physical delivery in a single transaction. That truly boosts capital efficiency and avoids protocol-level getting wiped. But the real contrarian risk is this: “Not getting wiped” doesn’t mean “investors don’t lose money.” It only legally tokenizes the liquidation risk at the protocol level and allocates it to ordinary holders.
When governance power is highly concentrated among vested interest groups, will physical delivery become a legitimate channel for large players to offload low-quality assets? What does everyone think about this mechanism? Feel free to discuss it in the comments.
#termmax @TermMax