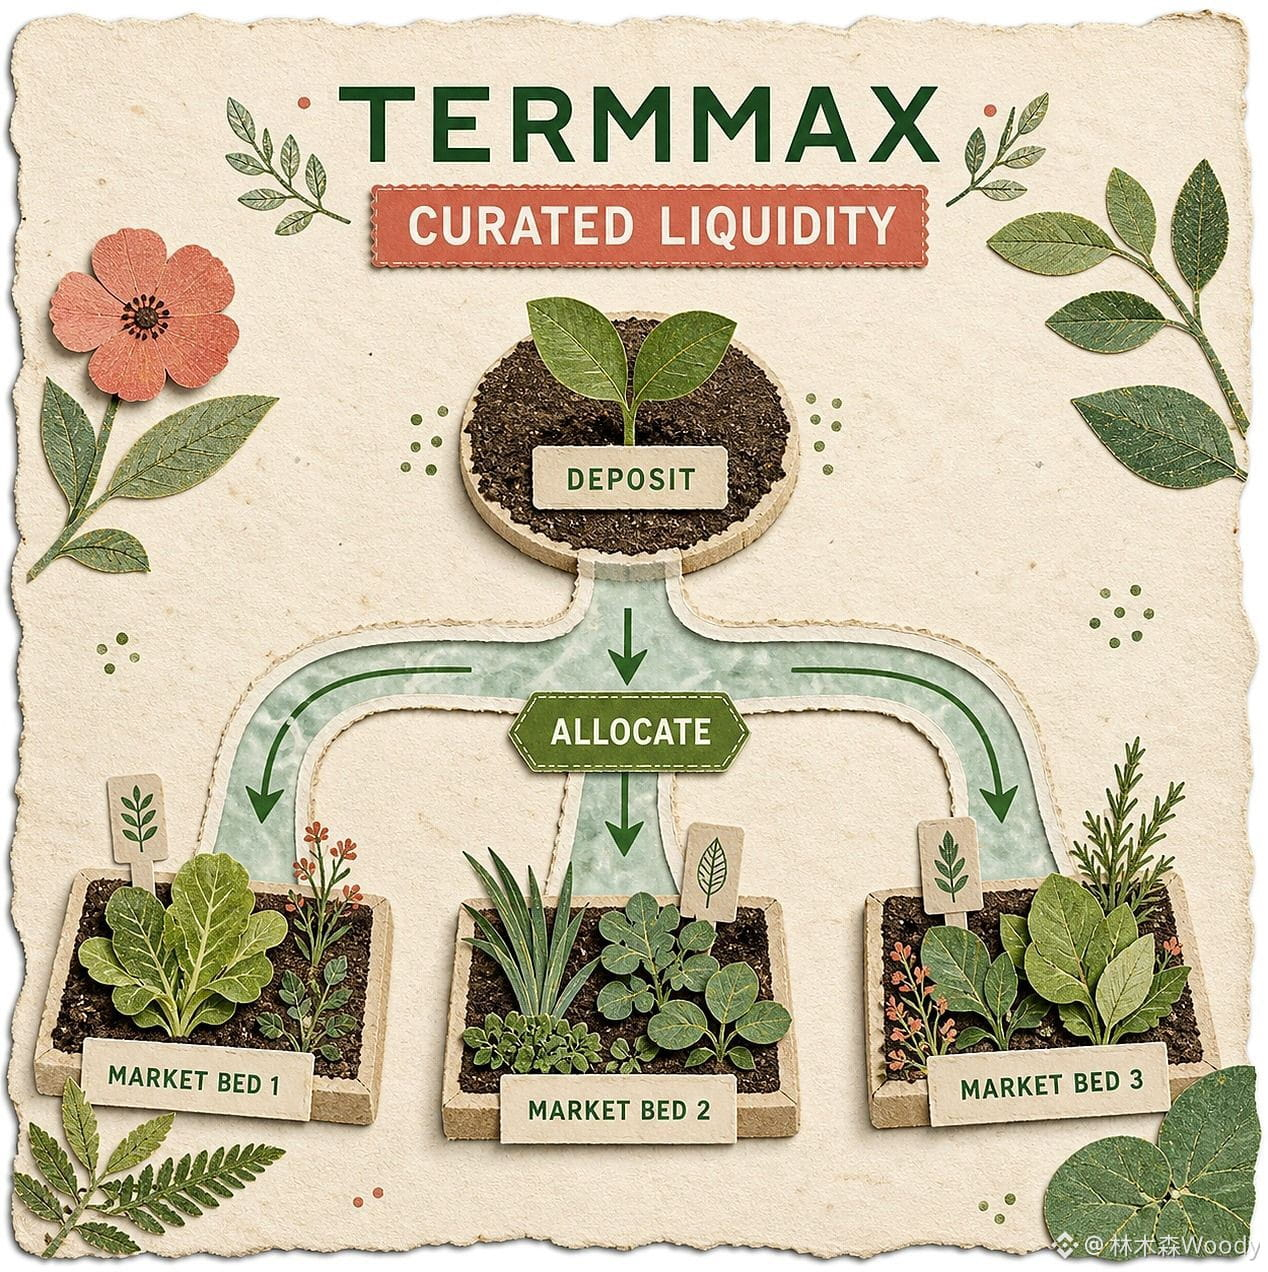
I traced the capital flows from the @TermMax document today by drawing the FT, XT, and GT—and when I got to the third arrow, I couldn’t help but laugh: a fixed-term loan, how did it get split into three different tokens? The design really is clever, but which one are ordinary users supposed to focus on?
First, I’ll straighten out the logic. FT is like a zero-coupon bond: at maturity, it can be redeemed for the debt asset at face value. XT covers the portion discounted from the FT; per the protocol definition, it’s always 1 FT plus 1 XT corresponding to 1 share of the debt asset. GT is ERC-721; it holds the collateral and the debt position. The borrower locks the collateral, mints FT, then splits the FT into the principal part and the interest part to exchange for XT, and finally bundles everything back into the asset they want to borrow. On paper, the loop is quite elegant—I admit it’s more verifiable than the idea of simply “writing interest rates on a page.”
But the more I read, the more I get uneasy. The FT price changes with the remaining term and the market curve. The value of XT at maturity goes to zero, and GT also carries liquidation risk. The three tokens each encode duration, interest, and the collateral-backed debt. TermMax makes the decomposition of a single loan very transparent, but it also fractures the states users need to understand. One-click trading on the page doesn’t mean the user’s brain can also understand it in one click, right?
More importantly, borrowers can repay directly with the debt asset, or they can buy and repay with discounted FT. That sounds flexible, but it means the cost of exiting early depends not only on the initially locked-in rate, but also on whether the FT market has depth and what price the curve implies at that time. Fixed interest provides contractual certainty, yet the exit price still has to be negotiated with the market.
I also looked back at the maturity end. Under normal circumstances, FT is redeemed at face value. But if the borrower is in default, and liquidation isn’t handled cleanly within the window, the redemption pool could end up mixed with collateral. In other words: yes, FT is like a bond—but the credit protection isn’t a promise by some institution to honor redemptions. Instead, it’s “handed off” through the collateralization ratio, oracles, liquidators, and market liquidity working together. Miss a relay, and the conclusion can easily go off-track.
So after researching #TermMax , what I most want to see isn’t another “fixed APY” poster. I want the system to explain, in plain language, how FT, XT, and GT change for each position—and what the worst-case exit path looks like. Complex mechanisms can be hidden behind a single click, but if the risk is hidden behind that same simplification, is this layer truly serving users—or only serving conversions?
$PRL $CLO