#bstockscis @BinanceCIS
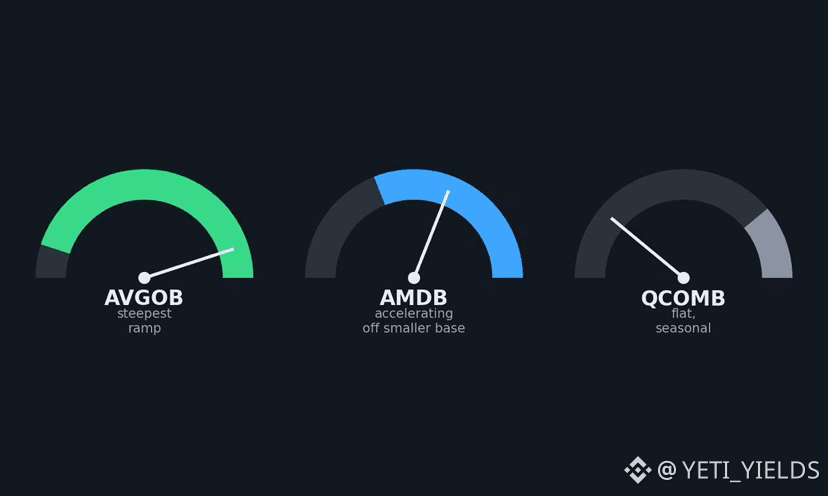
AVGOB, AMDB, QCOMB — three "chip stocks," three completely different growth clocks. 🔬 Ran the comparison properly instead of lumping all three together, because that's what most coverage does and it hides more than it reveals.
Broadcom's most recent quarter: $22.2B in revenue, up 48% year-over-year, guiding next quarter to roughly $29.4B — a 32% quarter-over-quarter jump on the guide alone, driven almost entirely by AI networking and custom silicon demand from six concentrated customers. 🚀 AMDB just picked up a fresh $1,250 price target from Baird, reflecting conviction that AMD is closing the inference price-performance gap against Nvidia — a share-of-a-growing-market thesis, not a replacement thesis. ⚔️ QCOMB, meanwhile, runs on an entirely different clock: mobile chipset volumes and licensing revenue tied to global handset shipment cycles, seasonal and multi-quarter rather than AI-capex acceleration. 📱
Line the three growth trajectories up and AVGOB's is steepest by a wide margin right now, AMDB's is accelerating off a smaller base with real analyst conviction behind it, and QCOMB's is comparatively flat — not because Qualcomm is a worse business, but because it's answering a different demand question entirely. 🧮
If you could only hold one of the three growth stories, which gets the weight — and does "semiconductor exposure" as a single thesis even make sense anymore given how different these clocks are?
#bStocksCIS @BinanceCIS $AVGOB $AMDB $QCOMB