


By | HONGCAN NExT (Red Can Network) Guo Jia'xi
Edited by | Jing Xue
In 2013, Tea颜悦色 opened its first store in Changsha. With the boom of the new tea beverage industry, it gradually became a representative consumption symbol of Changsha, and many out-of-town consumers even made special trips to Changsha just to check in.
In those years, the market was all waiting for it to move out of Hunan.
But for Tea颜悦色, in Changsha it was a full "trouble" of seven or eight years—until 2020—before it finally stepped out of Hunan and opened its first store in Wuhan. From Wuhan to Chongqing, and then to Nanjing and Wuxi, the pace at which Tea颜悦色 expanded remained restrained. Even in China’s new tea beverage track, it could be considered somewhat slow.
However, this slow company suddenly began to accelerate this year.
From the opening in Shenzhen in April to the official announcement of Guangzhou in July, the time gap is only 99 days. And these two cities happen to be the most brutal red oceans of competition for tea drinks nationwide.
Among the top five cities by number of tea-drink shops nationwide, Guangzhou ranks first and Shenzhen second. Local brands have been deeply cultivating the market for years, and top brands are all already in place. No matter how you look at it, this is not a market that’s easy to fight.
A first-generation internet celebrity that built nationwide recognition through regional scarcity has proactively entered the core cities with the highest intensity of competition. Tea Yan Yue Se is stepping out of its comfort zone. Once it starts turning toward its opponents, will it still have the odds on its side?
Conservative choices beneath the red ocean
First, take a look at the newly announced Guangzhou flagship store.
Rumor has it this shop will be located at Bai’e Tang Wanxiangcheng, with an expected opening in late September. When discussing the reasons for entering Guangzhou, Tea Yan Yue Se said: “Guangzhou is the national competition hub for tea drinks. We want to throw ourselves into this lively ‘elite matchup’ and see how good our product strength and organizational capability really are.”
A red ocean with the most stores nationwide—where local brands are deeply rooted and all major outside players are already in place—no matter how you look at it, it doesn’t seem like a comfortable expansion zone. But a supply-side red ocean doesn’t mean a demand-side dead sea.
According to data from the Guangzhou Daily, in 2025 the revenue of Guangzhou’s “beverages and cold drinks services” grew year over year by 22.8%. It is the fastest-growing segment among catering consumption, with a growth rate significantly higher than the average of total retail sales of consumer goods in society.
This means that Guangzhou is not only a stock of a zero-sum game cake—it’s also a mature market where supply and demand expand in step.
The basic demand base in the Shenzhen market is also solid. In a sense, Guangzhou and Shenzhen are both the “touchstone” for brands in the tea-drink industry—the highest-value proving grounds.
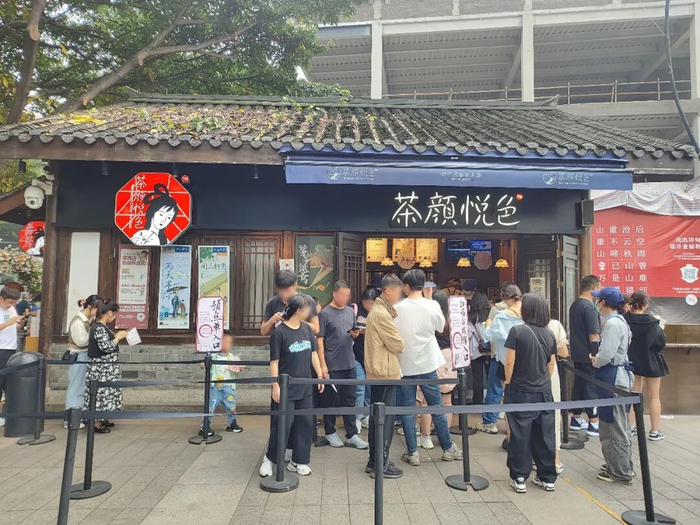
In terms of tea-drink categories, the supply in these two cities is extremely abundant. Segmented tracks such as fresh fruit tea, fresh milk tea, lemon tea, and regionally distinctive tea drinks all have established players. Consumers have plenty of choice space and are far less dependent on any single brand. The decline rate of the “internet celebrity freshness” happens much faster than the information gap effect seen in lower-tier markets.
Relying on scarcity to explode in a single market isn’t an accomplishment. For Tea Yan Yue Se to prove itself, it can only validate whether the brand awareness it built up in Changsha can carry forward and extend brand value in mature high-tier cities in a market where competition is sufficient and information is transparent. Only the conclusions drawn from that can be broadly applicable nationwide.
Also, this year in January, even before Tea Yan Yue Se had officially announced its Shenzhen stores, recruitment platforms already showed a position for a Shenzhen warehouse supervisor. Clearly, this brand that insists on a fully company-owned model has already invested storage and city management resources in Guangdong.
Shenzhen and Guangzhou are both in the Greater Bay Area. The logistics radius is short, and the supply chain system can be directly reused. Variations in quality control and logistics costs are far lower than when expanding into a completely new province.
As for location, Tea Yan Yue Se also has its own logic. Taking its Guangzhou flagship store as an example: the rumor is that the store is located at Bai’e Tang Wanxiangcheng. Bai’e Tang Wanxiangcheng is Guangzhou’s first Wanxiangcheng, positioned as an M1-level ultra-luxury commercial complex, and it is also a city-level flagship project built in Guangzhou by China Resources. The mall plans to open in late September, which closely matches the Guangzhou store opening timeline announced by Tea Yan Yue Se.
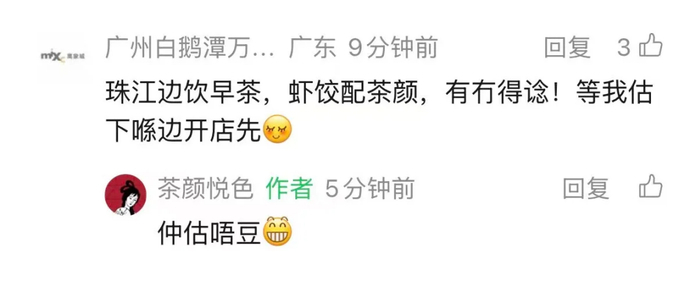
Many netizens complain that the location here is “off to the side.” In fact, they’re measuring the new commercial area against the benchmark of Tianhe’s core business district.
From an operational perspective, the commercial projects in Tianhe’s core business district already have stable customer traffic, and rent fully reflects the value of a mature location. Brands like Heytea, Naixue’s Tea, and Bawang Cha Ji have operated there for years; prime locations and consumer habits have long been formed. If Tea Yan Yue Se enters, it needs to spend higher costs to compete for a portion of customer flow that has already been thoroughly diverted.
And since Bai’e Tang Wanxiangcheng is in its opening recruitment period, the first-store effect and the mall’s opening traffic are concentrated and released. On one hand, Tea Yan Yue Se can reduce customer-acquisition spending in the early phase of entering Guangzhou. On the other hand, it also helps it avoid the most direct point-to-point competition with Tianhe’s mature business district.
A deeper logic is that Tea Yan Yue Se is tightly bound to the China Resources commercial ecosystem, replicating what that system offers.
In Shenzhen, the first two Tea Yan Yue Se stores opened at Shenzhen Bay Wanxiangcheng and Nanshan Wanxiangtiandi, respectively. Later, it also opened a store in Buji Wanxianghui.
All three commercial projects belong to or are operated by China Resources Land. As for Bai’e Tang Wanxiangcheng, it is also within the China Resources commercial ecosystem.
By continuously entering multiple China Resources projects, Tea Yan Yue Se and this commercial system have already formed a foundation for cooperation. There are experiences that can be reused for store construction, opening coordination, and mall operations. Communication and execution costs will also be lower than starting from scratch to find other commercial partners.
Although competition between Guangzhou and Shenzhen is fierce, consumer demand has also been repeatedly verified through ten-thousands of tea-drink stores. For Tea Yan Yue Se, that means it’s a market that is expensive but relatively easy to calculate.
There is no more room to slow down
“I’m rather pessimistic. Either we expand to death, or we don’t expand to death. We think not expanding—this kind of death—feels more dignified.” Lü Liang described Tea Yan Yue Se’s dilemma in the face of expansion this way.
For a long time, Tea Yan Yue Se indeed preferred the latter option.
But in recent years, Tea Yan Yue Se has changed.
On August 3, Tea Yan Yue Se opened two stores in Hefei at the same time. During queue times for the two theme “garden party” stores, the duration reportedly once approached 5 hours. The brand also said it plans to increase the number of local stores to 5 within the year.
Going further back, since late December 2024, Yichang, Huanggang, Changzhou, Ezhou, Yangzhou, Jingzhou, Taizhou, and Nantong have all gradually entered Tea Yan Yue Se’s expansion map.
This kind of pacing is not common in Tea Yan Yue Se’s expansion history over the past decade or more.
After being founded in 2013, it took seven years to get out of Hunan. After entering Wuhan, it waited nearly two more years before opening stores in Chongqing and Nanjing. In the past, pushing outward into a city might take one or two years; now it has begun opening multiple regions at the same time.
Behind the acceleration in expansion is the fact that the space Hunan is leaving for Tea Yan Yue Se is becoming more and more limited.
It’s undeniable that Changsha is still the market with the densest Tea Yan Yue Se store footprint and the strongest brand awareness. But Tea Yan Yue Se has already completed coverage of all 14 cities in Hunan. If it wants to add more stores in Hunan, it means either densifying in existing business districts or entering county-level markets with smaller capacity.
The former option would lead to diversion among stores, while the latter is also very hard to provide a sufficiently high revenue ceiling for a fully company-owned model.
In addition, over the past few years, Tea Yan Yue Se has also kept trying to make the Changsha market “thicker.”
In 2022, Yuan Yang Coffee was launched. After that, Gudemo Ning and Day and Night Poetry & Wine Tea were opened. Coffee, lemon tea, and low-alcohol tea-based drinks almost covered several of the hottest directions in the beverage industry at the time.
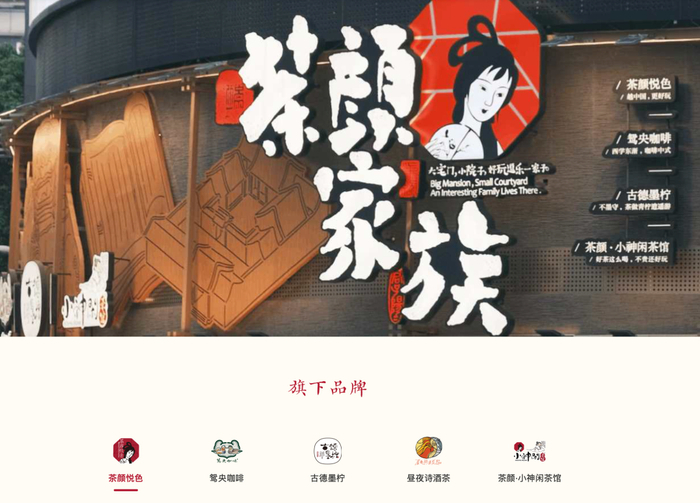
The sub-brand borrows Tea Yan Yue Se’s member system and brand traffic, and its launch speed isn’t slow. But as of now, only Gudemo Ning has surpassed 100 stores; the scale of Yuan Yang Coffee and Day and Night Poetry & Tea Wine remains limited. The three still haven’t broken out of the Changsha market.
The sub-brand failed to take on the growth task. As the main brand moved into more provinces, it gradually became an unavoidable choice.
Moreover, competition in local tea drinks in Hunan is also intensifying steadily. Brands such as Guming and Bawang Cha Ji have continued to densify their presence in Hunan in recent years, expanding their layout from core business districts into communities and county-level markets, directly diverting local consumers’ daily spending.
A few years ago, “going to Changsha to queue for Tea Yan Yue Se” was still a travel checklist staple for many people. The combination of regional scarcity and the influencer halo made Tea Yan Yue Se a bona fide “local specialty of the city.” Cross-city purchasing and queueing on someone’s behalf were once the norm. But now, as competitors’ store locations keep penetrating, this advantage is being gradually diluted.
On the product level, original-leaf milk tea used to be Tea Yan Yue Se’s biggest advantage in building brand-ization in its early days—its product format of freshly brewed tea base, fresh milk, and a cream top topped with crushed nuts, together with a naming system that reinforces a Chinese style, created a very strong market distinctiveness. But in the years when it tried coffee, lemon tea, and snacks, the market for original-leaf fresh milk tea had already seen a new set of leading players.
For its competitor in the same track—Bawang Cha Ji—after it listed on Nasdaq in 2025, in the first quarter of 2026 the brand’s global store count reached 7,531, including 374 overseas stores.
This brand, which was established later than Tea Yan Yue Se by four years, has already surpassed Tea Yan Yue Se in terms of scale and overseas business.
Competitors in the same track keep charging forward. That leaves Tea Yan Yue Se with less time and less space—so the window gets even narrower.
The road facing Tea Yan Yue Se is not that easy to take.
There are many competitors in Guangzhou, and there is also plenty of existing business. When a new mall opens, it naturally brings a surge in foot traffic; combined with the brand’s first-store effect, queues at opening are almost inevitable.
But the real watershed is whether the surrounding daily consumption can sustain stable store operations after the check-in trend fades—that’s the final test.
It’s not uncommon for tea-drink brands to show disparities in cross-city performance. For example, A’ma Handcrafted has long been in a state of scarcity—hard to get even one cup—in Shenzhen. After entering Guangzhou, it gained stable topic buzz but never reached the same level of explosive popularity.
Differences in consumer habits will also raise the operational threshold further. Guangzhou’s tea-drink market has stronger daily “necessity” attributes, and the delivery penetration rate is at a relatively high level nationwide. Local consumers are more inclined to buy nearby or order online; their willingness to specifically travel across districts to take a photo and wait in line for a long time is comparatively lower.
In the past, Tea Yan Yue Se has leaned toward an offline-to-store, light delivery operating logic. In Changsha, that can be part of the “check-in experience.” But in markets with a stronger daily-consumption attribute, it would instead raise consumers’ decision-making costs.
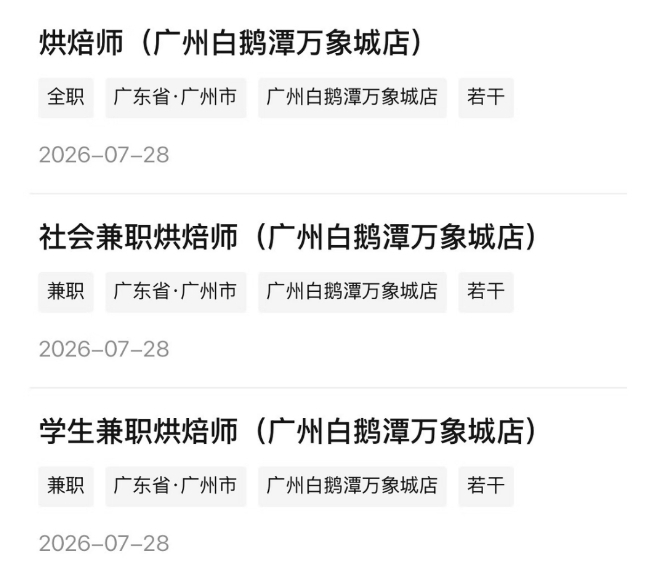
It’s worth noting that even if it chooses Bai’e Tang Wanxiangcheng, which is still in its commercial cultivation period, Tea Yan Yue Se can’t avoid direct competition. There are market rumors that Heytea will enter the same project in the form of a lab store. Information from recruitment platforms shows that relevant bakery positions had already started hiring at the end of July.
An even deeper challenge lies in reconstructing brand value.
Tea Yan Yue Se’s early brand premium was largely built on regional scarcity. The behavior of consumers specifically going to take photos and visit is, in itself, adding extra emotional value to the brand. As the brand’s stores continue to roll out nationwide, this sense of scarcity will keep being diluted, and the momentum of brand-related topics will likewise fall.
Red Meal’s supply chain guide noted that in cities that entered earlier—such as Chongqing and Wuhan—store “hype” has shown varying degrees of decline. Meanwhile, the brand’s core bestsellers for Tea Yan Yue Se are still mainly the few products from its early days, with no fundamental changes to its product lineup.
When original-leaf fresh milk tea becomes an industry-standard category and the product-side differentiation advantage keeps narrowing, it becomes hard for the brand to build a long-term moat based on product form alone.
Not to mention the fully company-owned model that Tea Yan Yue Se has always adhered to.
The single-store operating model in Changsha’s core business districts is built on high-density customer flow. Guangzhou’s commercial landscape is relatively dispersed: foot traffic is distributed across multiple business districts and community commercial nodes. If Tea Yan Yue Se wants to improve how often consumers are reached, it needs to add store locations across multiple areas.
Under a fully company-owned model, fixed costs such as rent and labor must be fully borne by the brand itself. The difficulty of reaching break-even at the store level is significantly higher than for franchise brands. Without enough store count, the costs of local warehousing and management teams cannot be quickly spread out, and the store-opening pace is likely to fall into a passive cycle.
For Tea Yan Yue Se, the “Guangzhou gate” it faces has never been about generating opening buzz. Instead, it is about the brand’s real ability to survive after it leaves the soil of Changsha. Tea Yan Yue Se’s nationalization has no way back. This “elite matchup” in Guangzhou is both the checkpoint it has to pass and the key test of whether its model can break free from regional roots.