$SNDK
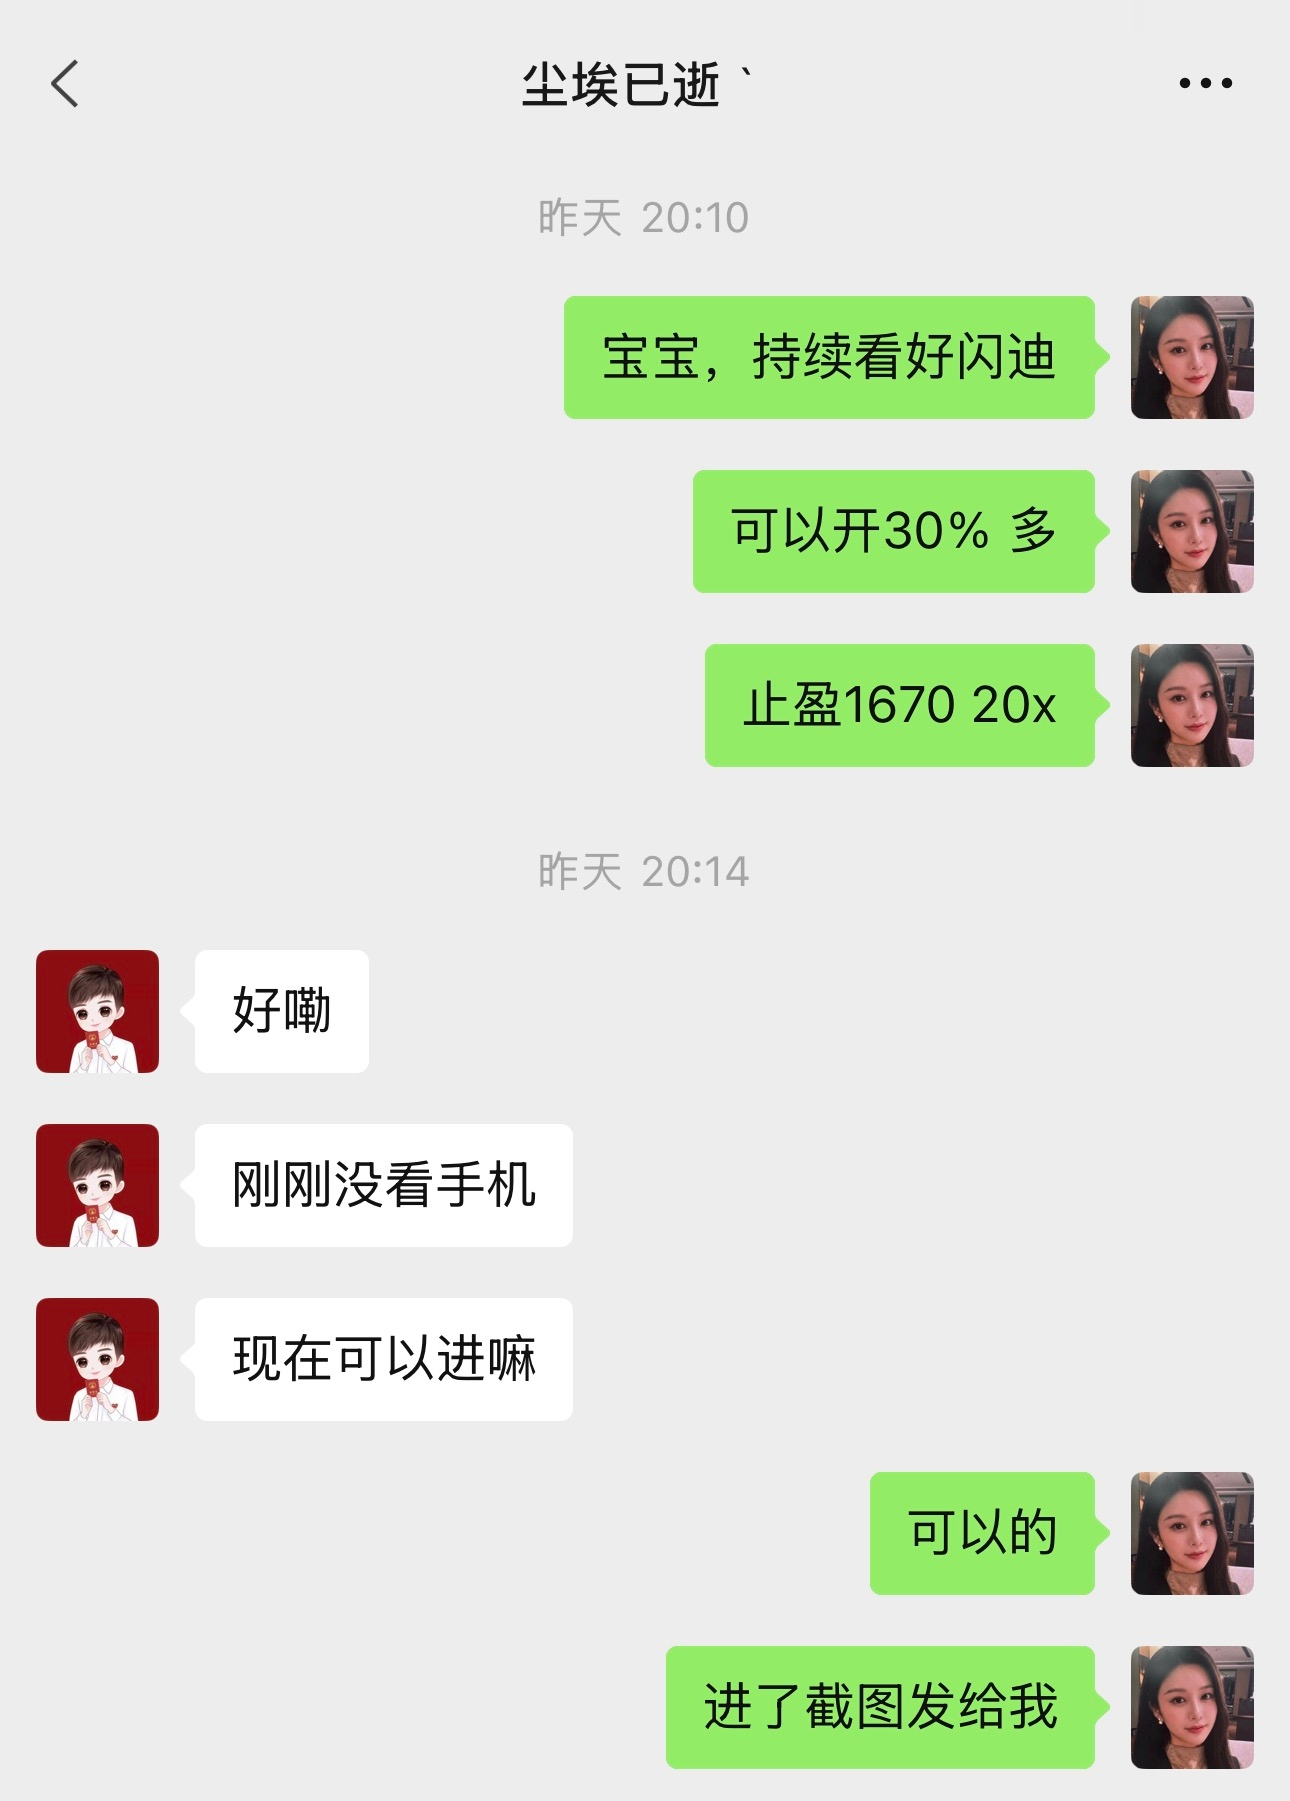
The logic behind this bullish setup is pretty solid—it’s not that flimsy kind of hype. A few key points are laid out on the table:
1. Record-breaking performance—the fundamentals hold up
For fiscal 2026 Q4, the gross margin jumped from 26.4% in the same period last year to nearly 85%. EPS surged from $0.29 to $39.25. This isn’t storytelling—it’s earned in real money.
2. Long-term contracts lock in profits for the coming years
They signed eight long-term customers, securing about 50% of shipments for fiscal 2027 and roughly two-thirds of shipments for fiscal 2028. Outstanding performance obligations are as high as $41.6 billion. In other words, the message to the market is: my revenue for the next few years is already covered—you don’t have to guess.
3. AI demand isn’t just short-term speculation—it’s a structural shortage
Micron says the tight balance will continue beyond 2027. SK hynix is even more aggressive, stating that the shortage runs through 2030. This year’s AI data center capex is at least $75 billion, and Alphabet is still ramping up. SanDisk’s NAND is one link you can’t bypass in this chain.
4. The company is proactively rewarding shareholders
With zero debt on the balance sheet, it also approved a $6.0 billion share repurchase plan. You don’t need to say much about how management views the company’s future.
So overall for now, I still look favorably on SanDisk’s upward trajectory. Teacher Angle and the fans have already added extra pockets to their clothes, aiming to make this one packed full too!!!
The logic behind this bullish setup is pretty solid—it’s not that flimsy kind of hype. A few key points are laid out on the table:
1. Record-breaking performance—the fundamentals hold up
For fiscal 2026 Q4, the gross margin jumped from 26.4% in the same period last year to nearly 85%. EPS surged from $0.29 to $39.25. This isn’t storytelling—it’s earned in real money.
2. Long-term contracts lock in profits for the coming years
They signed eight long-term customers, securing about 50% of shipments for fiscal 2027 and roughly two-thirds of shipments for fiscal 2028. Outstanding performance obligations are as high as $41.6 billion. In other words, the message to the market is: my revenue for the next few years is already covered—you don’t have to guess.
3. AI demand isn’t just short-term speculation—it’s a structural shortage
Micron says the tight balance will continue beyond 2027. SK hynix is even more aggressive, stating that the shortage runs through 2030. This year’s AI data center capex is at least $75 billion, and Alphabet is still ramping up. SanDisk’s NAND is one link you can’t bypass in this chain.
4. The company is proactively rewarding shareholders
With zero debt on the balance sheet, it also approved a $6.0 billion share repurchase plan. You don’t need to say much about how management views the company’s future.
So overall for now, I still look favorably on SanDisk’s upward trajectory. Teacher Angle and the fans have already added extra pockets to their clothes, aiming to make this one packed full too!!!