Net income has increased. So why might EPS barely change?
Because profit per share has a denominator:
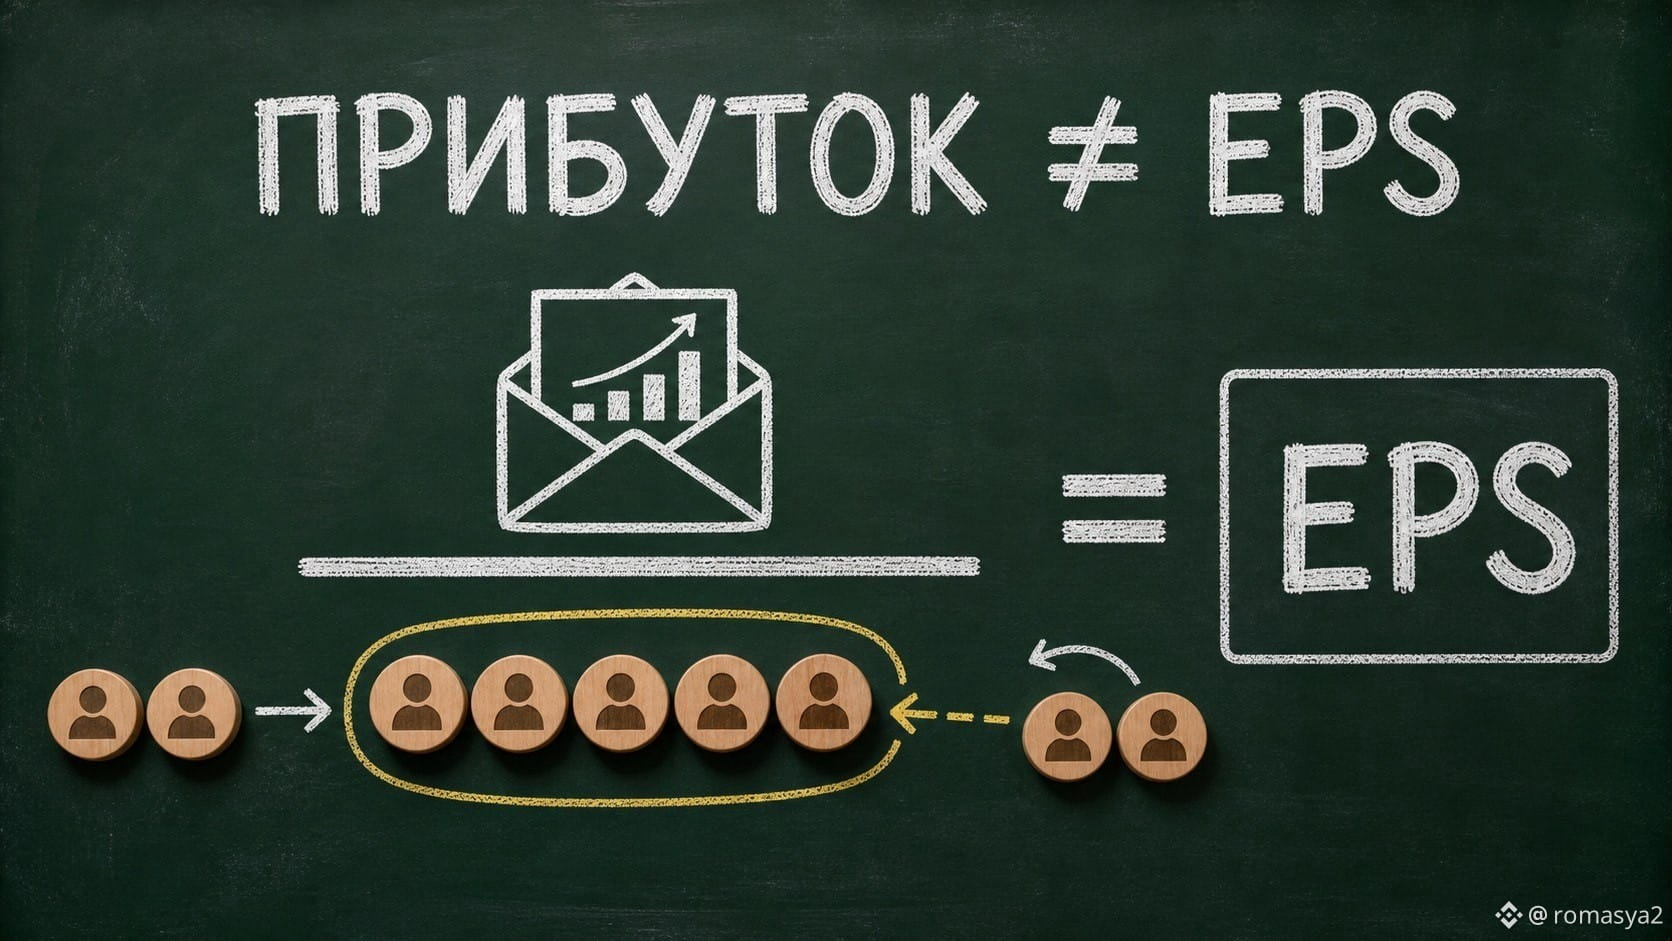
Diluted EPS = profit for common shareholders ÷ weighted-average diluted number of shares.
If a company actively issues shares as compensation or raises capital, the number of shares can increase. Then more earnings are spread across a larger number of units. Share buybacks work in the opposite direction, but their effect also needs to be checked in the report—not assumed.
For bStocks like $PLTRB, $AAPLB, or $AMZNB, I would look at three lines right away: net income, basic weighted-average shares, and diluted weighted-average shares.
Another trap is comparing reported EPS with adjusted EPS. These are different metrics, and the adjustments must be read in the reconciliation table.
My practical takeaway: analyzing EPS starts not with the EPS itself, but with its numerator and denominator.
Do you usually check changes in the number of shares?
@BinanceCIS #bStocksCIs
Because profit per share has a denominator:
Diluted EPS = profit for common shareholders ÷ weighted-average diluted number of shares.
If a company actively issues shares as compensation or raises capital, the number of shares can increase. Then more earnings are spread across a larger number of units. Share buybacks work in the opposite direction, but their effect also needs to be checked in the report—not assumed.
For bStocks like $PLTRB, $AAPLB, or $AMZNB, I would look at three lines right away: net income, basic weighted-average shares, and diluted weighted-average shares.
Another trap is comparing reported EPS with adjusted EPS. These are different metrics, and the adjustments must be read in the reconciliation table.
My practical takeaway: analyzing EPS starts not with the EPS itself, but with its numerator and denominator.
Do you usually check changes in the number of shares?
@BinanceCIS #bStocksCIs