A few days ago, I chatted with a friend who trades gold. He said something that really stuck with me—
"In the gold vaults in London, a lot of the gold is 'rented out,' but it's never moved.""
When I looked it up later, it turned out to be the gold lending market that took shape in the 1990s.
Central bank gold sits in vaults most of the time as dead assets, so it’s leased to investment banks and gold miners. The lease rate is priced off the LIBOR-lease rate, and the annualized return is usually only about 0.5%–2%. After taking the contract, the borrower uses it for hedging, arbitrage, and production planning.
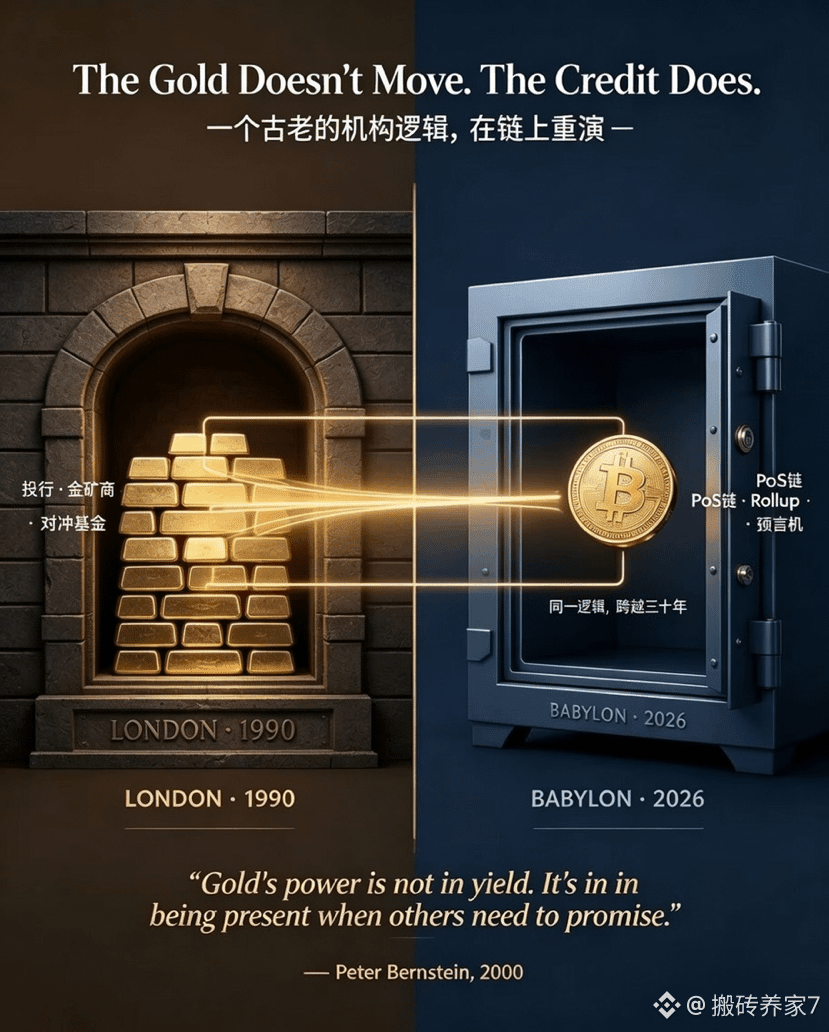
The physical gold never left the vault, but its credit circulates globally.
I looked at Babylon’s TBV, and that image kept playing in my head.
BTC is locked on-chain, constrained by scripts, and the private key stays with the user. Through Babylon, it provides finality guarantees to PoS chains, time proofs, and economic security.
The yield is low—almost the same order of magnitude as the gold leasing market.
This isn’t a coincidence. Any highly scarce reserve asset, once it starts being lent out, is destined to have a low yield. Its value anchor lies in the scarcity itself, not in its ability to generate interest.
Peter Bernstein wrote in *The Power of Gold*: "The power of gold is not that it generates how much return, but that when it’s present, other systems dare to make commitments."
Replace "gold" with "BTC," and the statement still holds.
Criticism of TBV’s low yield comes from people using a DeFi yield ruler to measure it. But if you use the ruler of gold leasing—where London vault lease rents have been around 1% for decades—nobody considers that market a failure.
@BabylonLabs_io is betting on BTC taking an institutionalization path, not becoming an interest-bearing asset, but becoming a reserve anchor of "value when present."
So maybe the real question isn’t "Is BABY yield high enough?"—but rather: when will the crypto world start treating BTC the way central banks treat gold?
#baby #Babylon $BABY
"In the gold vaults in London, a lot of the gold is 'rented out,' but it's never moved.""
When I looked it up later, it turned out to be the gold lending market that took shape in the 1990s.
Central bank gold sits in vaults most of the time as dead assets, so it’s leased to investment banks and gold miners. The lease rate is priced off the LIBOR-lease rate, and the annualized return is usually only about 0.5%–2%. After taking the contract, the borrower uses it for hedging, arbitrage, and production planning.
The physical gold never left the vault, but its credit circulates globally.
I looked at Babylon’s TBV, and that image kept playing in my head.
BTC is locked on-chain, constrained by scripts, and the private key stays with the user. Through Babylon, it provides finality guarantees to PoS chains, time proofs, and economic security.
The yield is low—almost the same order of magnitude as the gold leasing market.
This isn’t a coincidence. Any highly scarce reserve asset, once it starts being lent out, is destined to have a low yield. Its value anchor lies in the scarcity itself, not in its ability to generate interest.
Peter Bernstein wrote in *The Power of Gold*: "The power of gold is not that it generates how much return, but that when it’s present, other systems dare to make commitments."
Replace "gold" with "BTC," and the statement still holds.
Criticism of TBV’s low yield comes from people using a DeFi yield ruler to measure it. But if you use the ruler of gold leasing—where London vault lease rents have been around 1% for decades—nobody considers that market a failure.
@BabylonLabs_io is betting on BTC taking an institutionalization path, not becoming an interest-bearing asset, but becoming a reserve anchor of "value when present."
So maybe the real question isn’t "Is BABY yield high enough?"—but rather: when will the crypto world start treating BTC the way central banks treat gold?
#baby #Babylon $BABY