

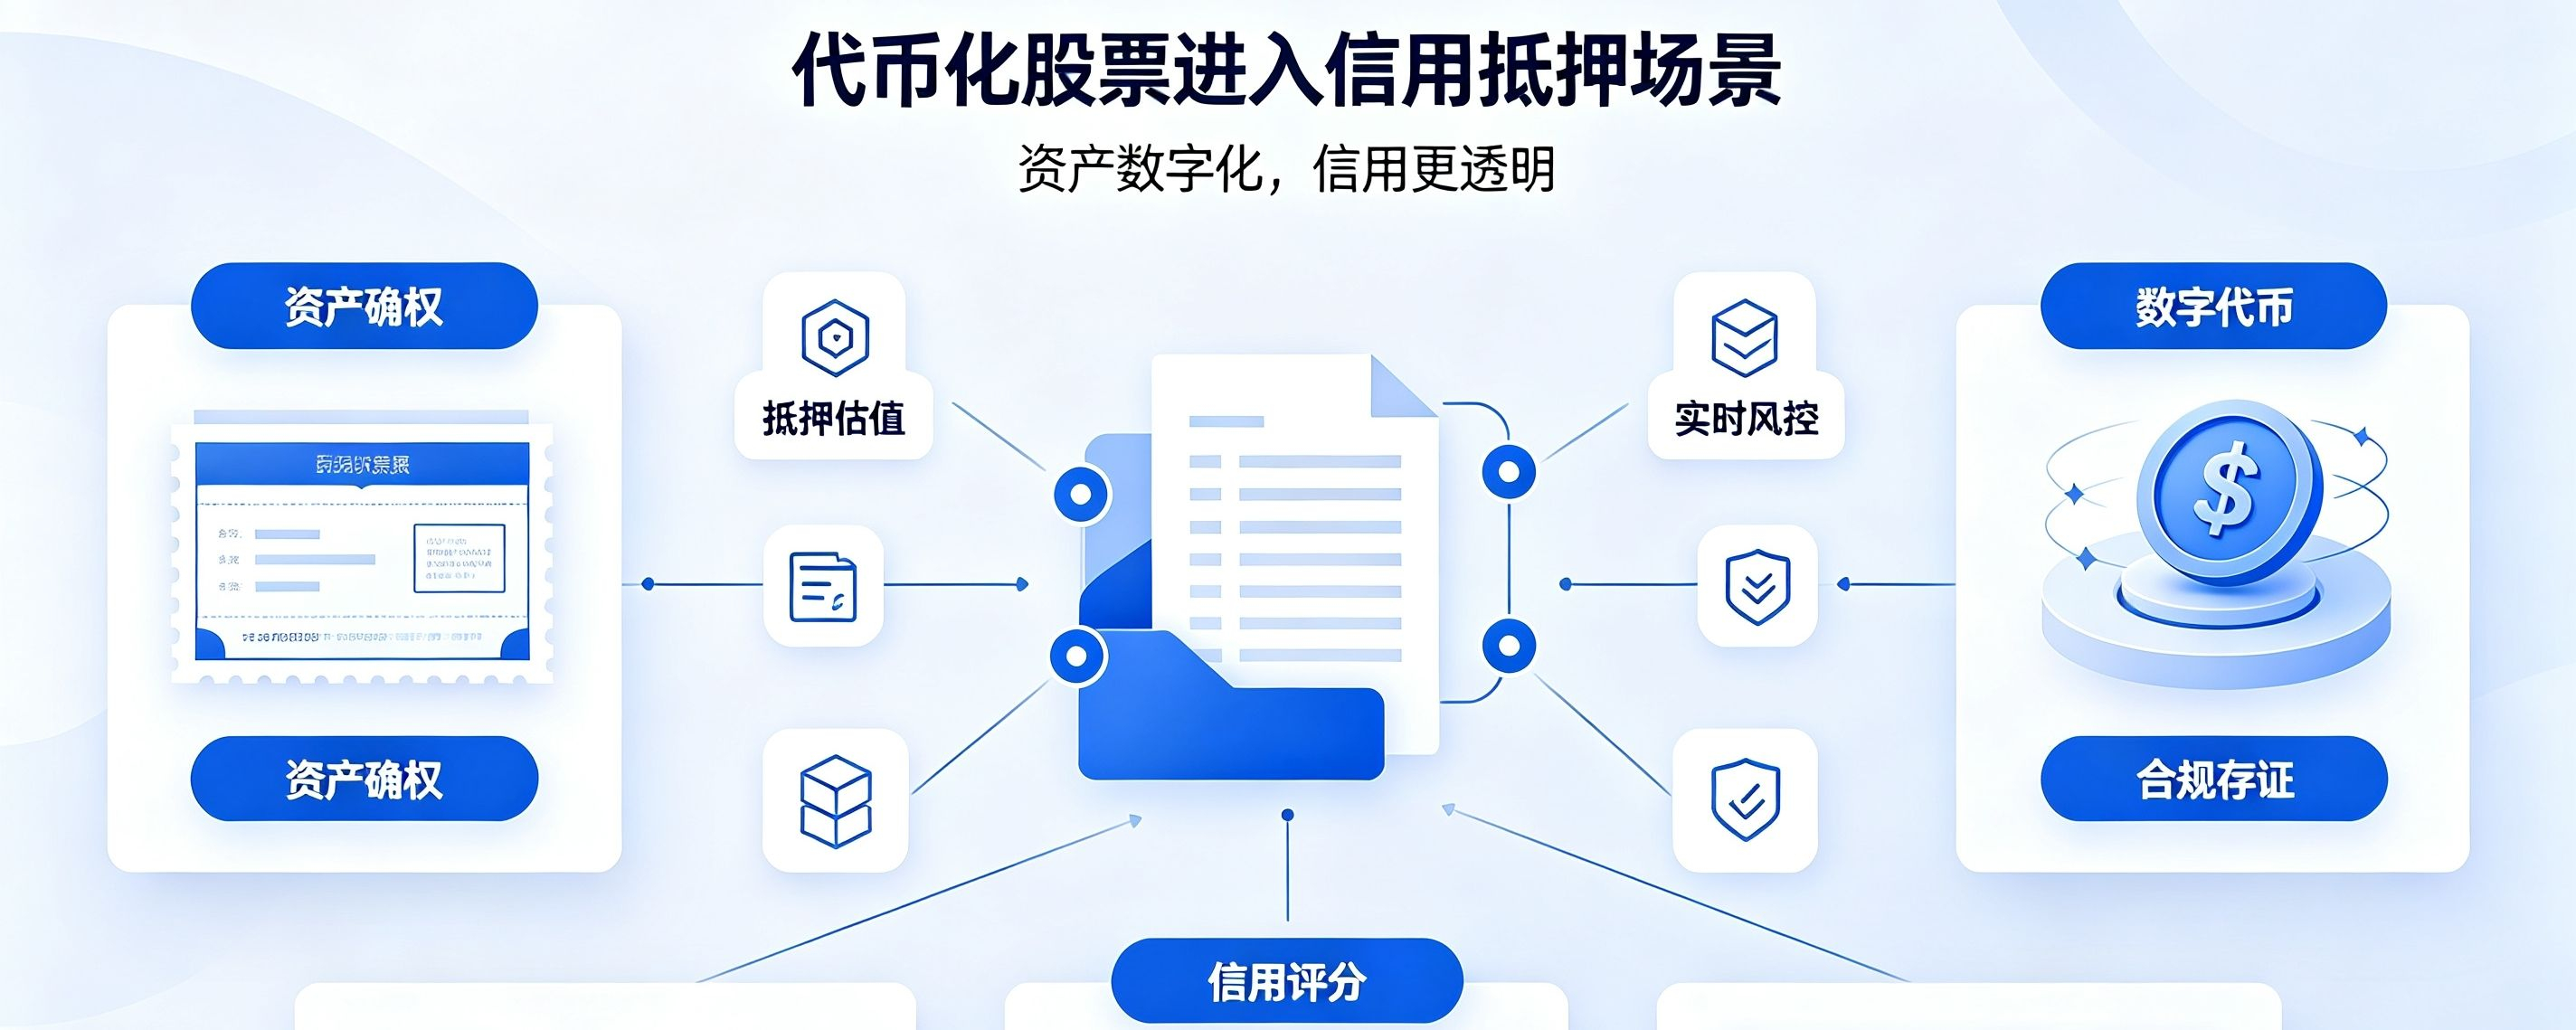
On July 3, the crypto exchange Kraken announced that tokenized stocks from companies such as Nvidia, Apple, and Tesla can be directly used as collateral for margin trading. Only four days later, Binance—the world’s largest crypto exchange—also announced almost identical measures.
These two pieces of news may look like nothing more than "an additional set of collateral types," but if you place them on a longer timeline, they point to an ongoing structural shift: stocks from the traditional world are beginning to enter, officially, the credit system of the crypto world.
From "sell" to "collateral": a crucial fork in the road
Suppose you have $100,000 worth of NVIDIA stock, and you’re bullish long-term and don’t want to sell. Meanwhile you think bitcoin has already dropped enough, but you don’t have spare cash. In the past there was only one path: sell your NVIDIA for dollars, move to a crypto exchange, and then buy bitcoin—stocks are stocks, crypto is crypto, separated by a wall with significant friction costs.
What Kraken and Binance are doing in essence is creating an entry point in that wall: you don’t have to sell NVIDIA. The exchange treats tokenized stocks as collateral, allowing you to open bitcoin or ether positions using that collateral power—or even add leverage directly.
This is consistent with the logic of "mortgage loans on property": you can’t take the house directly to buy groceries, but the bank recognizes its value and allows you to borrow against it. The asset remains, but its value is reused. The key difference is that selling ends the asset, while collateralizing extends the asset’s credit.
Haircut: How exchanges price risk
Kraken doesn’t calculate borrowing capacity based on the asset’s full market value. Instead, it applies discounts to each type of asset—an industry term known as a "haircut." Among the first batch of ten disclosed stock tokens, stable assets like SPY and QQQ have discounts of about 10%; tech stocks like Apple, Tesla, and NVIDIA are around 20%; and more volatile ones like Robinhood, Strategy, and Circle can reach 30%.
For example, if you hold NVDAx with a market value of $100,000 and the haircut is 20%, the collateral value recognized by the system is $80,000. The discount rate reflects the exchange’s assessment of the asset’s volatility and liquidity risk.
A detail that needs clarification: tokenized stocks are not true stocks
It’s worth noting that NVDAx and SPYx on the exchange are not the same as actual NVIDIA stock or the S&P 500 index. They are independent tracking security products—unable to be transferred into a traditional brokerage account to exchange for real shares. Holding an Apple token also doesn’t mean you have voting rights in Apple.
So why is the exchange still willing to accept it as collateral? The key isn’t the legal label of the asset, but whether it has reliable pricing, sufficient liquidity, and can be handled quickly during periods of extreme volatility. As long as those conditions are met, such assets can be included in the collateral system.
Two-way leverage: capital efficiency and risk transmission
The appeal of this mechanism lies in "betting both ways on the same asset"—NVIDIA continues to help you gamble on upside, while it also supports your bitcoin position. If both types of assets rise in the same direction, that’s the ideal scenario.
But the risks run in the opposite direction. Once there’s a global selloff of risk assets, while your bitcoin position is losing money, the tokenized stock used as collateral also shrinks in value. This double squeeze forces position reductions and may even trigger liquidation.
This means that if you hold stocks on their own, even if they fall, they don’t go to zero; there’s still potential for long-term recovery. But once they’re used as collateral and leverage is added, in extreme markets they may be wiped out in a single stroke. When prices rise, it boosts capital efficiency; when prices fall, it turns into risk transmission between two markets.
Why this is worth paying attention to
A year ago, discussions around stock tokenization were still focused on basic questions like "Can it be traded 24 hours a day?" "Can it be bought for one dollar?" Now, the question has shifted to: after stocks are moved into the crypto world, what functions can they still serve?
From stock perpetual futures at the beginning of the year to stock-collateralized crypto purchases today, traditional brokerages are also bringing crypto assets into their own trading accounts. These two paths are moving toward each other—going forward, the boundary between stock accounts and crypto accounts may no longer be as clear as it is today.
No predictions—just mechanisms. What truly deserves ongoing attention is how this cross-market credit system will be tested in the next extreme market event.