


Starting from January 1, 2026, a historic shift in cryptocurrency taxation will be implemented across 48 jurisdictions globally, including the UK and EU member states. This year, as the framework for reporting crypto assets is launched worldwide, cryptocurrency investors in these 48 countries will begin having their crypto wallet transaction data recorded for tax purposes.
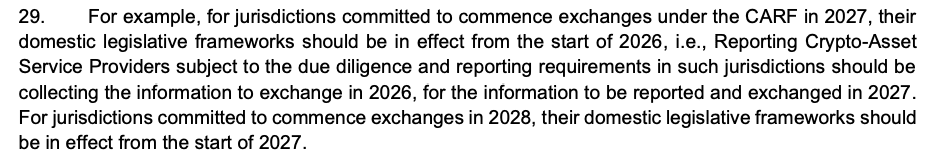 Source: OECD
The international tax transparency framework for crypto asset reporting (CARF), developed by the Organisation for Economic Co-operation and Development (OECD), will officially come into effect in 2027. However, from January 1 of this year, cryptocurrency service providers in participating jurisdictions (including centralized exchanges, decentralized exchanges, cryptocurrency ATMs, and brokers and traders) have been required to start collecting necessary transaction data to combat tax evasion and money laundering activities.
In a report update in November, the OECD stated that an increasing number of jurisdictions have committed to exchanging information under the CARF framework starting in 2027. These jurisdictions have enacted the necessary legislation to mandate cryptocurrency service providers to collect CARF-related data or are in the "final stages" of enforcing these laws.
The OECD's cryptocurrency asset reporting framework (CARF) signifies a fundamental change in monitoring digital asset transactions and reporting them to tax authorities. Under this new regime, major cryptocurrency exchanges must now collect comprehensive transaction data from users and report detailed transaction information and tax residency status to national tax authorities.
This framework represents a coordinated international effort aimed at eliminating the anonymity historically associated with cryptocurrency transactions.
Exchanges operating in participating jurisdictions must now maintain complete user transaction records, including asset types, acquisition dates, costs, disposal dates, gains, fees, and wallet addresses. This standardized approach establishes a unified global standard for cryptocurrency taxation, with participating countries committing to automatically share relevant data starting in 2027. The UK's tax authority (HMRC) will begin exchanging data with EU member states, Brazil, the Cayman Islands, South Africa, and other participating countries based on reciprocal agreements.
The implementation of CARF reflects the growing consensus among the international community regarding cryptocurrency regulation and tax compliance. Among the 75 countries committed to implementing this framework, 48 have now actively enforced it, with others expected to follow suit.
The United States plans to implement CARF in 2028 and begin information exchange in 2029. This phased global push establishes an increasingly interconnected tax enforcement system, where cryptocurrency users will face stricter scrutiny and audit risks regardless of their location.
For cryptocurrency users and traders, the new rules require immediate compliance actions. Individuals must provide personal information to cryptocurrency service providers before the reporting deadline and maintain detailed records of all transactions.
Tax authorities have made it clear that non-compliance will lead to severe penalties, and enforcement mechanisms have been strengthened to identify underreported or unreported gains. The framework treats cryptocurrency transactions as taxable events—whether through direct sales, exchanges between different cryptocurrencies, or participation in decentralized finance activities—fundamentally changing how digital asset holders handle their tax obligations.
"The implementation of cryptocurrency asset reporting framework by 48 jurisdictions marks a historic shift in cryptocurrency taxation" was first published on (Blockcast).