


BitMine playing options directly wiped out its profits.
Written by: Oluwapelumi Adejumo
Compiled by: Chopper, Foresight News
BitMine is aggressively expanding its Ethereum holdings, trying to convert them into a stable cash-flow source. In the previous quarter, revenue from its staking business was nearly $46 million.
However, a $92.1 million loss from derivative options fully wiped out the staking returns. Coupled with continuously rising asset management costs and the company’s aggressive stock issuance, the space for returns for existing shareholders has been greatly squeezed.
The Q3 financial report for fiscal year 2026 as of May 31 shows the company’s revenue surged from $2.1 million year-over-year to $46.5 million. Of that, 98% ($45.7 million) came from staking and node validation businesses. BitMine is accelerating the divestment of its Bitcoin mining business and fully shifting to an Ethereum treasury-holding model.
Behind the sharp growth in revenue, the company recorded a net loss of $83.6 million this quarter, compared with a small net loss of only $0.623 million in the same quarter last year—its loss magnitude expanded rapidly.
A massive options loss wipes out all Ethereum staking gains
The core factor dragging down this quarter’s performance is the company’s Ethereum derivatives options trading strategy. In this quarter, BitMine recorded total losses on Ethereum-related derivatives of $92.1 million, about twice the total revenue from its staking business in the same period. Of this, $78.6 million came from net losses on expiring option contracts, and $14.0 million came from losses on exercised positions. The $0.534 million gain from open contracts only offsets part of the losses slightly.
In the same period last year, the company did not conduct any derivatives trading, and its risk exposure in the asset-management business jumped qualitatively. In the first nine months of this fiscal year, cumulative derivatives losses totaled $133.3 million, including $79.3 million from exercise losses and $54.5 million from losses on expiring contracts; only $0.515 million in gains came from open contracts. In the same period, the combined revenue from staking and validation businesses was only $56.9 million, meaning the scale of derivatives losses was more than twice the staking revenue.
BitMine states that its options strategy is mainly centered on selling put options and is part of an overall position-management plan. Selling put options can earn premium and add to assets when prices fall, but if the market moves against the position and the contracts are exercised under unfavorable conditions, it will result in substantial losses. This large loss is enough to show that attempts to enhance returns through options have, for now, completely offset the stable income generated by the node staking business.
At the same time, the company’s administrative and general management expenses surged from $0.744 million in the same period last year to $37.30 million. Management explained that the increase was mainly driven by digital asset custody and asset-management service fees, salary raises, and higher compensation to directors in cash and stock forms.
Before excluding changes in the valuation of crypto assets, the pledged-revenue was sufficient to cover this quarter’s cost of sales and management expenses. Even after deducting multiple non-cash items, the company’s own adjusted non-GAAP net loss still reached $70.8 million. This financial report shows that the node validation business has already formed a sizable and stable cash flow, but the overall position-trading strategy continues to consume pledged-profit.
Continuing to issue more BMNR shares and hoard Ethereum, significantly diluting shareholders’ equity
Most of the funds for BitMine’s large-scale hoarding of Ethereum comes from issuing common stock in public markets, with the costs borne entirely by existing shareholders. Within the nine months ended May 31, under an in-market issuance plan the company cumulatively sold 340.7 million shares of BMNR common stock, raising $11.87 billion after issuance expenses. In the same period, it spent $11.69 billion to buy Ethereum.
Shareholders’ equity is significantly diluted. Over nine months, the number of circulating common shares increased by 149%, from 232.4 million shares as of August 31, 2025 to 579.7 million shares by the end of May 2026; and issuance continued even after the quarter ended. As of July 9, the total shares outstanding had reached 603.2 million shares.
Backed by equity financing, as of May 31 BitMine had cumulatively held 5.42 million ETH, with an average cost basis of $19.05 billion; at the time of writing, the holdings had grown to 5.70 million ETH.
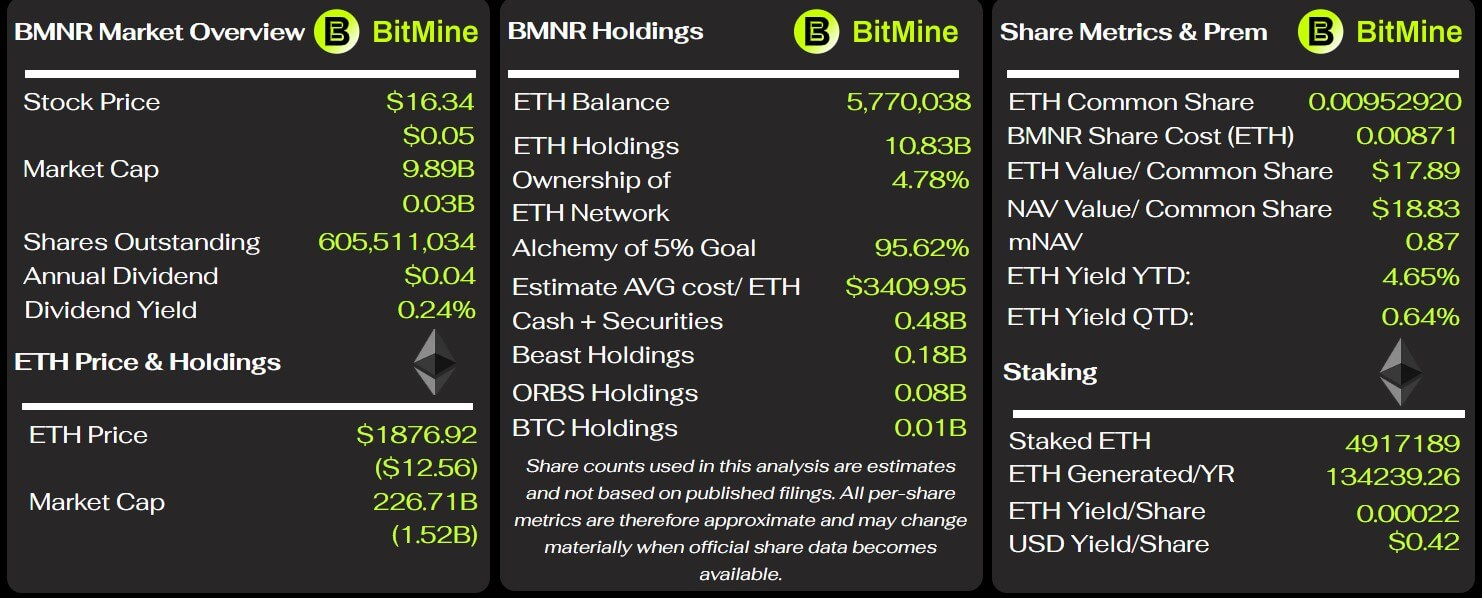
BitMine’s key metrics, source: BitMine Tracker
As of the end of May, the market value of this batch of Ethereum holdings was only $10.86 billion, with an unrealized floating loss of about $8.2 billion—meaning the floating loss rate was 43%.
This impairment of the position is the main source of the company’s unrealized loss of $9.04 billion in digital assets during the first nine months of this fiscal year; in the same period, the company’s cumulative net loss was $9.1 billion. The huge floating loss clearly reflects that BitMine bought Ethereum at a high price by issuing shares, with all risk borne by shareholders.
Earlier this January, the shareholders’ meeting approved raising the company’s authorized limit for common stock from 500 million shares to 50 billion shares. This authorization does not mean the company must issue the full amount, but it gives management ample room to continue issuing shares to purchase digital assets and make other investments.
BitMine warns that its ability to expand Ethereum holdings depends heavily on continued access to smooth and uninterrupted financing channels. A decline in Ethereum’s price, weakness in the company’s stock price, and cooling investor subscription demand will all raise future financing costs, and may even limit the company’s ability to issue securities on favorable terms.
The support conditions for this business model are not just staking annualized returns and further increases in Ethereum’s price. Shareholders must also accept substantial equity dilution, with the positions carrying a floating loss on the order of billions for years—continuing to provide funding for the company to hoard crypto.
Long-term service contracts raise staking operating costs and squeeze profit margins
BitMine relies on its staking business to hedge fluctuations in its position price, but the accompanying long-term cooperation agreements generate fixed fees and profit-sharing arrangements that continuously compress overall profit. The company has signed a 10-year advisory agreement with third-party service provider Ethereum Tower; this quarter it spent $12.8 million for this, about 28% of total staking revenue for the period. Over the first nine months, cumulative expenses for this item were $37.5 million. The company estimates annual expenses in a range of $40 million to $50 million, billed according to a tiered schedule based on the total value of the digital assets under custody.
This agreement can be terminated only under a limited set of specific conditions. If BitMine terminates the cooperation without a valid reason, it must pay Ethereum Tower 85% of the total estimated service fees for the remaining contract term.
In addition, after acquiring node operator Pier Two, BitMine separately entered into a 10-year management services agreement. Under the agreement, Ethereum Tower receives 2% equity in the MAVAN platform and receives a monthly profit share based on the platform’s native staking reward ratio. As of May 31, the company had not accrued expenses related to this agreement, so the associated cost of the profit share had not yet appeared in the staking business profit and loss statement.
BitMine says that the vast majority of its Ethereum is staked through MAVAN, and over the long term the staking rewards are sufficient to cover the asset custody costs. On an operational basis for this quarter alone, staking revenue does cover the sales and administrative expenses excluding changes in the valuation of crypto assets. However, the addition of ten-year fixed advisory fees, future upside-sharing arrangements, and various asset-management-related expenditures means that relying solely on staking revenue cannot fully reflect the business’s true profitability.
Although BitMine has no debt, its reliance on the capital markets is growing ever deeper
As of the end of May, BitMine’s leverage in its balance sheet structure was extremely low. It held $340.3 million in cash and had $433.1 million in working capital, with no traditional debt. Total assets were $11.63 billion, and total liabilities were only $30.1 million; the vast majority of its assets were digital assets such as Ethereum. Based on the statements, the company does not face an immediate debt-repayment crisis, but in the first nine months cash flow from operating activities was negative $287.6 million. The company says that cash consumption mainly resulted from legal, consulting, investment-banking fundraising, and other related expenses arising from the expansion of its Ethereum positions.
After the quarter ended, BitMine again issued 3.5 million shares of 9.5% annualized perpetual preferred stock, BMNP, raising $273.8 million. This share issuance provides liquidity in the short term, but adds a rigid annual outflow of $33.25 million in preferred dividends. This security is equity rather than debt, but its claim ranks ahead of common stock, and the high dividends continue to tie up the company’s cash flow.
Management’s assessment is that current cash, expected operating cash flows, and in-market issuance tools are sufficient to support at least the next 12 months of operations. This assessment holds on the premise that the capital markets continue to provide an open financing window: if Ethereum trading conditions remain weak for the long term, the company’s share price weakens, and investor subscription willingness falls, financing costs will rise and operating flexibility will be constrained.
Based on the latest financial results, BitMine faces a set of contradictory realities: On one hand, the company has built a mature staking business that generates tens of millions of dollars of revenue per quarter, sufficient to cover core operating expenses. On the other hand, large losses from options completely absorb staking profits; long-term cooperation contracts continue to raise management costs; and the expansion of Ethereum hoarding relies entirely on issuing additional shares, with the total shares outstanding already increasing by more than one hundred percent.
Therefore, BitMine’s long-term economic benefits depend on whether staking revenue can consistently cover various asset-management costs and options losses, whether the company can continue to secure equity financing steadily, and whether the price of Ethereum can rebound significantly.