


In 2025, the prediction market is expected to accelerate towards mainstream: brokers, sports platforms, and crypto products will enter simultaneously, and the demand has been validated. The real watershed is no longer product innovation, but whether large-scale implementation can be achieved within the regulatory framework.
Article author, source: MarsBit
This article points out that the prediction market is entering a knockout stage focused on compliance, settlement, and distribution, using global regulatory comparisons, the divergence of on-chain and compliant paths, and the 2026 World Cup as a 'system-level stress test.' The winner will be the platform that can operate stably under peak loads and strong regulation.
The original text is as follows:
The U.S. event contract market significantly accelerated in 2025, resonating with the approach of a 'generational-level' catalyst.
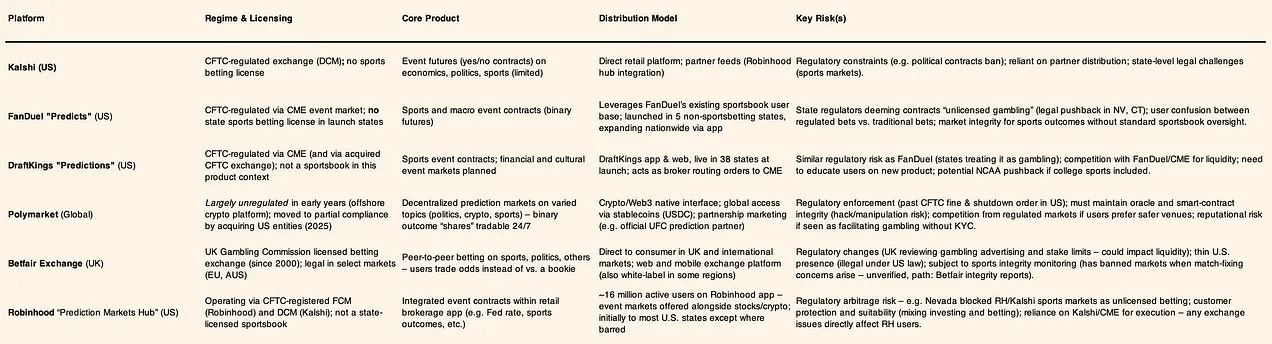
Kalshi's valuation doubled to $11 billion, with Polymarket reportedly also seeking higher valuation levels; meanwhile, platforms targeting the mass market—including DraftKings, FanDuel, and Robinhood—are launching compliant prediction products ahead of the 2026 FIFA World Cup (to be held in North America). Robinhood anticipates that the event market has generated approximately $300 million in annualized revenue, becoming its fastest-growing business line, indicating that 'opinion-based trading' is entering the financial mainstream at scale.
However, this growth is colliding head-on with regulatory realities. As platforms prepare for participation peaks driven by the World Cup, prediction markets are no longer just a product issue but increasingly a 'regulatory design' issue. In reality, the focus of team building is shifting from merely meeting user needs to designing for legal characterization, jurisdictional boundaries, and settlement standards. The importance of compliance capabilities and distribution partnerships is gradually matching that of liquidity; the competitive landscape is increasingly shaped by 'who can scale operations within an acceptable framework,' rather than 'who can launch the most markets.'
Intersecting forces of regulation
The U.S. Commodity Futures Trading Commission (CFTC) allows only a small class of event contracts linked to economic indicators, deeming other types as unacceptable gambling. In September 2023, the CFTC blocked Kalshi's attempt to launch political futures; however, a subsequent court challenge granted limited approval for contracts related to the presidential election.
At the state level, regulatory attitudes towards 'sports-like' markets are tougher. In December 2025, the Connecticut gambling regulator issued a cease and desist order to Kalshi, Robinhood, and Crypto.com, determining that the sports event contracts they offered constituted unlicensed gambling; Nevada also sought judicial action to stop similar products, forcing related platforms to delist in the state.
In response, established giants like FanDuel and DraftKings are restricting prediction products to jurisdictions where 'legal sports betting is not yet possible', highlighting that distribution strategies are driven by regulatory boundaries rather than user needs. The core implication is already very clear: what determines scale is not product innovation but regulatory tolerance. Contract design, settlement terms, marketing language, and geographical expansion paths are being systematically engineered to pass legal characterization reviews; platforms that can operate within accepted regulatory frameworks will gain more lasting advantages. In this market, regulatory clarity itself constitutes a moat, while uncertainty directly limits growth.
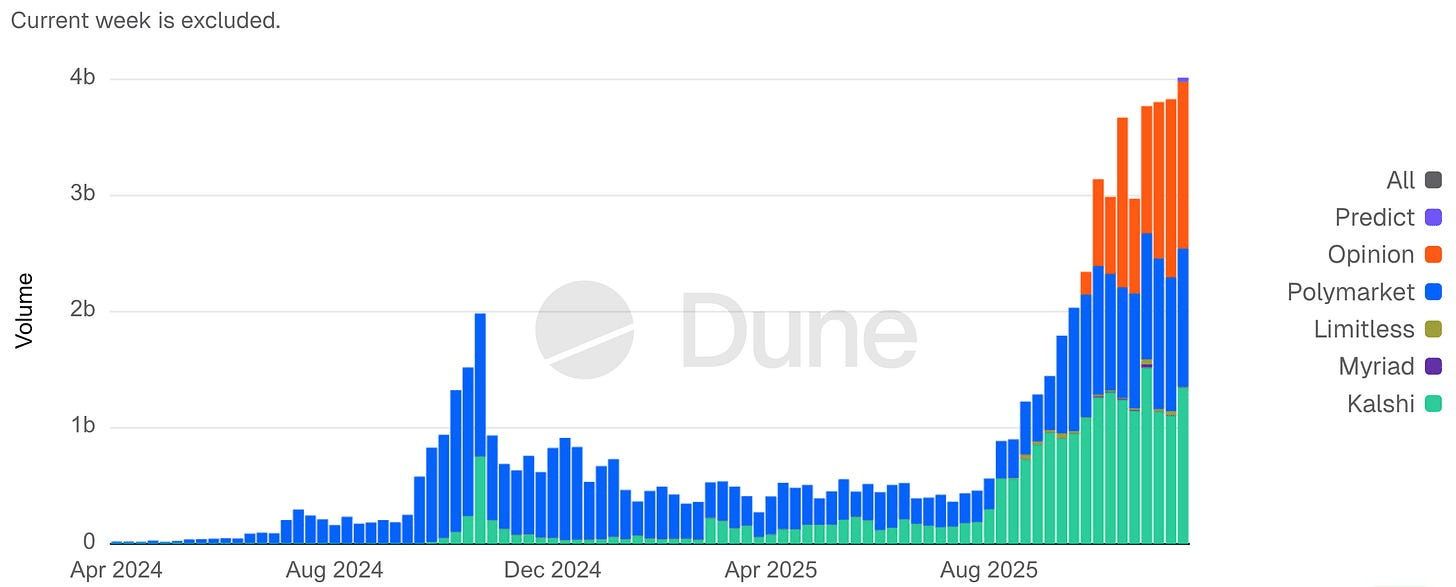
Weekly Prediction Market Notional Volume
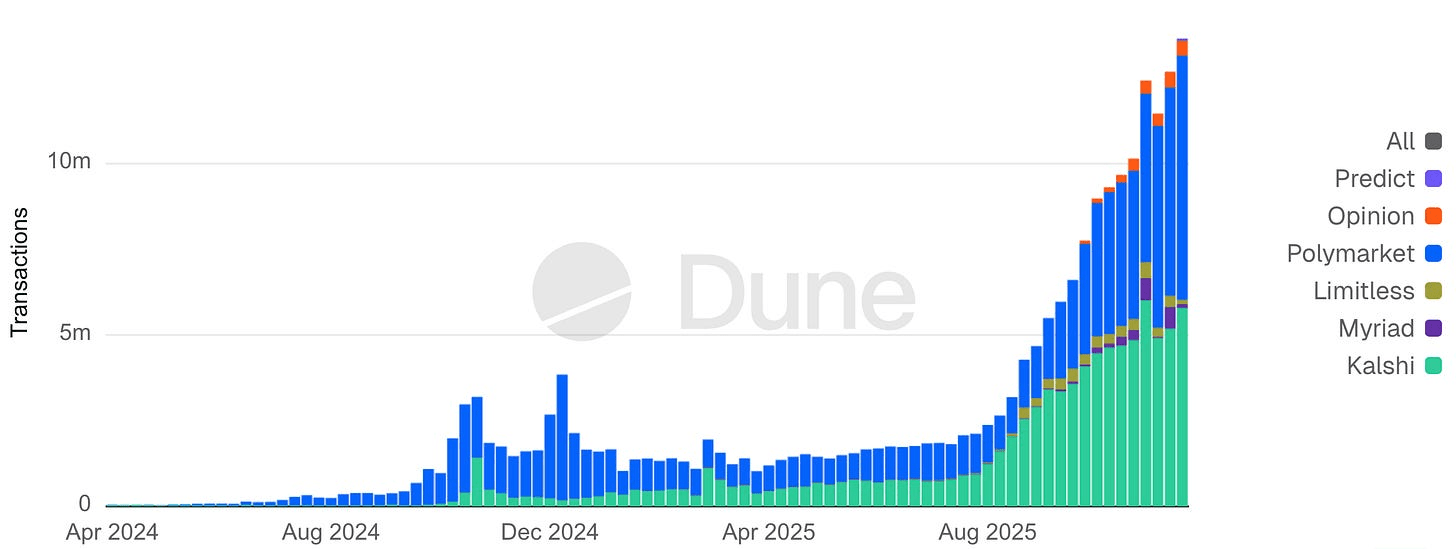
Weekly Prediction Market Transactions
Global comparable cases
In regions outside the U.S., mature betting platforms and newer licensing regimes indicate that under gambling regulation, event-type markets can achieve liquidity, but their economics and product boundaries are significantly constrained. The UK's Betfair Exchange has demonstrated that market depth can be formed within a gambling license framework, although strict consumer protection rules limit profitability. In Asian markets, betting is mostly undertaken by state monopolies or offshore platforms, reflecting strong latent demand but long-term challenges of enforcement and fairness. Latin America is moving towards formalization: Brazil opened its regulated gambling market in January 2025, attempting to convert long-existing grey areas into taxable, regulated activities.
The overall trend across regions is consistent: regulators are closing loopholes. Lotteries that rely on 'free tokens + prize mechanisms' and social casino models have been restricted or banned in multiple jurisdictions, significantly raising the compliance threshold for any products that skirt the edges of gambling. The global direction is stricter regulation, not indulgence in grey areas.
On-chain platforms vs compliance
Decentralized prediction markets once exchanged faster, global access for compliance deficiencies. Take the crypto platform Polymarket as an example: it was fined $1.4 million by the Commodity Futures Trading Commission (CFTC) in January 2022 for unregistered event swaps and was forced to implement geographical restrictions on U.S. users. Subsequently, Polymarket made a pivot: strengthening internal control (introducing former CFTC advisors) and acquiring a licensed entity in 2025, allowing it to return to the U.S. in a testing capacity in November 2025. Its trading volume subsequently soared—reportedly reaching $3.6 billion in betting on a single election issue in 2024, with monthly transaction volume reaching $2.6 billion by the end of 2024; and in 2025 it attracted blue-chip investors at an estimated valuation of around $12 billion.
On-chain platforms rely on oracle technology for rapid market creation and settlement but face the trade-off of speed vs fairness: governance and oracle disputes may delay outcomes, and anonymity raises concerns about manipulation or insider trading. Regulators remain vigilant: even if the code is decentralized, organizers and liquidity providers may still become targets for enforcement (as seen in the Polymarket case). The challenge in 2026 will be to combine 24/7 global markets and innovative crypto instant settlement with sufficient compliance without sacrificing openness.
User behavior and transaction trends
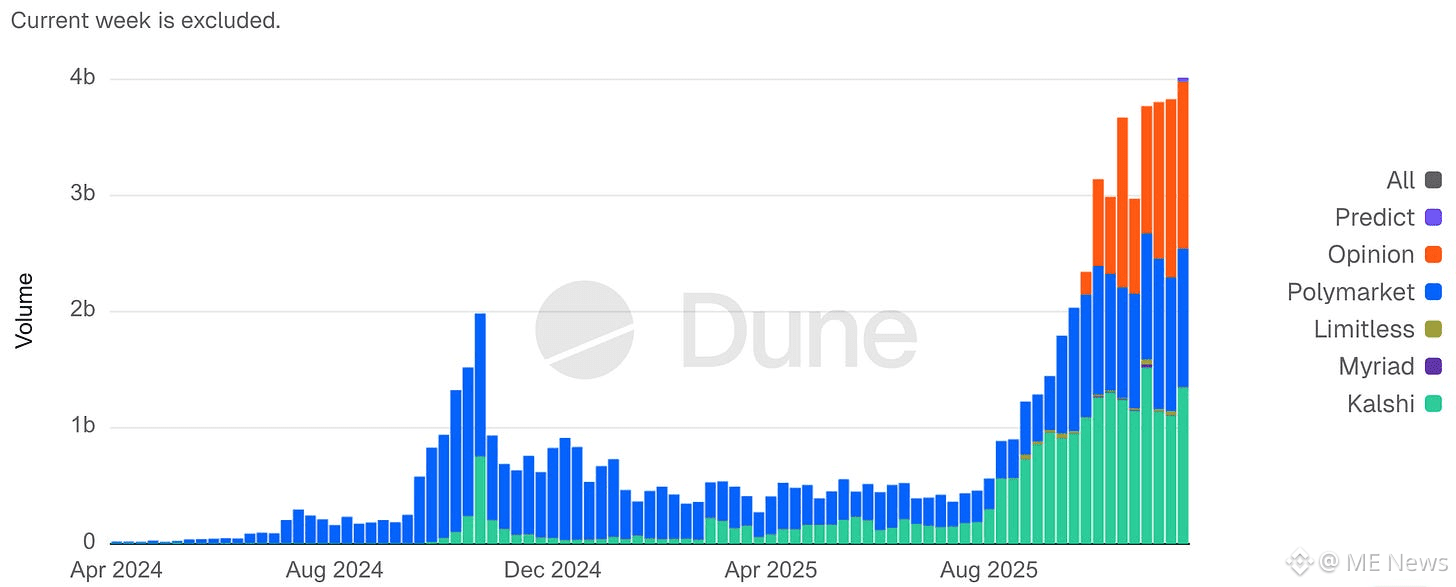
In 2025, prediction markets saw simultaneous surges in both sports and non-sports events. Industry estimates show that total nominal transaction volume expanded over tenfold compared to 2024, reaching about $13 billion/month by the end of 2025. The sports market became the main 'transaction engine', with high-frequency events generating continuous small transactions; political and macro markets served as 'capital magnets', with fewer transactions but larger individual amounts.
Structural differences are clearly visible: in Kalshi, sports contracts contribute the bulk of cumulative transaction volume, reflecting repeated participation from entertainment users; however, open interest is more concentrated in politics and economics, indicating heavier single-position funding. In Polymarket, the political market similarly dominates open interest, although trading frequency is lower. Conclusion: sports maximize turnover, while non-sports concentrate risk.
This leads to two types of participants:
Sports users: more like 'traffic traders', engaging in multiple small transactions driven by entertainment and habit;
Political/macroeconomic users: more like 'capital allocators', small in number but large in volume, seeking information advantages, hedging, or narrative influence.
The platform thus faces dual optimization: maintaining traffic participation while providing credibility and fairness for capital-driven markets.
This also explains the concentration of risk: the controversies of 2025 mainly arose in non-sports areas, including opposition from U.S. collegiate sports regulators to contracts related to student athletes. Platforms quickly delisted related contracts, indicating that governance risks rise with capital concentration and information sensitivity, rather than just with pure trading volume growth. Long-term growth depends on whether high-impact non-sports markets can operate without crossing regulatory or reputational red lines.
2026 World Cup: System-level stress test
The FIFA World Cup will be jointly hosted by the United States, Canada, and Mexico and should be seen as a full-stack stress test for event trading and compliant gambling infrastructure. Historical analogies show:
The 1994 World Cup in the United States primarily tested entities and venues; the 1996 Atlanta Olympics shifted the key path towards communication, information distribution, and emergency response. IBM's 'Info '96' focused on timing and results processing, telecoms expanded cellular networks, and Motorola deployed a large-scale intercom system; the bombing of Centennial Olympic Park on July 27 that year highlighted the importance of shifting from throughput to integrity and resilience under pressure.
The pressure points of 2026 will clearly enter the digital + financial coupling layer: events will expand to 48 teams, 104 matches, and 16 cities, concentrating attention and trading flow multiple times within about five weeks. The global betting volume for the 2022 World Cup is widely estimated to be in the hundreds of billions of dollars, with peak windows bringing extreme short-term liquidity and settlement loads.
The North American compliant track will bear a larger proportion of activity—38 U.S. states plus Washington D.C. and Puerto Rico have legalized sports betting to varying degrees, with more funds flowing through KYC, payment, and monitoring systems rather than offshore channels. App-based distribution further tightens coupling: live broadcasts, real-time contracts, deposits, and withdrawals are often completed in a single mobile session.
For event contracts/prediction markets, observable operational pressure points include: liquidity concentration and volatility during match window periods; settlement integrity (data delays, dispute resolution); product and judicial design across federal/state lines; scalability of KYC/AML/responsible gambling/withdrawals under peak demand.
The same set of regulations and technology stack will be tested again at the 2028 Los Angeles Olympics, thus the 2026 World Cup is more like a filtering event: it could trigger regulatory intervention, platform consolidation, or market exit, distinguishing infrastructure built for peak phases from sustainable, compliant scalable platforms.
Payment and settlement innovations
Stablecoins are transitioning from speculative assets to operational infrastructure. Most crypto-native prediction markets complete deposits and settlements in US dollar stablecoins, while regulated platforms are also testing similar channels. In December 2025, Visa launched a pilot in the U.S., allowing banks to use Circle's USDC for on-chain settlements 24/7, continuing a cross-border stablecoin experiment that began in 2023. In event-driven markets, stablecoins (where permitted) provide advantages in instant access, global coverage, and matching settlement periods with continuous trading hours.
In practice, stablecoins are more like settlement middleware: users treat them as faster deposit and withdrawal tools; operators benefit from lower failure rates, improved liquidity management, and near-instant settlements. Thus, stablecoin policies have a second-order impact on prediction markets: restricting stablecoin channels increases friction and slows withdrawals; clear regulations facilitate deeper integration of mainstream gambling and brokerage platforms.
But there are also resistances. Christine Lagarde warned in 2025 about the monetary stability risks of private stablecoins and reiterated support for a central bank digital euro; the European Central Bank also pointed out in its November 2025 financial stability assessment that the expansion of stablecoins could weaken banks' funding sources and disrupt policy transmission. A more likely scenario in 2026 is gradual integration: more betting platforms accepting stablecoin deposits, payment institutions bridging cards to crypto, while strengthening license, reserve auditing, and disclosure, rather than fully endorsing native crypto payment tracks.
Macroeconomic liquidity backdrop
Evaluating the prosperity of 2025 requires skepticism: loose funding will amplify speculation. The Federal Reserve's shift at the end of 2025 to end quantitative tightening may slightly improve liquidity in 2026, impacting risk appetite more than the direction of adoption. For prediction markets, liquidity affects the intensity of participation: ample funds → amplified transactions; tightening → marginal speculation cools.
However, the growth of 2025 occurs in a high-interest environment, indicating that prediction markets are not primarily driven by liquidity. A more reasonable framework is to view macro liquidity as an accelerator rather than an engine. Long-term factors—mainstream distribution of brokerage/gambling, product simplification, and increased cultural acceptance—better explain baseline adoption. Monetary conditions influence the amplitude but do not determine whether it occurs.
'Missing elements': Super App distribution and moat
The key suspense lies in: who controls the user interface for integrated trading/gambling?
Consensus is forming: distribution is king, and the real moat lies in super app-like user relationships.
This prompted intensive collaboration: exchanges want retail users (e.g., CME Group's cooperation with FanDuel/DraftKings), and consumer platforms want differentiated content (e.g., Robinhood's partnership with Kalshi, DraftKings' acquisition of a small CFTC exchange).
The model is akin to comprehensive brokerage: stocks, options, crypto, and event contracts are presented side by side, allowing users to stay on the same platform.
Prediction markets are exceptionally sensitive to liquidity and trust: thin markets fail quickly, while depth compounds returns. Platforms with existing users, low customer acquisition costs, and ready KYC and funding channels naturally outperform independent venues that need to build depth from scratch. Therefore, it resembles options trading more than social networks: depth and reliability trump novelty. This is also why the 'function vs product' debate is increasingly determined by distribution rather than technology.
Robinhood's early success supports this judgment: it launched event trading to some active traders in 2025, quickly ramping up volume; ARK Invest estimates its recurring revenue at the end of the year reached $300 million. The comparison of moats is clear: independent prediction markets (innovation again) struggle against existing users. For example, FanDuel has over 12 million users and quickly established liquidity and trust in 5 states by integrating CME event contracts; DraftKings replicated a similar path in 38 states. In contrast, Kalshi and Polymarket spent years building depth from scratch and are now more actively seeking distribution partnerships (Robinhood, Underdog Fantasy, even UFC).
Possible outcomes: a few large aggregation platforms gain network effects and regulatory endorsements; smaller platforms either specialize (e.g., only doing crypto events) or get acquired. At the same time, the merger of financial technology and media super apps is approaching: PayPal and Cash App may in the future place prediction markets alongside payments and stocks; Apple, Amazon, and ESPN have explored partnerships for sports betting between 2023 and 2025, potentially evolving into broader event trading. The real 'missing element' may be the moment when tech giants fully embed prediction markets into super apps—integrating news, betting, and investment into one, forming a moat that few competitors can match.
Before this, the competition for user lock-in among exchanges, bookmakers, and brokers will continue. The key question for 2026 is: will prediction markets become a function of large financial apps or continue to exist as independent verticals? Early evidence points towards integration.
However, regulators may also remain vigilant towards super apps that seamlessly switch between investment and gambling. The ultimate winners will be the platforms that can persuade both users and regulators—whose moats come not only from technology and liquidity but also from compliance, trust, and experience.
Opinion Trade (by Opinion Labs): An on-chain challenger with a macro focus
Opinion Trade (launched by Opinion Labs) positions itself as a 'macro-first' on-chain prediction trading platform, with a market form closer to dashboards for interest rates and commodities rather than betting products dominated by entertainment events. The platform went live on the BNB Chain on October 24, 2025, and as of November 17, 2025, its cumulative nominal transaction volume exceeded $3.1 billion, with an average daily nominal transaction volume of about $132.5 million in the early stages.
During the period from November 11 to 17, the platform's weekly nominal transaction volume was approximately $1.5 billion, ranking among the leading prediction market platforms; as of November 17, its open contract size reached $60.9 million, still lagging behind Kalshi and Polymarket at that time.
At the infrastructure level, Opinion Labs announced a partnership with Brevis in December 2025 to introduce zero-knowledge proof verification mechanisms into settlement processes, aiming to reduce the trust gap in determining market outcomes. The company also disclosed completing a $5 million seed round, led by YZi Labs (formerly Binance Labs), with other investors participating. This not only provided financial support but also strategically connected closely with the BNB ecosystem.
Additionally, the platform's explicit geographical restrictions on users in the U.S. and other restricted jurisdictions highlight a core trade-off facing on-chain prediction markets in 2025–2026: how to achieve rapid global liquidity aggregation within the constraints of regulatory boundaries.
Consumer-grade prediction markets as a distribution channel for 'ICO 2.0'
Sport.Fun (formerly Football.Fun) provides a concrete case of how consumer-grade prediction markets can evolve into a new generation of token distribution infrastructure. This emerging 'ICO 2.0' model is directly embedded within consumer-grade applications that generate real revenue. Sport.Fun launched on Base in August 2025, initially focusing on event trading similar to fantasy football, then expanding into NFL-related markets.
By the end of 2025, Sport.Fun disclosed that its cumulative trading volume exceeded $90 million, with platform revenue surpassing $10 million, indicating that the product had validated a clear product-market fit before any public token issuance.
The company completed a $2 million seed funding round led by 6th Man Ventures, with Zee Prime Capital, Sfermion, and Devmons participating. This investor structure reflects a growing market interest in consumer-facing crypto applications—these projects combine financial primitives with entertaining participation methods, rather than merely betting on underlying infrastructure. More importantly, this round of funding was invested only after user activity and monetization capabilities had been validated, overturning the traditional sequence of 'selling tokens first, finding users later' seen in earlier ICO cycles.
The public token issuance of Sport.Fun further confirms this shift.
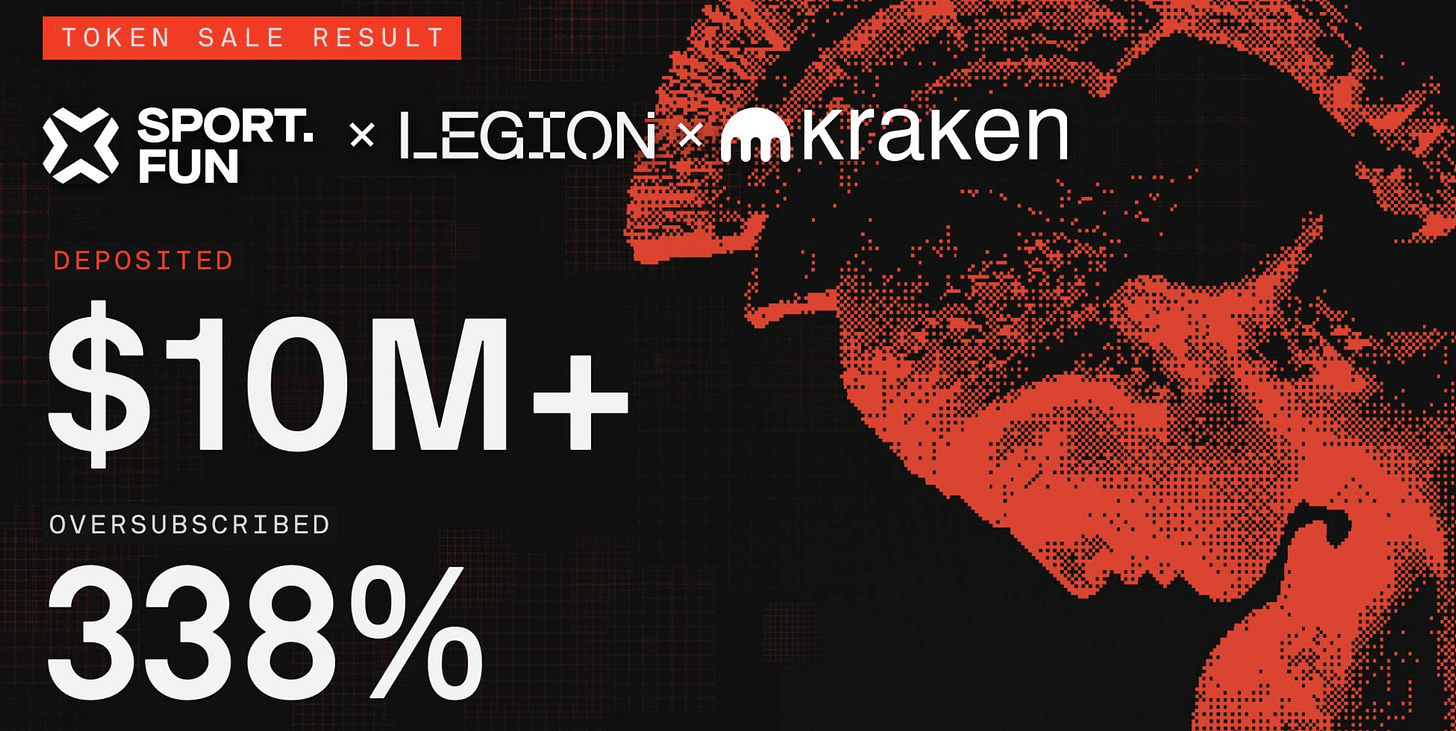
$FUN's public offering will take place from December 16 to 18, 2025, through the Kraken Launch platform and will be completed via a contribution and merit-based Legion distribution path. This offering attracted over 4,600 participants, with total subscription amounts exceeding $10 million; the average participation size per wallet is about $2,200. Demand exceeded the soft cap of $3 million by approximately 330%.
Ultimately raising $4.5 million, the token was priced at $0.06, corresponding to a fully diluted valuation (FDV) of $60 million; after exercising the greenshoe mechanism, a total of 75 million tokens were sold.
The design of the token economic model aims to balance liquidity with stability post-launch.
According to the arrangement, 50% of the tokens will be unlocked at the token generation event (TGE) in January 2026, with the remaining portion released linearly over six months. This structure is markedly different from the 'immediate full unlock' commonly seen in early ICO cycles, reflecting lessons learned and corrections from past experiences driven by volatility that ultimately led to price collapses. Functionally, this token issuance resembles not a purely speculative financing but rather a natural extension of an existing consumer-grade market—allowing users who are already actively trading on the platform to effectively 'invest' in the products they are using.
Conclusion
By the end of 2025, prediction markets have transitioned from marginalized experiments to a credible, mass-market category. Their growth momentum comes from mainstream channel distribution, product simplification, and clearly visible user demand. The current core constraint is no longer 'whether it is adopted', but rather how to design within regulatory frameworks: legal characterization, settlement integrity, and cross-jurisdiction compliance determine who can achieve scalability.
The FIFA World Cup should not be simply understood as a growth narrative, but rather as a system-level stress test under peak loads—a comprehensive examination of liquidity, operational capability, and regulatory resilience. Platforms that can pass the test without triggering enforcement risks or suffering reputational damage will define the next stage of industry consolidation; those that fail to do so will accelerate the industry's move towards higher standards, stronger regulations, and fewer but larger winners.