



Original author: Ada, Deep Tide TechFlow
The 'new stock god' Serenity, popular on X, recently shared a systematic view on Taiwan's AI industry chain. He highlighted 9 Taiwanese stocks covering CPO (Co-packaged Optics), ASIC (Application-Specific Integrated Circuits), and compound semiconductors as the three main lines. He characterized CPO as 'the biggest industry theme of the next stage.' Goldman Sachs predicts that the global Optical TAM will explode from $15 billion in 2026 to $154 billion in 2028, with CPO's share increasing from $164 million to $9.1 billion. He also made it clear: there is no bubble in Taiwan's AI industry chain, and the real risk does not lie across the strait, but rather in the capital expenditures of ultra-large-scale cloud service providers.
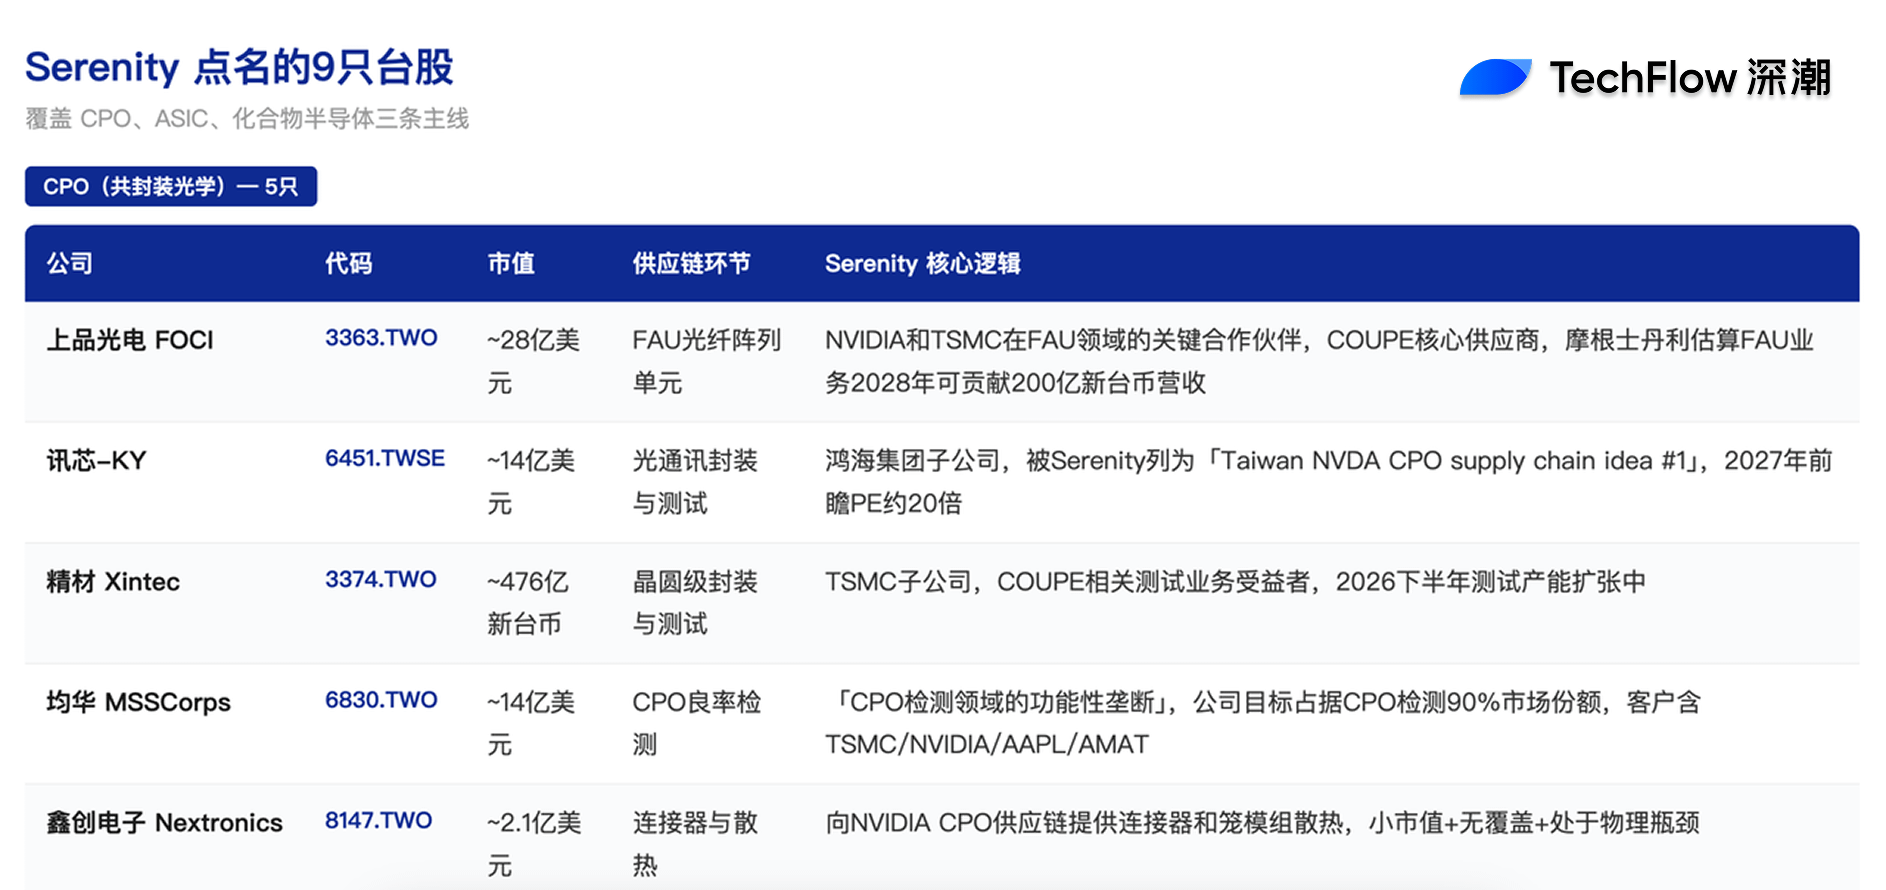
TSMC COUPE is counting down to mass production in 2026, with five Taiwanese stocks each occupying a link.
The hard time anchor supporting Serenity's CPO mainline judgment is that TSMC's COUPE (Compact Universal Photonic Engine) platform is set to enter mass production in 2026.
According to TrendForce on April 1, citing TSMC's advanced packaging integration director Hsu Shang-Yu's statements at SEMICON Taiwan, COUPE is set to enter mass production in 2026 based on SoIC technology for heterogeneous integration of electronic integrated circuits and photonic integrated circuits. Hsu also pointed out three major bottlenecks for scaling CPO: wafer-level testing, fiber array unit (FAU) integration, and high-speed optical packaging assembly. The five CPO stocks Serenity identified correspond to these three bottleneck segments and their peripheral support.
The first is FOCI (上品光电, 3363.TWO), with a market cap of about $2.8 billion. FOCI is a key partner for NVIDIA and TSMC in the FAU field and a core supplier within the COUPE architecture. Serenity stated on X that FOCI's current market cap of about $2.8 billion 'does not fully reflect its strategic position in the supply chain.' Morgan Stanley estimates that FOCI's FAU business could contribute approximately NT$20 billion in revenue by 2028, while currently it's almost zero. Hunterbrook Media and Citrini Research confirmed the 'fingerprint-level' correspondence of the three companies in 22-channel FAU through a cross-comparison of four patents as early as March, which is the strongest external evidence for FOCI's entry into the core COUPE supply chain.
The second is Shunsin Technology (讯芯-KY, 6451.TWSE), with a market cap of about $1.4 billion. Shunsin is a subsidiary of Foxconn focused on optical communication packaging and testing. Serenity once listed Shunsin on X as 'Taiwan NVDA CPO supply chain idea #1,' reasoning that 'Foxconn is NVIDIA's ODM, akin to Celestial getting a free ride to the market with MRVL.' His personal estimate is that Shunsin's forward P/E ratio will be around 20 times by 2027.
The third is Xintec (精材, 3374.TWO), with a market cap of about NT$47.6 billion. Xintec is a wafer-level packaging and testing subsidiary of TSMC, chaired by CH Chen, specializing in wafer-level chip size packaging and wafer testing. According to a DIGITIMES report on May 29, 2026, Xintec is preparing to expand capacity for testing business in the second half of 2026. Serenity recently categorized Xintec as a 'beneficiary of COUPE-related testing businesses.'
The fourth is MSSCorps (均华, 6830.TWO), with a market cap of about $1.4 billion. Serenity clearly stated on X that he built a position in MSSCorps and made a strong judgment: 'This looks like a functional monopoly in the CPO testing field. The market may be confusing it with the material/failure analysis oligopolies of MA-tek and iST.' He then cited MSSCorps' own statement, 'The company's goal is to capture 90% of the CPO testing market share' as further confirmation. MSSCorps' client mapping includes TSMC, NVIDIA, AAPL, AMAT, among others. In the three major CPO bottlenecks pointed out by TSMC, 'wafer-level testing' is the segment where MSSCorps directly positions itself.
The fifth is Nextronics (鑫创电子, 8147.TWO), with a market cap of about $210 million. Serenity's rationale for building a position in Nextronics is its provision of 'CPO connectors and Cage Thermal Modules' to NVIDIA's CPO supply chain. Nextronics is the smallest in market cap among the five CPO stocks in Taiwan, matching Serenity's typical profile of 'small cap + no coverage + facing physical bottlenecks.'
The five Taiwanese stocks, sorted by supply chain segments, are: FAU access (FOCI), optical communication packaging testing (Shunsin, Xintec), yield testing (MSSCorps), connectors and thermal management (Nextronics). The entire link is highly concentrated on downstream customers in NVIDIA and TSMC.
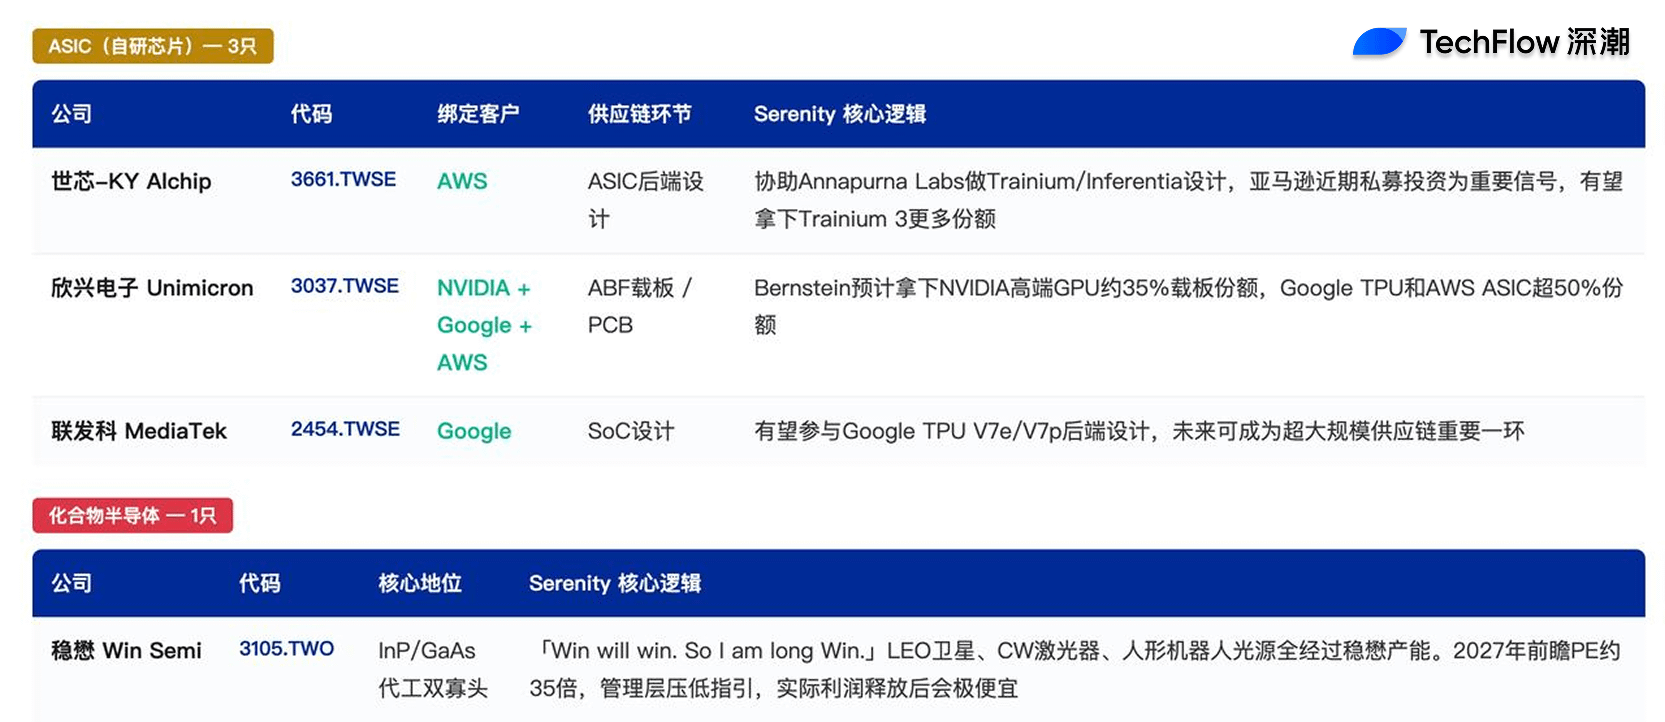
Three ASIC foundries are tied to the self-developed chips of three major Hyperscalers.
Beyond NVIDIA GPUs, the continuous ramp-up of self-developed ASICs from mega cloud service providers like AWS Trainium, Google TPU, and Microsoft Maia forms the second main line of Serenity's Taiwanese stock list.
Alchip (世芯-KY, 3661.TWSE) is the most representative target in this line. Established in 2003 and headquartered in Taipei, Alchip specializes in the design and manufacturing of advanced CMOS ASICs. According to industry chain data compiled by Global Tech Research, Alchip primarily assists Amazon's Annapurna Labs with back-end design for AWS Trainium and Inferentia series chips, with current projects including Trainium 1 and Inferentia 2. Serenity recently indicated that Alchip is expected to gain more market share in the design portion of AWS Trainium 3, particularly as Amazon's recent private investment in Alchip has been interpreted by the market as an important signal. Alchip's collaboration with Ayar Labs in the CPO field also represents further expansion of its potential market space.
Unimicron (欣兴电子, 3037.TWSE) is an ASIC beneficiary from the perspective of ABF substrates and PCBs. According to Gotrade News citing Bernstein's research report on May 4, Unimicron is expected to capture about 35% of the ABF substrate share for NVIDIA's high-end GPUs, as well as over 50% of the shares for ASIC chips like Google TPU and AWS Trainium. Bernstein lists TSMC and Unimicron as the two most representative Taiwanese stocks in the AI Capex cycle in the Asian market. Unimicron's revenue in Q1 2026 grew by 8% quarter-over-quarter, with a gross margin of 18%.
MediaTek (联发科, 2454.TWSE)'s collaboration news with Google TPU has been widely circulated in the market. According to Global Tech Research analysis, MediaTek is expected to participate in back-end design support for Google TPU V7e/V7p in the future. Serenity recently stated that although this positive news has partially reflected in the stock price, he believes that MediaTek's future ASIC business growth is still worth continuous attention. In the coming years, MediaTek has the opportunity to become a crucial part of the mega supply chain for large US cloud providers.
Three Taiwanese foundries are bound to the core segments of self-developed chips from mega cloud service providers from three different dimensions: design services, substrate packaging, and SoC design.
Win: The undervalued dual oligopoly of InP/GaAs.
Serenity's most steadfast and direct position in Taiwan stocks is in Win Semiconductor (稳懋, 3105.TWO).
Win Semiconductor (稳懋) is one of the global leaders in compound semiconductor wafer foundry, alongside GlobalFoundries, serving as a dual oligopoly for InP and GaAs foundry. The market's traditional impression of Win comes from its relationship with SpaceX's Starlink and Broadcom (AVGO) supply chains.
Serenity recently stated on X: 'Win will win. So I am long Win.' Serenity's core judgment is that Win is one of the dual oligopolies for InP and GaAs foundry; the future LEO (Low Earth Orbit) satellites of SpaceX's Starlink, continuous wave lasers (CW laser), and the visual and radar light sources for humanoid robots will all pass through Win's foundry capacity.
He provided an estimate that Win's forward P/E ratio will be around 35 times by 2027. While this may seem pricey, he believes 'the management intends to lower the performance guidance; once actual profits are released in the future, the P/E ratio will appear extremely cheap.' Win's assistance to silicon photonics companies in expanding laser production capacity is seen by Serenity as a future core growth engine, and this part has yet to be fully priced in by the market.
InP is the segment where Serenity first built a position in the US stock market with its 'Strait of Hormuz' target AXTI; he likens InP substrates to 'the oil of the future AI optical communication era.' Win's position in the Taiwan stock market is as a downstream foundry node in this supply chain.
Serenity hasn't mentioned, but it's a necessary element in the full picture: upstream materials, energy, and liquid cooling.
The nine Taiwanese stocks identified by Serenity are concentrated in the midstream of CPO and ASIC. For the overall landscape of Taiwan's AI supply chain, upstream materials and downstream energy/liquid cooling sectors are also indispensable. This part has not been directly covered by Serenity in public statements, but it cannot be omitted for a complete understanding of Taiwan's AI supply chain.
At the upstream materials end, TSMC itself (台积电, 2330.TWSE) is the central node of the entire picture. According to Bernstein's prediction, TSMC's earnings growth is expected to be around 40% in 2026, with a compound growth rate of about 20% for 2027-2028. The company has locked in its 2026 capital expenditure guidance at a high-end range of $52-56 billion. In the upstream transmission chain of AI Capex, TSMC acts both as an amplifier and a throttle; its capital expenditure direction directly determines the order rhythm for downstream packaging, substrates, testing, connectors, and all Taiwanese stocks.
On the energy and liquid cooling front, Taiwan's AI data centers are facing substantial power supply pressures. According to Reccessary on December 2025, citing the statement of Taipower's system planning director Yi Xu-Quan, global critical grid equipment such as transformers and gas turbines are in short supply, with gas turbine delivery times extending from 2-3 years to 7-8 years, and prices doubling, 'the speed of grid construction simply cannot keep up.' This supply-side bottleneck has created structural opportunities for three key Taiwanese stocks.
Firstly, Delta Electronics (台达电, 2308.TWSE) as a leader in power management and liquid cooling integration solutions has penetrated both the white space (IT computation) and gray space (power cooling) of AI data centers. Secondly, AVC (奇鋐, 3017.TWSE) is a global leader in thermal solutions, covering full-stack technologies for cold plate liquid cooling and immersion cooling. Lastly, Auras Technology (双鸿, 3324.TWSE) focuses on the manufacturing of liquid cooling modules and is a first-tier supplier for NVIDIA. According to Goldman Sachs, the global server cooling market size is expected to grow 111%, 77%, and 26% from 2025 to 2027, reaching $17.6 billion in 2027. This growth curve is synchronized with the growth curve of CPO during the AI capital expenditure cycle.
The real risk isn't across the strait, but with the capital expenditures of mega cloud service providers.
Serenity's take on the overall risk of the Taiwan stock market's AI supply chain is at odds with the mainstream narrative.
He recently stated that there is currently no bubble in Taiwan's AI supply chain; many Taiwanese companies' valuations remain lower than their counterparts in the US Nasdaq. Geopolitical risks have been exaggerated by the market because Taiwan is already an integral part of the global tech supply chain. 'No country would choose to engage in a zero-sum game that disrupts massive supply chains.' Looking long-term over 7-10 years, the US is establishing domestic supply chains through companies like Intel, but there are no particularly significant systemic risks in the next 2-3 years.
He pointed out that the real risk worth tracking is the capital expenditures of mega cloud service providers. The continuous expansion of investments from large cloud providers like Microsoft, Amazon, Google, Meta, and Oracle is the core driver of the current prosperity in the AI industry. 'As long as these companies continue to increase their AI infrastructure building, the Taiwanese supply chain will continue to benefit; however, if mega cloud service providers start cutting capital expenditures, Taiwan's AI supply chain could face significant valuation adjustments.'
The 'stress test' for this judgment is beginning to show early signs.
The marginal changes recently observed in the market are worth tracking. On June 3, Daybreak announced its Q2 FY2026 performance, with a guidance of $16 billion in AI chip revenue for Q3 FY2026, below the consensus expectation of $17.2 billion by about $1.2 billion; Broadcom's CEO Chen Fu-Yang maintained the full-year AI semiconductor revenue guidance of $56 billion unchanged during the earnings call, with no upward adjustment. The market interpreted the 'no upward adjustment' as negative, leading to a single-day plunge of 10.26% in the Philadelphia Semiconductor Index (SOX), marking the largest single-day drop since March 2020; along with Japan and South Korea's KOSPI dropping 5.54%, KOSPI's opening on June 8 fell 8.37%, triggering a circuit breaker.
However, the key reference currently observed is that TSMC's capital expenditure for 2026 is locked in at the high-end range of $52-56 billion, with no substantial downward adjustments yet. The capital expenditure guidance of mega cloud service providers themselves is also still in an upward revision channel. Whether the 'real risk' that Serenity judges is triggered needs to be observed in the upcoming Q2 and Q3 2026 earnings reports from Microsoft, Amazon, Google, Meta, and Oracle, which is the core prerequisite for the establishment of Serenity's stock list in Taiwan and the most worth tracking marginal variable in the next quarter.