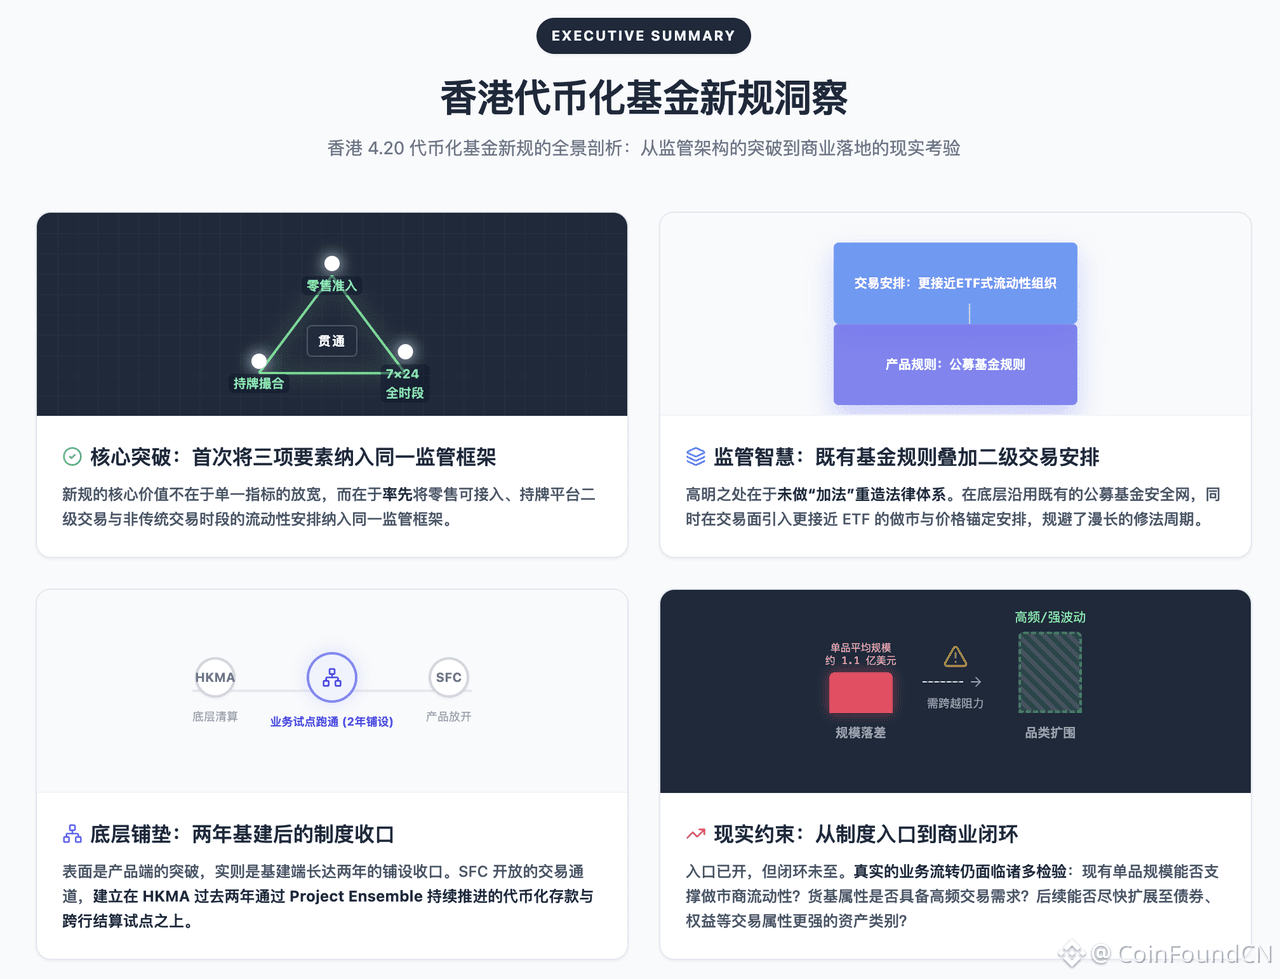
Hong Kong's new tokenized fund regulations really change not whether trading is possible, but rather the method of trading.
For the first time, it integrates retail access + secondary matching + 24/7 liquidity
into the same regulatory framework.
More crucially:
it's not about reinventing the rules, but directly applying the ETF mechanism.
This means one thing:
RWA is no longer just 'on-chain asset mapping',
but is starting to enter the 'standardized trading market'.
However, the issue is clear:
the framework is in place, but the market hasn't caught up yet.
Scale, liquidity, and asset structure
are the real variables for the next phase.
Read the original: 香港新规落地:代币化基金二级交易通道开启,产品走向ETF化
For the first time, it integrates retail access + secondary matching + 24/7 liquidity
into the same regulatory framework.
More crucially:
it's not about reinventing the rules, but directly applying the ETF mechanism.
This means one thing:
RWA is no longer just 'on-chain asset mapping',
but is starting to enter the 'standardized trading market'.
However, the issue is clear:
the framework is in place, but the market hasn't caught up yet.
Scale, liquidity, and asset structure
are the real variables for the next phase.
Read the original: 香港新规落地:代币化基金二级交易通道开启,产品走向ETF化