



Original author: KarenZ, Foresight News
On November 3, 2025, a security incident causing losses exceeding 120 million USD largely shattered the growth illusion of the long-established DeFi protocol, Balancer.
This is the largest security incident in Balancer's history. But the deeper pain is not in that astronomical figure.
Looking at the financial data attached to Balancer's latest proposal, its fundamentals are already not optimistic: the protocol's annual fees are approximately 1.65 million USD, while the DAO's estimated annual revenue is only 290,000 USD, accounting for 17.5%.
The remaining funds flowed to veBAL holders, core pools, the Balancer Alliance program, and others. The entire system appears to be a continuously operating 'money printer', but in reality, it has two sides 'leaking': on one hand, transaction fees are lost through multiple layers of splits; on the other hand, the BAL token releases an inflation of approximately 3.78 million tokens annually, which, at the current price, creates a continuous selling pressure of about 580,000 USD — it's important to note that the current fully diluted valuation (FDV) of BAL is only 11 million USD.
The annual operational budget reached $2.87 million, while the annual revenue is only $290,000, resulting in a gap of $2.58 million.
The DAO treasury (excluding BAL) has only $10.3 million left. At this speed, the treasury has less than 4 years left.
After the safety incident, Balancer's TVL has become even more dire. Balancer's TVL has fallen from $800 million to about $300 million, and has continued to decrease, currently below $160 million. It is worth noting that during Balancer's peak in 2021, its TVL exceeded $3 billion.
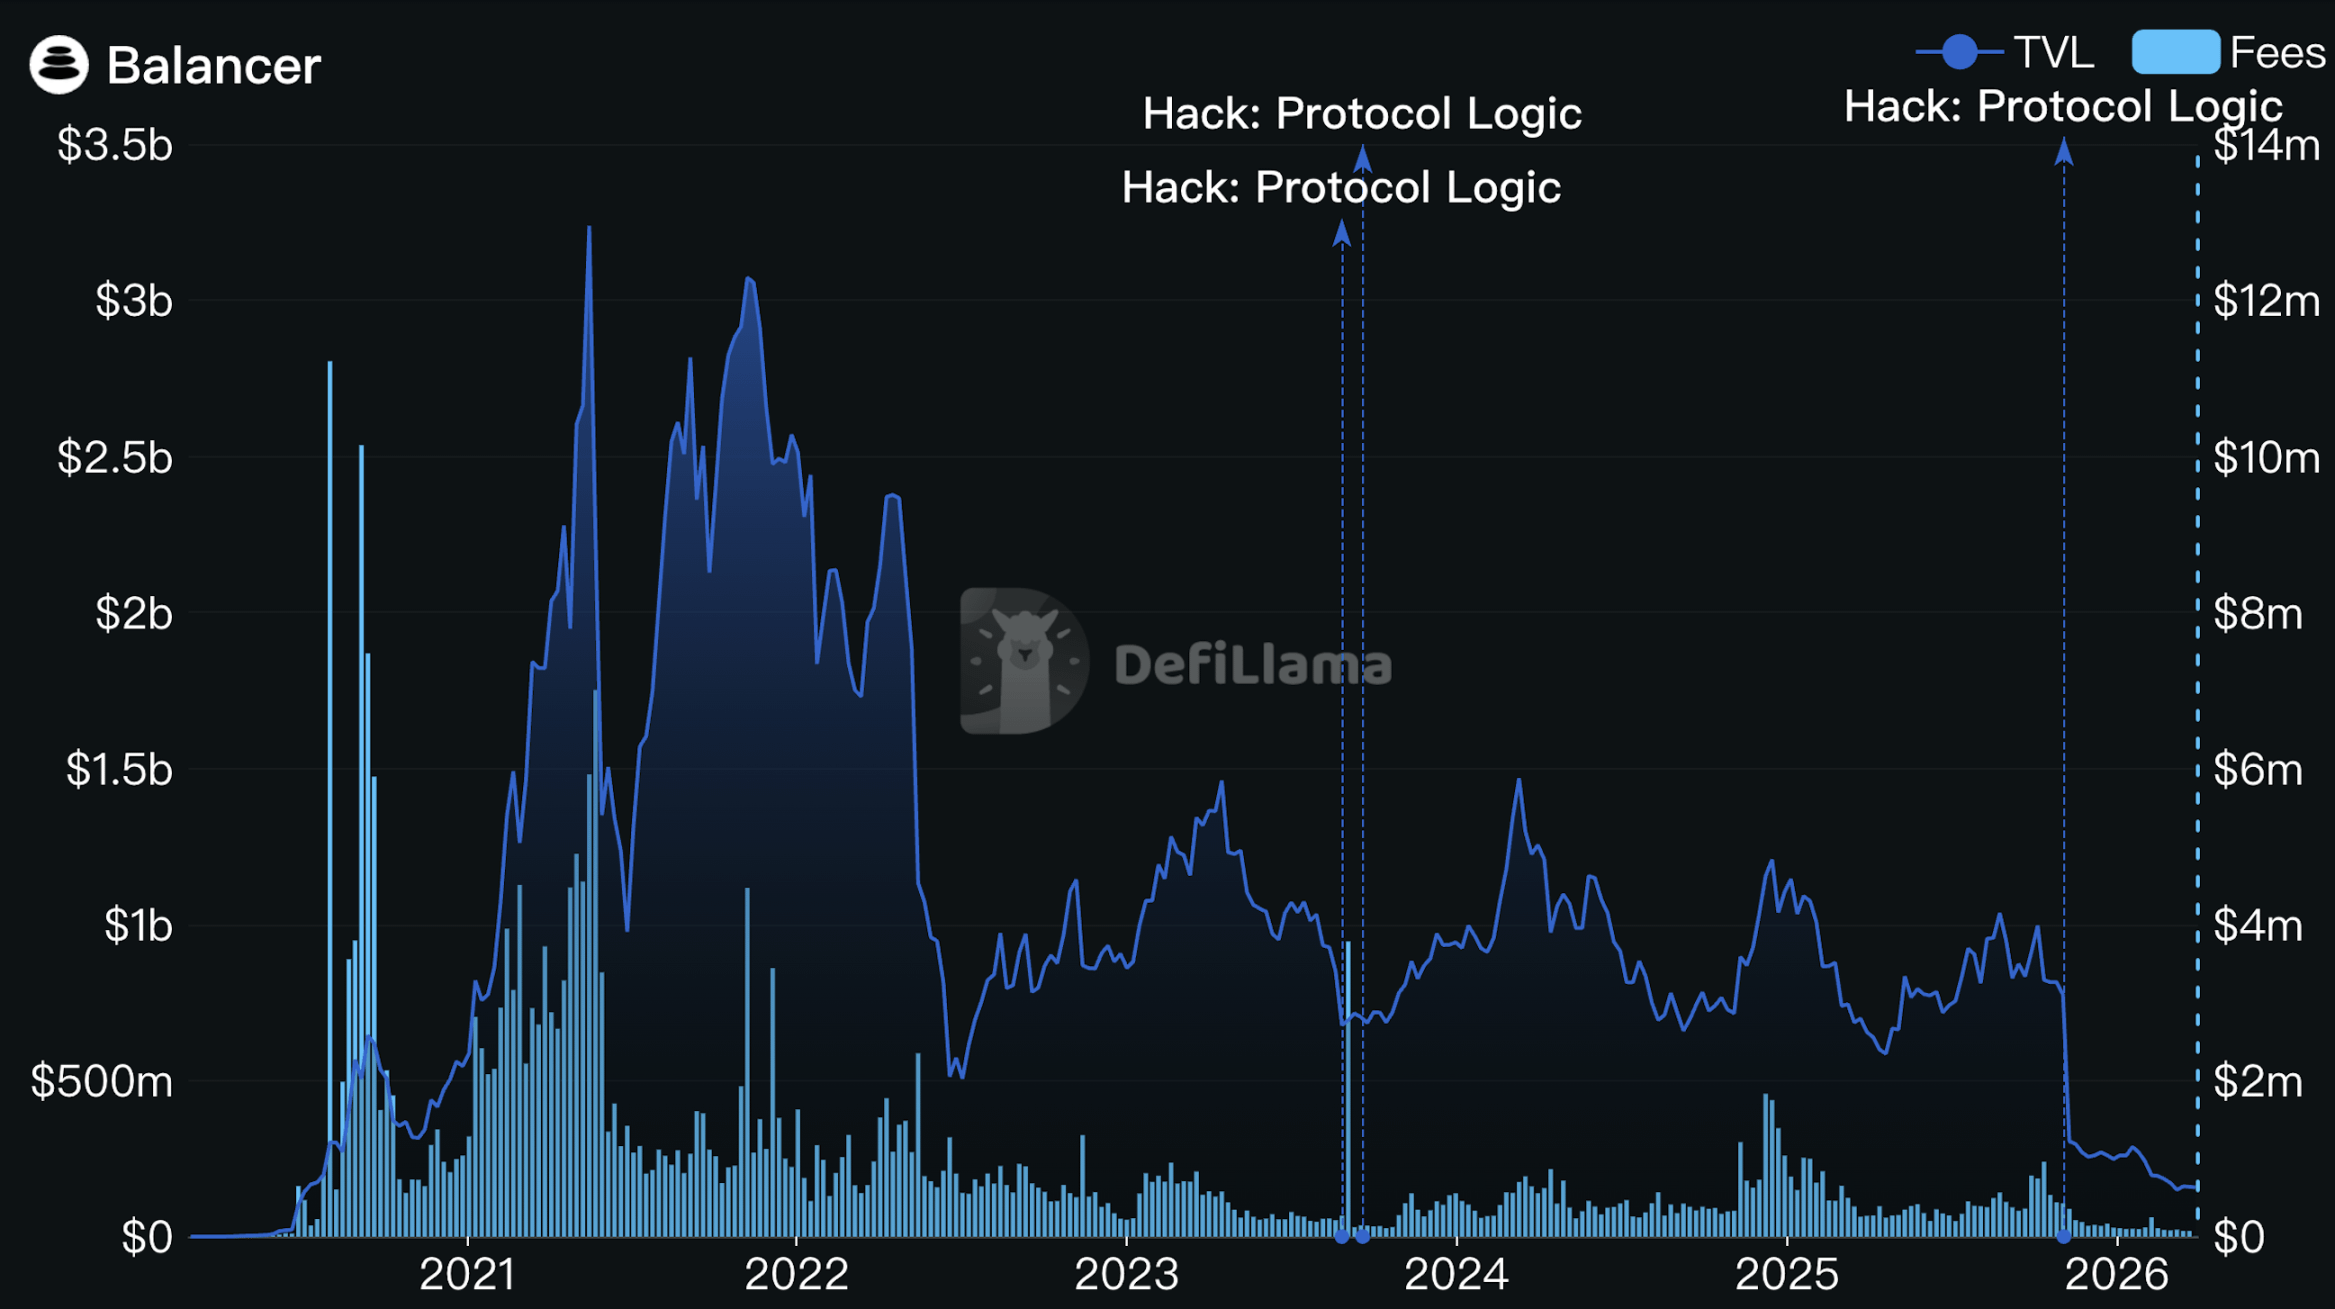
Source: DefiLlama
Balancer has officially reached a crossroads of fate. On March 23, 2026, the core team of Balancer simultaneously released two important governance proposals: a comprehensive reform of BAL token economics and a reorganization of the operational structure.
The core logic of the two documents can be summarized in one sentence: abandon the growth model driven by token releases and shift to revenue-driven sustainable operations.
Operational restructuring: the team is 'slimming down,' with an annual budget reduction of 34%.
The proposal suggests that Balancer Labs be formally dissolved, with its core technical personnel integrated as contractors into Balancer OpCo Limited, which will continue to operate as the legal agent of the DAO.
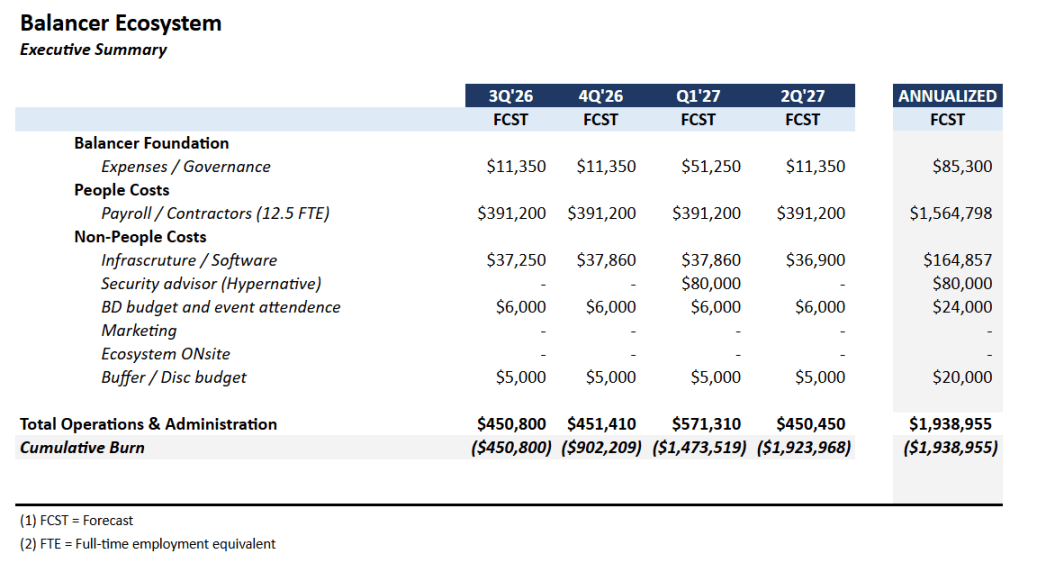
The team size will be reduced from about 25 people to 12.5 full-time equivalents (including dedicated service providers like Beets, MAXYZ, etc.), with the annual operational budget reduced from $2.87 million to $1.9 million, a 34% reduction.
The product line is also being drastically narrowed. The team will focus its resources on three commercially viable products: Boosted Pools (flagship product), reCLAMM (to be relaunched after fixing vulnerabilities and possibly renaming), and LBP (token issuance pool, opportunistic operation).
The other exploratory directions, such as ETF structured products, yield optimizers, AI-driven liquidity tools, etc., must all be advanced on the premise of "core KPI achievement."
On-chain deployment is also shrinking. Maintaining the V2 and V3 models across more than 9 chains is becoming unsustainable, and the team has clearly stated that it will retain four core chains: Ethereum, Gnosis, Arbitrum, and Base, while other deployments will be reviewed one by one based on fee income and operational costs; those that do not meet the standards will be terminated directly.
Token economics reform: rebuild rather than make minor fixes.
Stop BAL release, abolish veBAL
After the proposal is passed, Balancer will terminate BAL token incentive releases, with no transition period.
Meanwhile, the governance mechanism of veBAL will also be formally abolished. Holders will stop receiving any economic benefits after the last bi-weekly fee distribution, and the locked veBAL will become purely a governance certificate, awaiting natural expiration after the lock-up period ends.
This is a painful decision, but the underlying logic is clear: the veBAL mechanism has had a structural risk of being monopolized by oligarchs since its design. Currently, Aura Finance (the veBAL governance protocol) and large whales have already obtained a large amount of voting power, and the genuine voices of the community are becoming weaker in governance. This mechanism has not only failed to promote the healthy development of the protocol but has instead become a vehicle for a circular economy game—money from the protocol flows to middlemen through incentives, and the votes from middlemen push more incentives in their direction.
If veBAL was once an experiment for Balancer to draw on Curve's design, the team now admits: the experiment is over, and the results did not meet expectations.
In response to the termination of veBAL economic rights, Balancer announced a compensation activity of $500,000, directly distributed to veBAL holders, which is purely cash compensation.
All fees will go to the DAO treasury, reducing the V3 protocol's take.
All protocol fees, V2 exchange fees, V3 exchange fees, yield fees, LBP fees, will thereafter flow 100% into the DAO treasury, and the old multi-party split mechanism will no longer be used.
At the same time, the protocol fee share for V3 has been reduced from 50% to 25%. This means that for the same transaction, liquidity providers previously took 50%, but now they take 75%.
These two actions may seem contradictory, but the underlying logic is consistent: the former eliminates the circular economy, allowing the treasury to obtain real usable funds; the latter enhances LP attractiveness, exchanging lower platform extraction for more organic liquidity and real trading volume.
The proposal estimates that after the reform, the DAO's annual revenue could reach about $1.22 million, which is more than 4 times the current $290,000.
Those who want to exit can destroy BAL at a unit price of $0.16 to exchange for stablecoins.
The treasury will allocate 35% of its assets (currently about $3.6 million) as a special pool, not to actively buy BAL in the secondary market, but to open a 'burn for stablecoin' channel: BAL holders can actively send tokens into the contract for destruction and receive an equivalent amount of stablecoins at the NAV price (net asset value, about $0.16 each).
The window will open 12 months after the proposal is passed and will last for 12 weeks. Any unused stablecoins during this period will return to the treasury after the window closes. The design intention of the 12-month waiting period is to allow holders of veBAL to gradually participate as their holdings unlock.
As of the time of writing, the price of BAL is $0.1548, lower than the NAV price. Providing an exit at the NAV price gives those wishing to exit a more dignified option than a secondary market crash.
If this channel is fully utilized, about 22.7 million BAL will be destroyed, accounting for about 35% of the circulating supply, which is 6 times the current annual inflation emission.
Is 9 years of 'runway' enough?
If both proposals are passed, the financial model calculated by the team is as follows:
The DAO's annual revenue is approximately $1.22 million (assuming that TVL rebounds after the V3 fee reduction), annual operational expenditure is $1.9 million, buyback expenditure is about $3.6 million, plus $500,000 in veBAL compensation.
After completing the buyback and compensation, the treasury will still have about $6.2 million remaining, and the annual funding gap will narrow from about $2.6 million to $700,000, with a theoretical survival period approaching 9 years.
For a DeFi protocol, 9 years is sufficient to cross a complete industry cycle.
However, this model is built on optimistic assumptions: the reduction in the V3 protocol's take can indeed drive more organic TVL; the reduced team can truly support the protocol's daily operations, security maintenance, and other business; and the core product (especially reCLAMM) can successfully attract the market again after repairs.
If any link falls short of expectations, the 9-year survival cycle will shorten rapidly. The team has also clarified that if DAO monthly revenue falls below $60,000 for three consecutive months, a revision proposal must be submitted to the community.
For Balancer, this is an almost all-or-nothing reform. It abandons the once proud veBAL mechanism and the complex multi-party profit-sharing structure, returning to an extremely streamlined point: allowing real trading fees to drive the protocol's survival, rather than relying on newly minted tokens to maintain a false prosperity.
Whether this all-in reform can be effective ultimately depends on the market and time; we will wait for subsequent long-term observations.