


Currently, the exploration of RWA in the Crypto market mainly focuses on asset tokenization—specifically, how to map the ownership of real assets such as government bonds, stocks, or real estate onto the blockchain for more efficient settlement and holding. However, this solution, centered on efficient holding and settlement, cannot fully meet the other demand in the financial market, which is significantly larger and more active: leverage trading and risk management regarding asset price fluctuations.
Article Author: OKX
Source: MarsBit
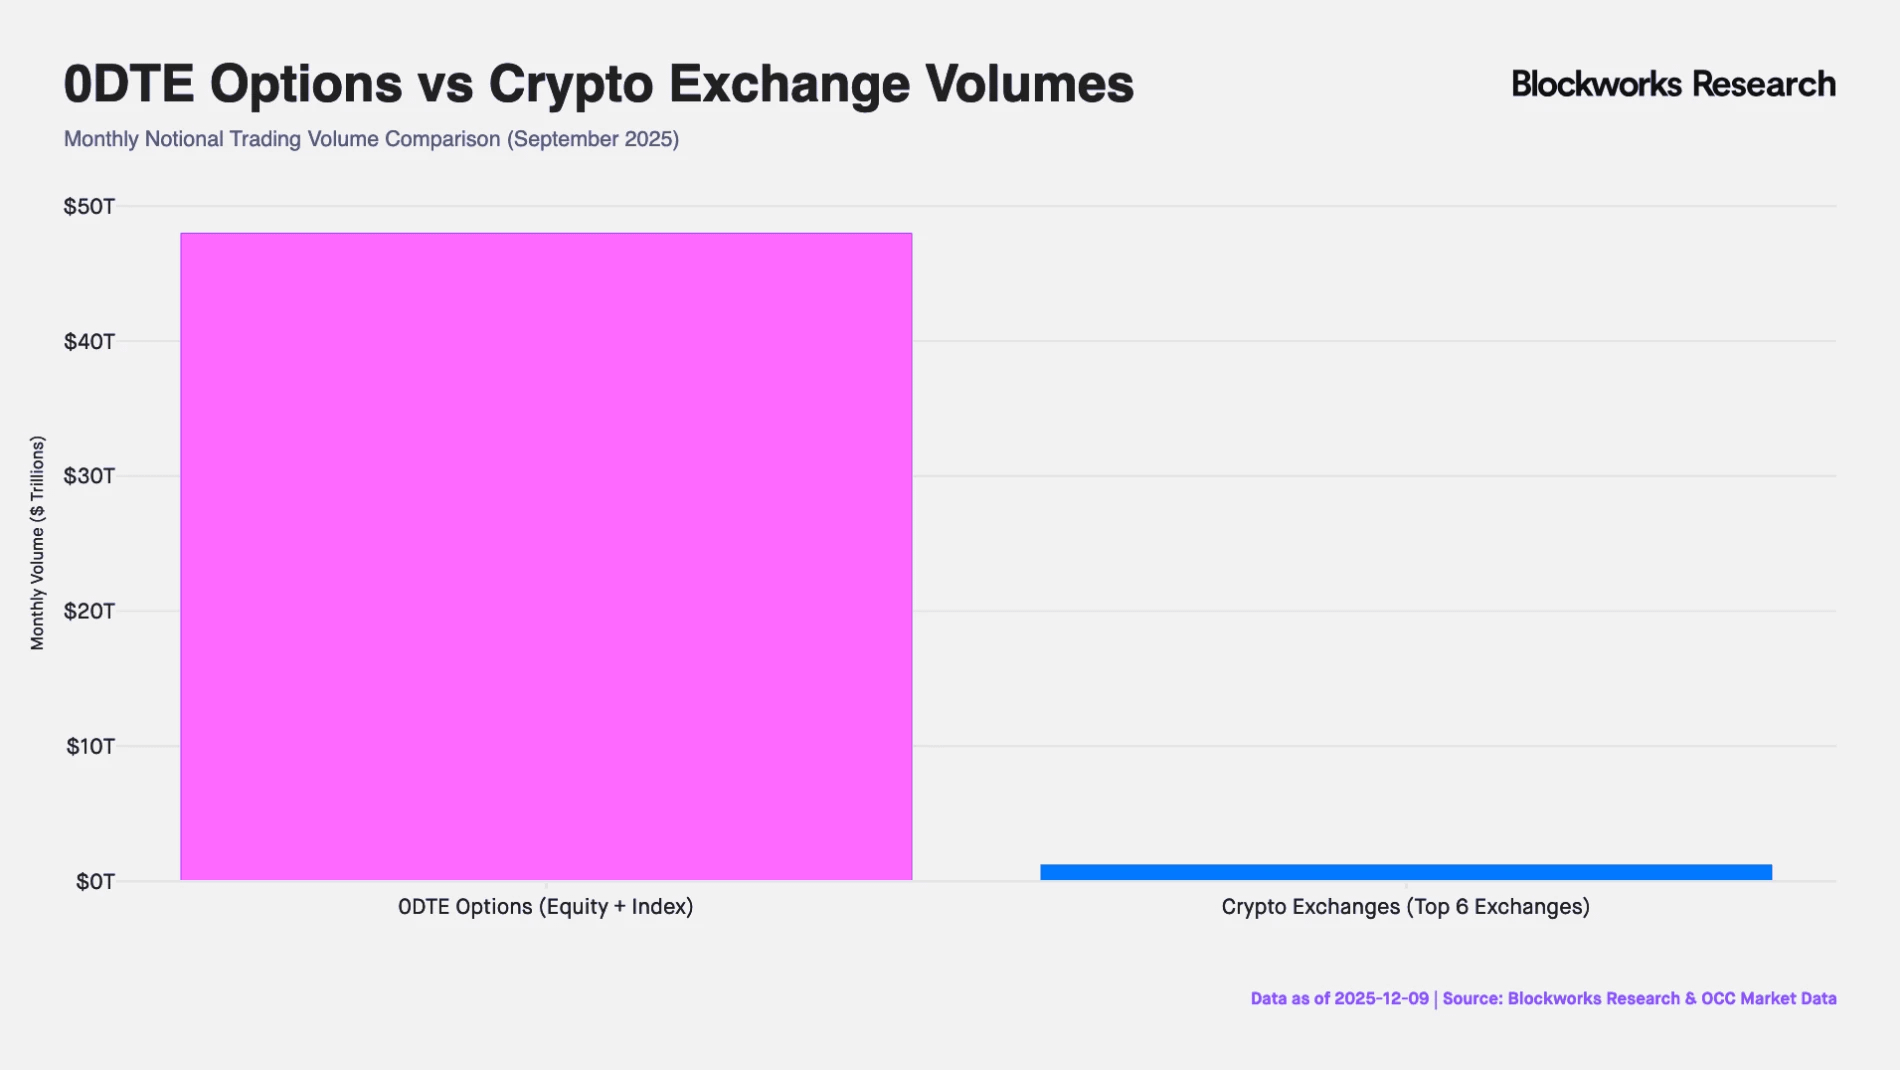
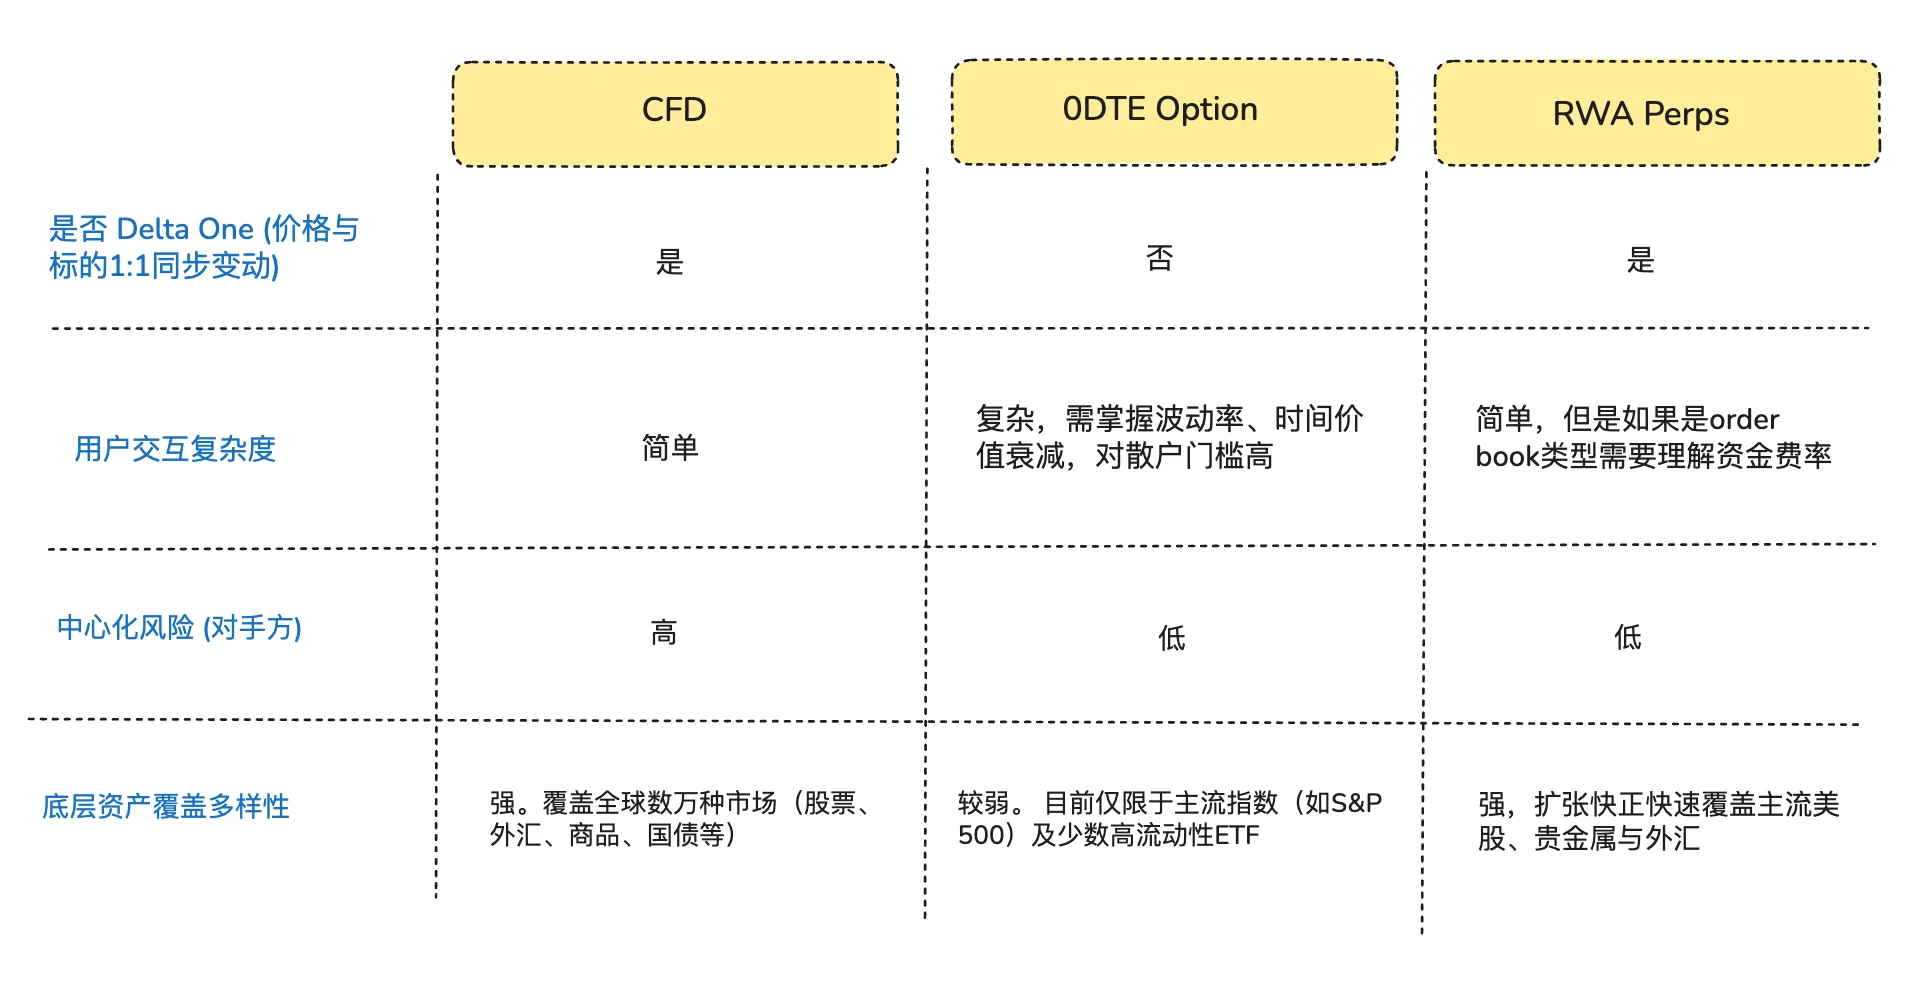
In fact, the true engine of global financial market liquidity is not the static holders of assets, but the traders seeking leveraged directional exposure. From the approximately $50 trillion nominal value of the U.S. end-of-month options market to the approximately $30 trillion monthly trading volume of the CFD (Contract for Difference) market outside the U.S., retail investors' thirst for high leverage and short-term risk exposure has never ceased. Despite the enormous trading scale, existing traditional financial instruments still struggle to meet this demand: 0DTE Option (zero-day-to-expiration option/end-of-month option) forces traders in a simple directional bet to also bear the non-linear risks of Theta (time decay) and Vega (volatility). Meanwhile, the CFD market is criticized for its opaque black-box mechanism and centralized counterparty risk.
From the perspective of purely seeking directional exposure, many traders actually desire not 'options' or 'tokenized stocks,' but a purely Delta One (linear/symmetrical yield) exposure—where the price fluctuations of assets can be simply and directly converted into investment profits and losses in a proportional manner, without any losses or deviations in between (Arthur Hayes wrote a retrospective (Adapt or Die) at the end of last year discussing the complete background of their development of crypto perpetual contracts, worth reading).
It is precisely within this structural mismatch that DeFi protocols keenly captured this market opportunity. Some DeFi entrepreneurs attempted to introduce perpetual contracts, which have undergone nearly 10 years of validation and maturation in the crypto market, into the traditional asset space. These products employ a synthetic derivative architecture, anchoring the prices of underlying assets through oracle feeds and funding rate mechanisms, providing around-the-clock leveraged trading services for stocks, commodities, and forex without the need to physically hold or deliver assets.
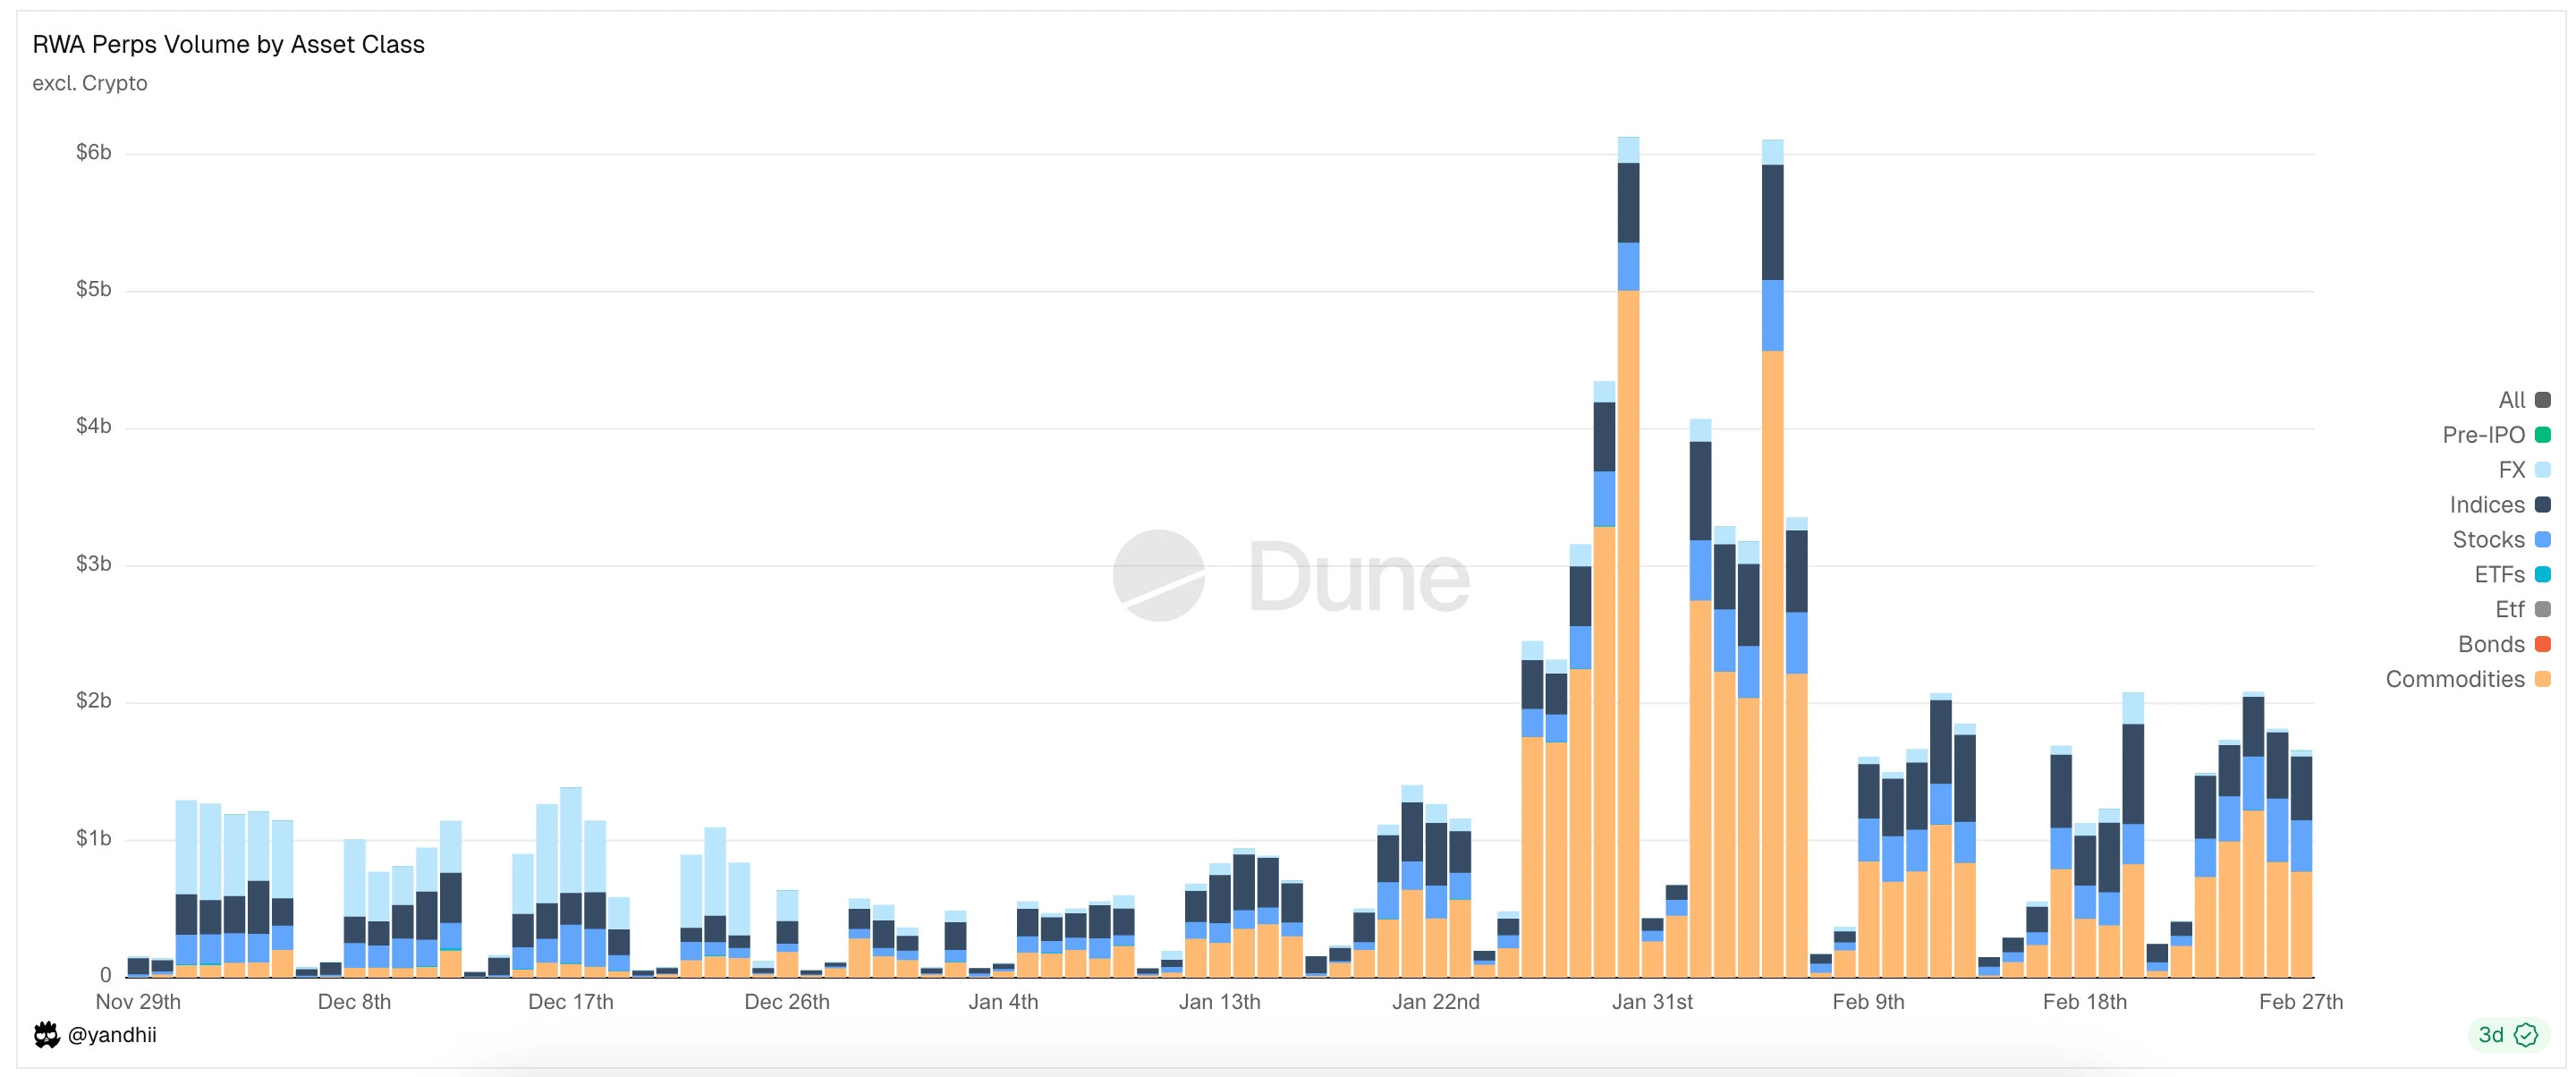
Figure: Current main trading asset types of RWA Perps Dex
1. Market Background (Opportunities for Entering the RWA Perps Market)
1.1 Market Entry 1: The U.S. 0DTE Option (End-of-Day Option) Market
Over the past 10 years, the U.S. options market has undergone profound structural changes. According to data from major options exchange Cboe Global Markets, the trading volume of end-of-day options in S&P 500 index options has surged from less than 5% in 2016 to over 60% currently, with a nominal monthly trading volume of $48 trillion (about 40 times the monthly trading volume of perpetual contracts on CEX exchanges). This data reflects not only the increase in trading frequency but also reveals a significant force in the market seeking extremely high intraday leverage exposure.
Note: 0DTE stands for 'Zero Days to Expiration,' meaning options that expire on the same day are also known as end-of-day options. Traders use them for ultra-short-term games, obtaining quick returns and avoiding overnight holding risks.
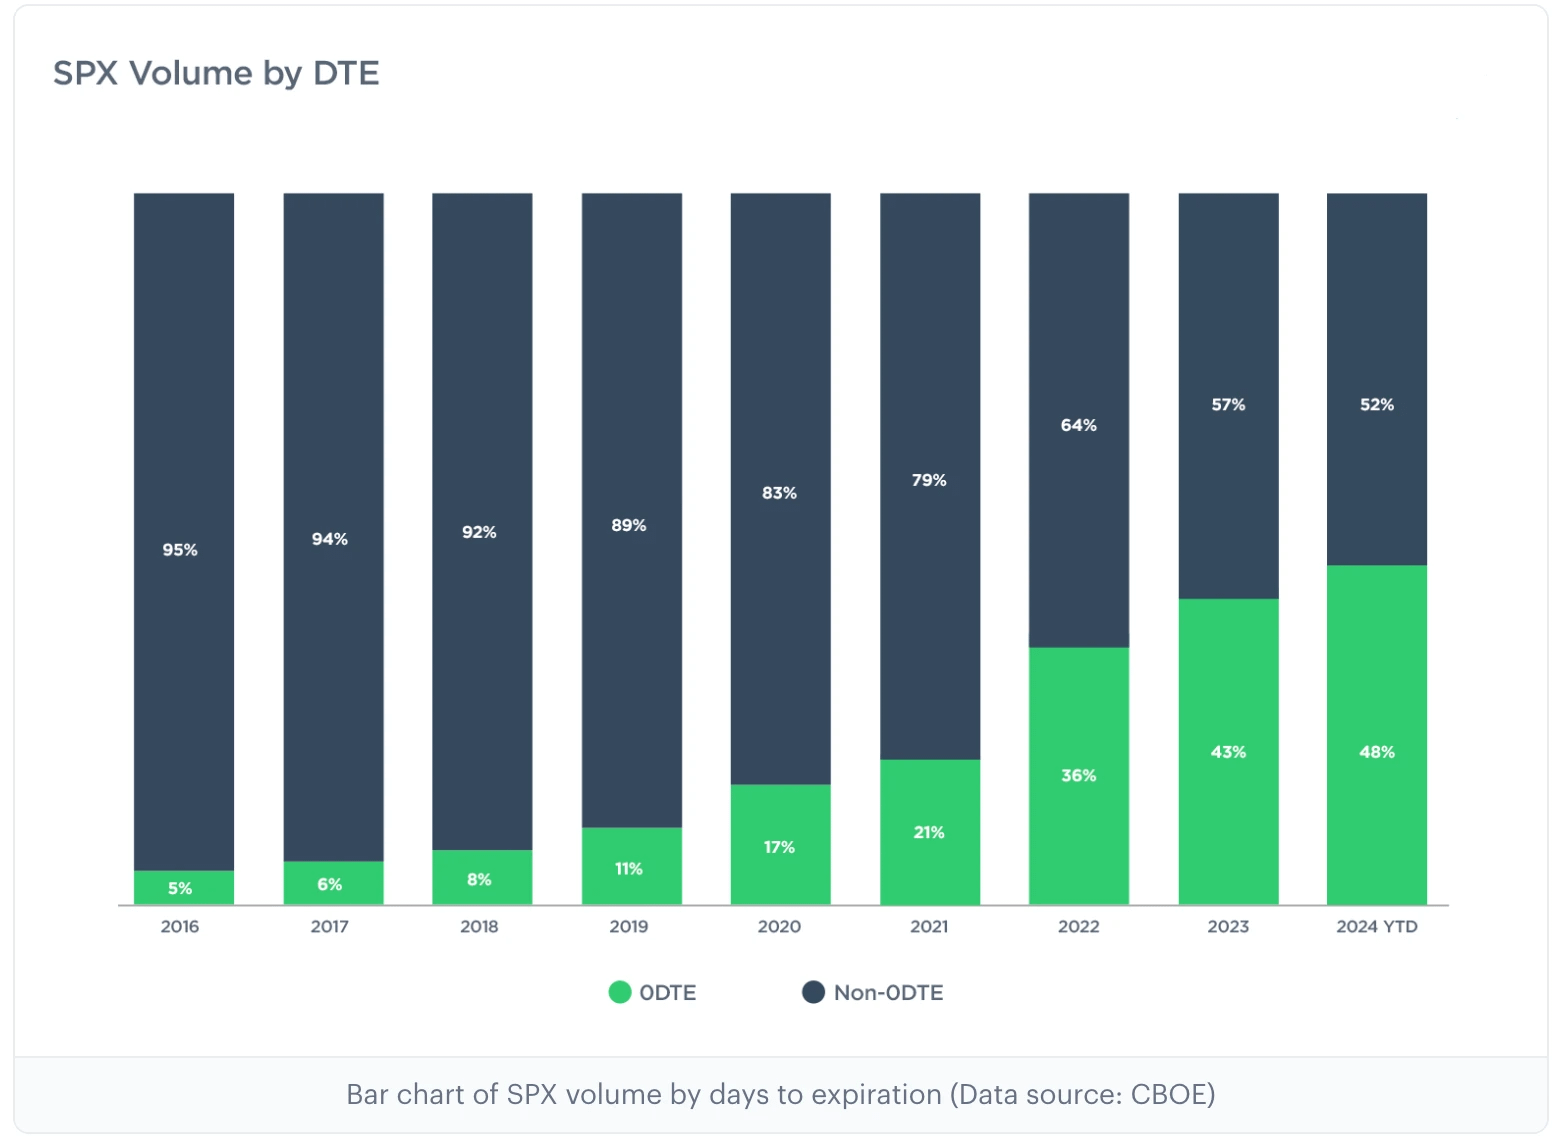
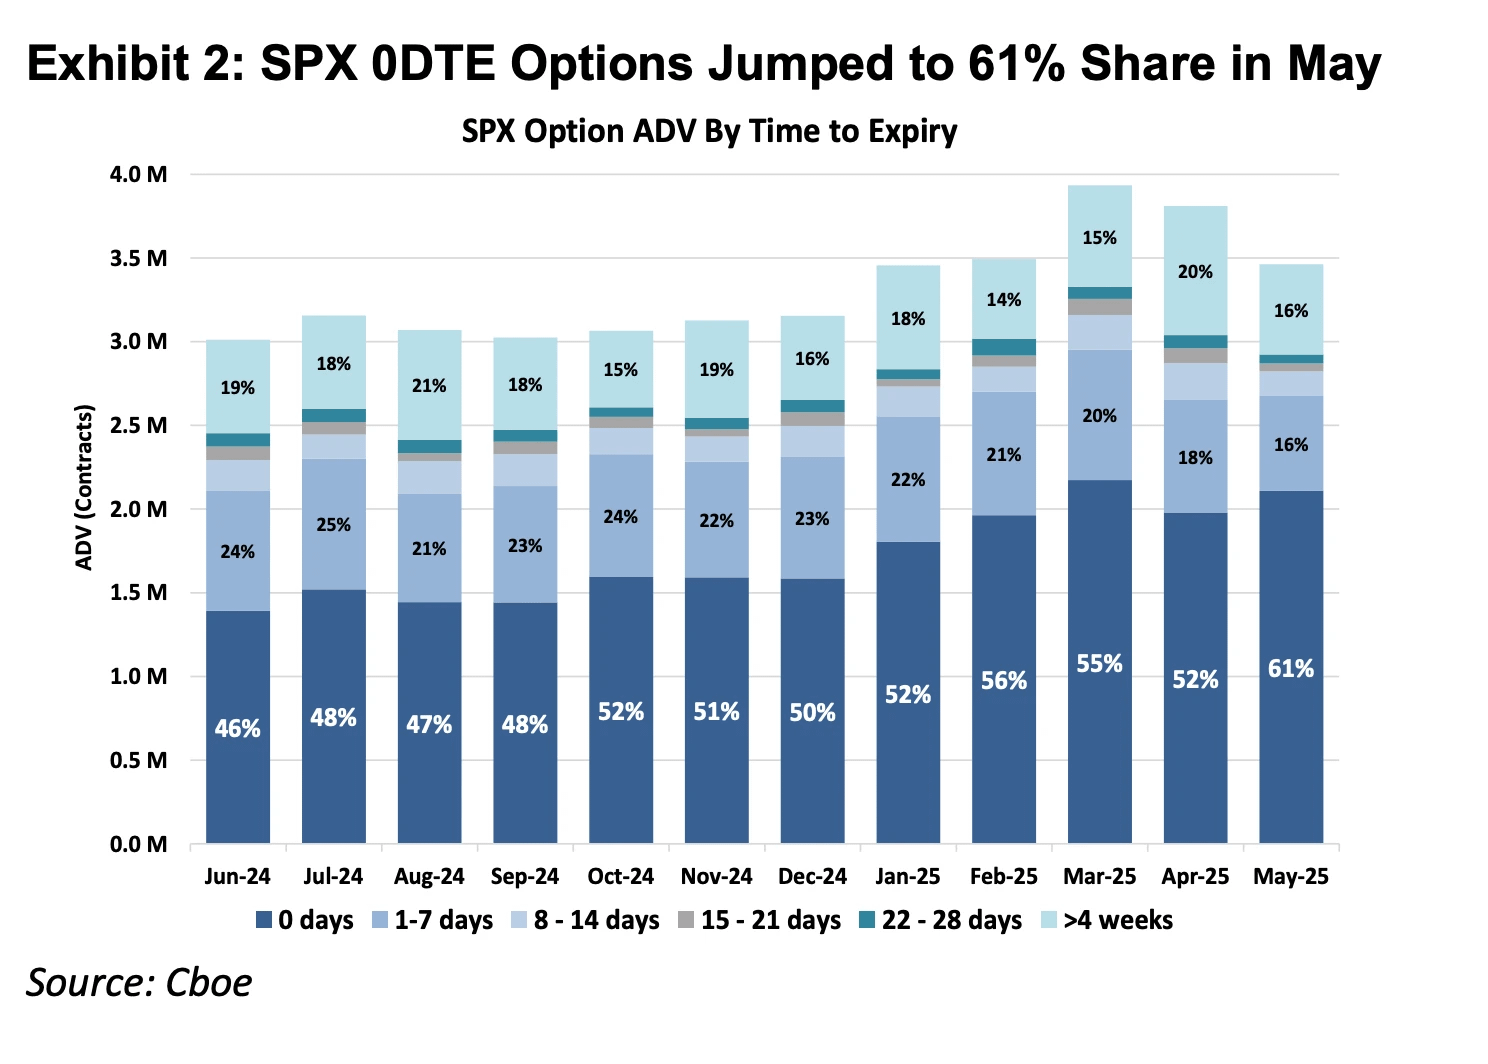
Figure: The two previous figures show the proportion of S&P 500 index options with different expiration times from 2016 to 2025. It can be seen that 0DTE Options made up only about 5% of the options market in 2016, but by 2025, their market share soared to 61%, indicating that nearly half of S&P 500 index options trading is betting on the direction for same-day short-term games.
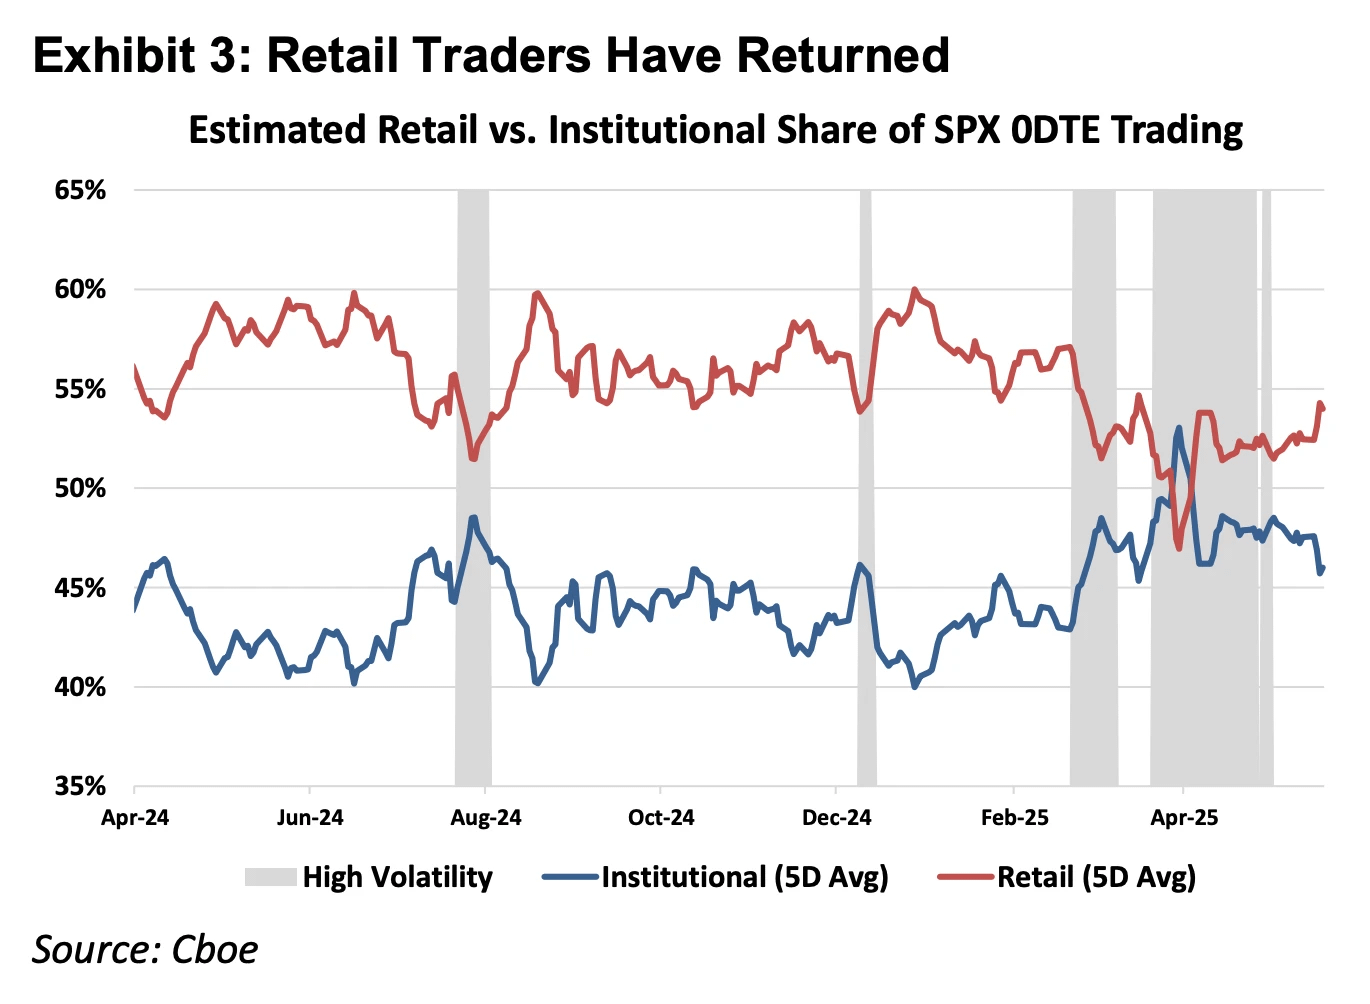
Figure: The above figure shows that retail investors are the absolute main force in the 0DTE market.
From the first principles of financial instruments, financial derivatives can be divided into Delta One products and nonlinear products. Traditional Delta One tools like stocks and futures have symmetrical risk exposures: the profits from price increases and the losses from price declines are linearly proportional in scale. However, the original intention of options design is to manage asymmetric risks.
For example, a fund manager holding a large amount of Apple Inc. stock, optimistic about the company's long-term fundamentals and reluctant to sell, may worry about short-term earnings volatility leading to a significant stock price drop. At this point, they can buy put options to provide insurance for their position. In this structure, their profit potential remains retained as the stock price rises (symmetric upside profit), but their loss scale is strictly capped at the premium already paid (asymmetric downside risk).
In order to achieve this 'separation of rights and obligations' insurance function, the cost structure of options must reflect not only the intrinsic value (Delta) that indicates direction but also the possibility of volatility (Gamma) and the time value that reflects the passage of time (Theta).
The significant growth of the 0DTE market share in recent years reveals a paradox: a large number of traders do not seek to manage asymmetric risks or engage in complex volatility trading, but rather see it as the only means of obtaining intraday directional leverage. In this case, traders are forced to pay high time value costs (Theta Decay) for an 'insurance function' they do not need. As long as the speed of the underlying asset's price increase cannot cover the decay rate of time value, even with correct directional judgment, trading will still incur losses.
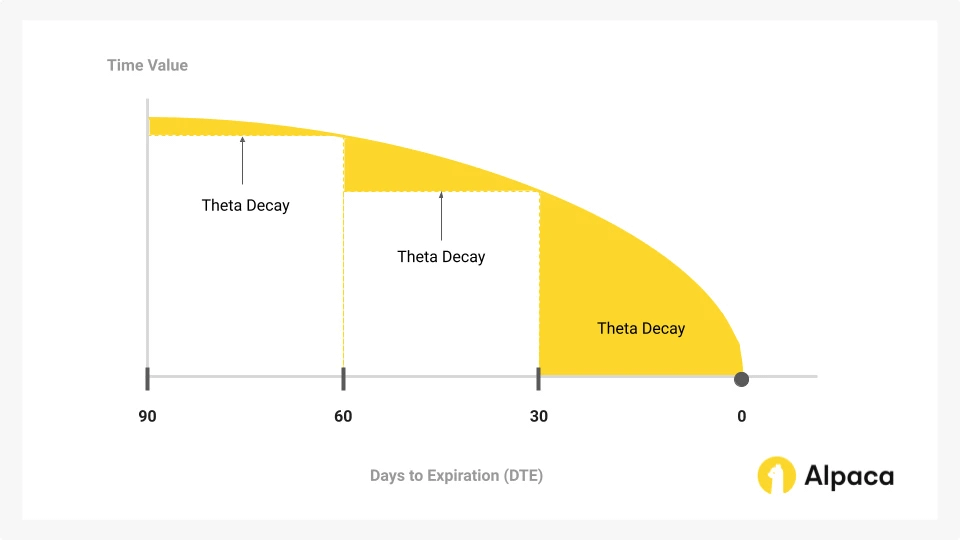
Figure: Time value is the main part of options that depreciates over time and is also the core of 0DTE options traders' battles.
Therefore, perpetual contracts, as a Delta One product, are valued for stripping away excess time and volatility costs, providing purely linear leveraged exposure that can mathematically match the speculative needs of this capital more accurately than 0DTE Options.
1.2 Market Entry 2: CFD Market in Non-U.S. Regions
In markets outside the U.S., retail leverage demand is mainly met by CFDs (Contract For Difference), with the monthly average trading volume of the CFD market reaching $30 trillion in 2025.
Although CFDs offer a linear return Delta One structure, their market operation model is based on a brokerage model, which has significant transparency issues. The vast majority of CFD brokers adopt a B-Book (internal market making) model, meaning brokers act directly as counterparties to clients (there are serious risk-controlled brokerages in the industry that hedge profitable clients to avoid risk, but since the top few companies in the CFD market only account for twenty percent of the market share, the remaining eighty percent is filled with many small and medium-sized brokers, leading to a lack of overall transparency and reliance on customer losses to profit), in this zero-sum game structure and opaque black box, brokers have the technical authority and economic motivation to modify quotes, slippage, and execution speed.
Compared to CFD products, RWA Perps can also be understood as a 'transparent CFD based on smart contracts.' By putting the liquidation logic, funding rate calculations, and oracle quotes on-chain, the DeFi protocol eliminates the possibility of centralized brokers intervening in trading outcomes. At the same time, the stablecoin-based atomic settlement mechanism improves the efficiency of capital flow to the second level, achieving true self-custody of funds and real-time settlement.
2. RWA Perps Product Construction Challenges
RWA Perps is not just a simple replica of the Perps focused on crypto assets that we have seen before. Crypto assets have the characteristics of 7x24-hour trading, real-time pricing, and T+0 on-chain settlement, but traditional assets are constrained by the legal framework of the physical world, holiday systems, and outdated bank settlement protocols.
The asynchronous nature of these underlying attributes creates the 'impossible triangle' in the product design of RWA Perps:
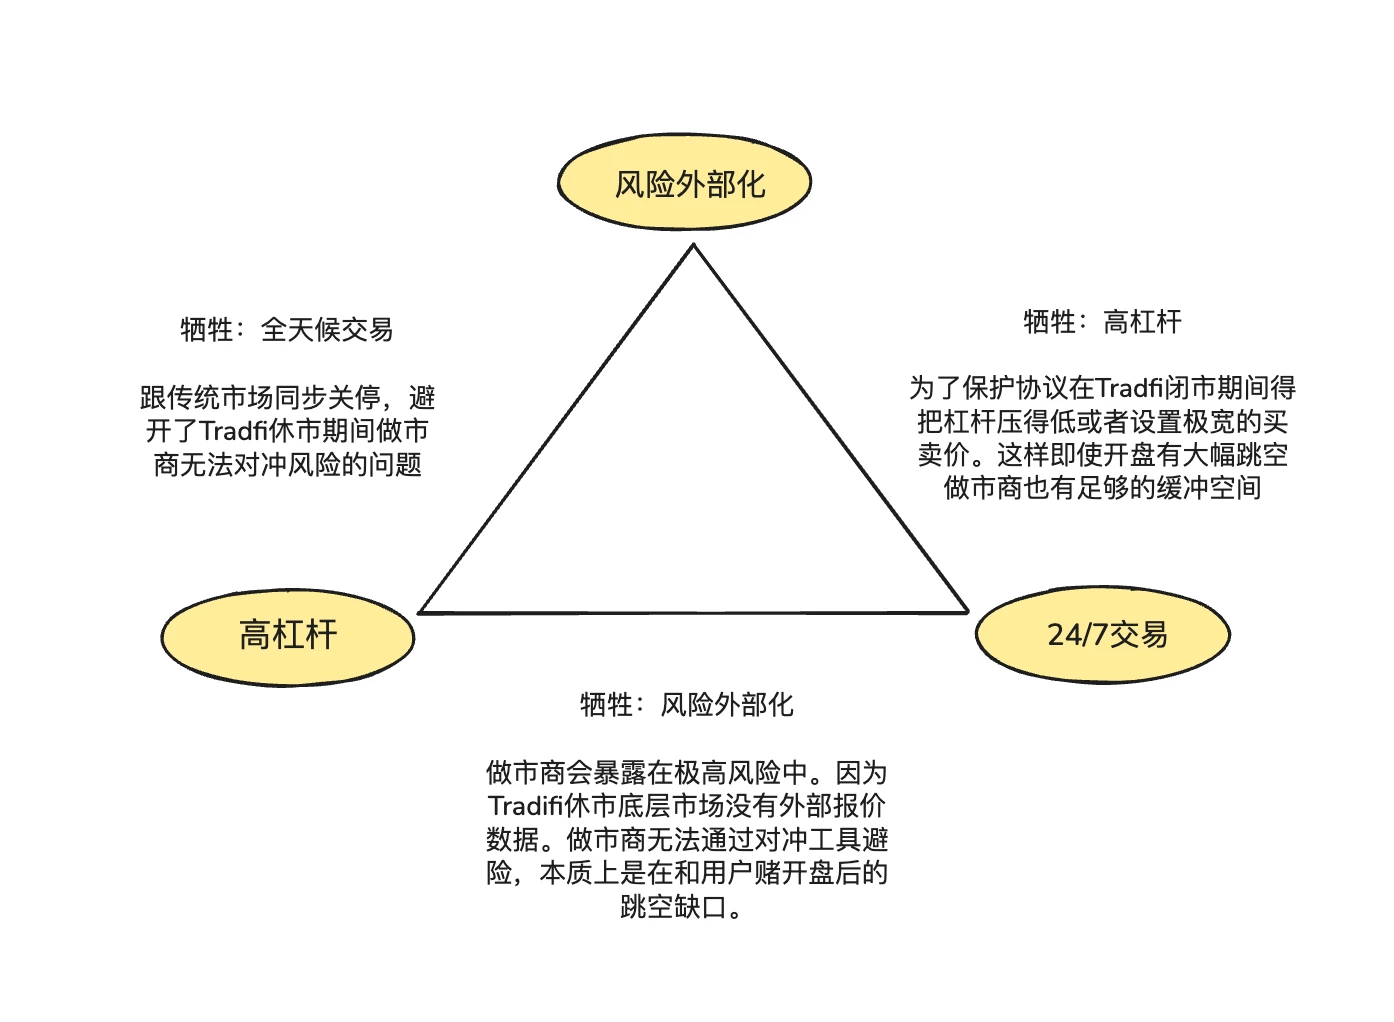
High Leverage: Meets the speculative demand of retail users for high multiple leverage.
24/7 Availability: Maintains the core value of DeFi transactions anytime, anywhere.
Risk Externalization: Ensures that the protocol and market makers do not bear directional betting risks, achieving systemic long-term survival.
2.1 How to Anchor On-Chain Prices of RWA Perps When the U.S. Stock Market is Closed?
The essence of Perps products is 'a mirror of price discovery.' It requires continuous external spot price feeds. However, when NASDAQ or CME is closed on weekends and nights, it causes breaks in the oracle data sources.
This pricing vacuum and misalignment during the U.S. stock market closures generate two core risks:
Risk 1: Market makers lack sufficient risk hedging channels during weekend closures
Professional market makers can provide extremely narrow spreads and deep liquidity because they do not bet on direction but pursue neutral positions only to collect spreads. This means that when market makers sell a $1 million Tesla stock contract to traders on-chain, they must immediately buy an equivalent amount of assets in traditional spot or futures markets to hedge this risk exposure.
When traditional markets are closed, hedging channels are shut down, and market makers cannot adjust their hedging positions. To avoid this risk, market makers during non-trading hours can only choose to withdraw orders or add large risk premiums to their quotes. This explains why traditional order book models experience non-linear spread expansions to dozens of times normal levels on weekends, easily leading to liquidity drying up.
Risk 2: The 'gap risk' of extremely high or low openings on Monday.
Due to the 24/7 nature of trading in crypto-native assets, asset price curves are usually continuous, and the liquidation engine has enough time to liquidate users' positions when prices drop. However, in the RWA Perps space, the pressure from price fluctuations accumulated during traditional market closures is released instantaneously when the market opens on Monday. If there is a significant gap at Monday's opening, the liquidation engine can find itself in a vacuum zone during a 'price dislocation,' unable to find counterparties to execute liquidations before liquidations occur.
In response to the above dilemmas, there are currently two main handling solutions for RWA Perps:
Internal simulation pricing (such as TradeXYZ / Hyperliquid): Introduces an Exponential Moving Average (EMA) algorithm that allows prices to 'drift' slowly based on on-chain buying and selling power when the oracle disconnects, maintaining a 7x24 shell, but theoretically remains a potentially manipulable 'shadow market.'
Mandatory risk downgrade (such as Ostium): This is a more pragmatic risk management solution. Ostium introduced 0DTE properties: requiring all high-leverage positions to be automatically liquidated or significantly reduced in leverage before the close. Only low-leverage positions (with sufficient margin buffers to cover a 5%-10% gap) are allowed to be held overnight. This approach sacrifices part of 'perpetuality' in exchange for absolute safety for the system when facing Monday morning gaps, preventing LP pools from being penetrated by systemic bad debts.
2.2 How to provide TradFi-level trading depth on-chain at a low cost?
In the development of DEX, the choice of liquidity supply and order execution mechanisms is a core variable determining the system's capital efficiency, risk distribution logic, and user experience. The two mainstream solutions are: CLOB (Central Limit Order Book) and Oracle-based Pool (Oracle-driven funding pool).
Hyperliquid has validated the success of the order book model for crypto-native assets, with its core being zero friction in hedging execution: market makers can transfer risks across platforms in milliseconds using stablecoins. After receiving orders on-chain from the order book, market makers can use stablecoins for millisecond-level risk hedging on CEXs operating 7x24 hours. As crypto funds and assets operate in a highly interconnected crypto network, hedging costs are extremely low, allowing market makers to suppress quote spreads to a very narrow range, thereby attracting trading volume and creating a positive feedback loop.
In the RWA space, market makers face significant cross-border hedging friction: on the one hand, on-chain USDC (T+0) and the time mismatch of traditional fiat currency settlements force market makers to keep large amounts of dollars in traditional accounts as hedging reserves; on the other hand, the closure mechanism of traditional banks on weekends and holidays causes market makers to be unable to hedge in a timely manner during unexpected market movements on non-working days.
This is also why Kaledora, the founder of Ostium, insists on a pool-based model rather than the core logic of an order book. She believes that the zero-friction hedging typical of crypto-native asset exchanges is difficult to achieve in the RWA perps space. When a market maker takes the next NVDA order in RWA Perps, they cannot use stablecoins to hedge in milliseconds on NASDAQ because they must overcome numerous barriers in traditional banking channels.
2.3 How does the system ensure it does not go bankrupt when traders continue to profit in one-sided markets?
The third dilemma involves how the protocol ensures long-term solvency through external hedging. GMX's pool model has managed to survive in the crypto market long-term because it acts as a 'passive dealer,' leveraging statistical advantages from large samples to stabilize the wear and tear of high-leverage positions and capture liquidation profits during frequent fluctuations. In the crypto market, which exhibits distinct oscillatory features, this model's mathematical expectations are favorable for pool LPs.
But the risk distribution of RWA assets is entirely different. Mainstream indices like the S&P 500 often exhibit sustained multi-year one-sided trends. In the absence of risk externalization (hedging) mechanisms, users' continued profits will directly translate into net losses for the LP capital pool, leading to the system not only failing to capture volatility dividends but also being completely drained by one-sided positions, ultimately facing solvency exhaustion.
3. Representative Projects and Structural Game: Oracle Pricing + Funding Pool (Pool based + Oracle pricing) vs. Order Book
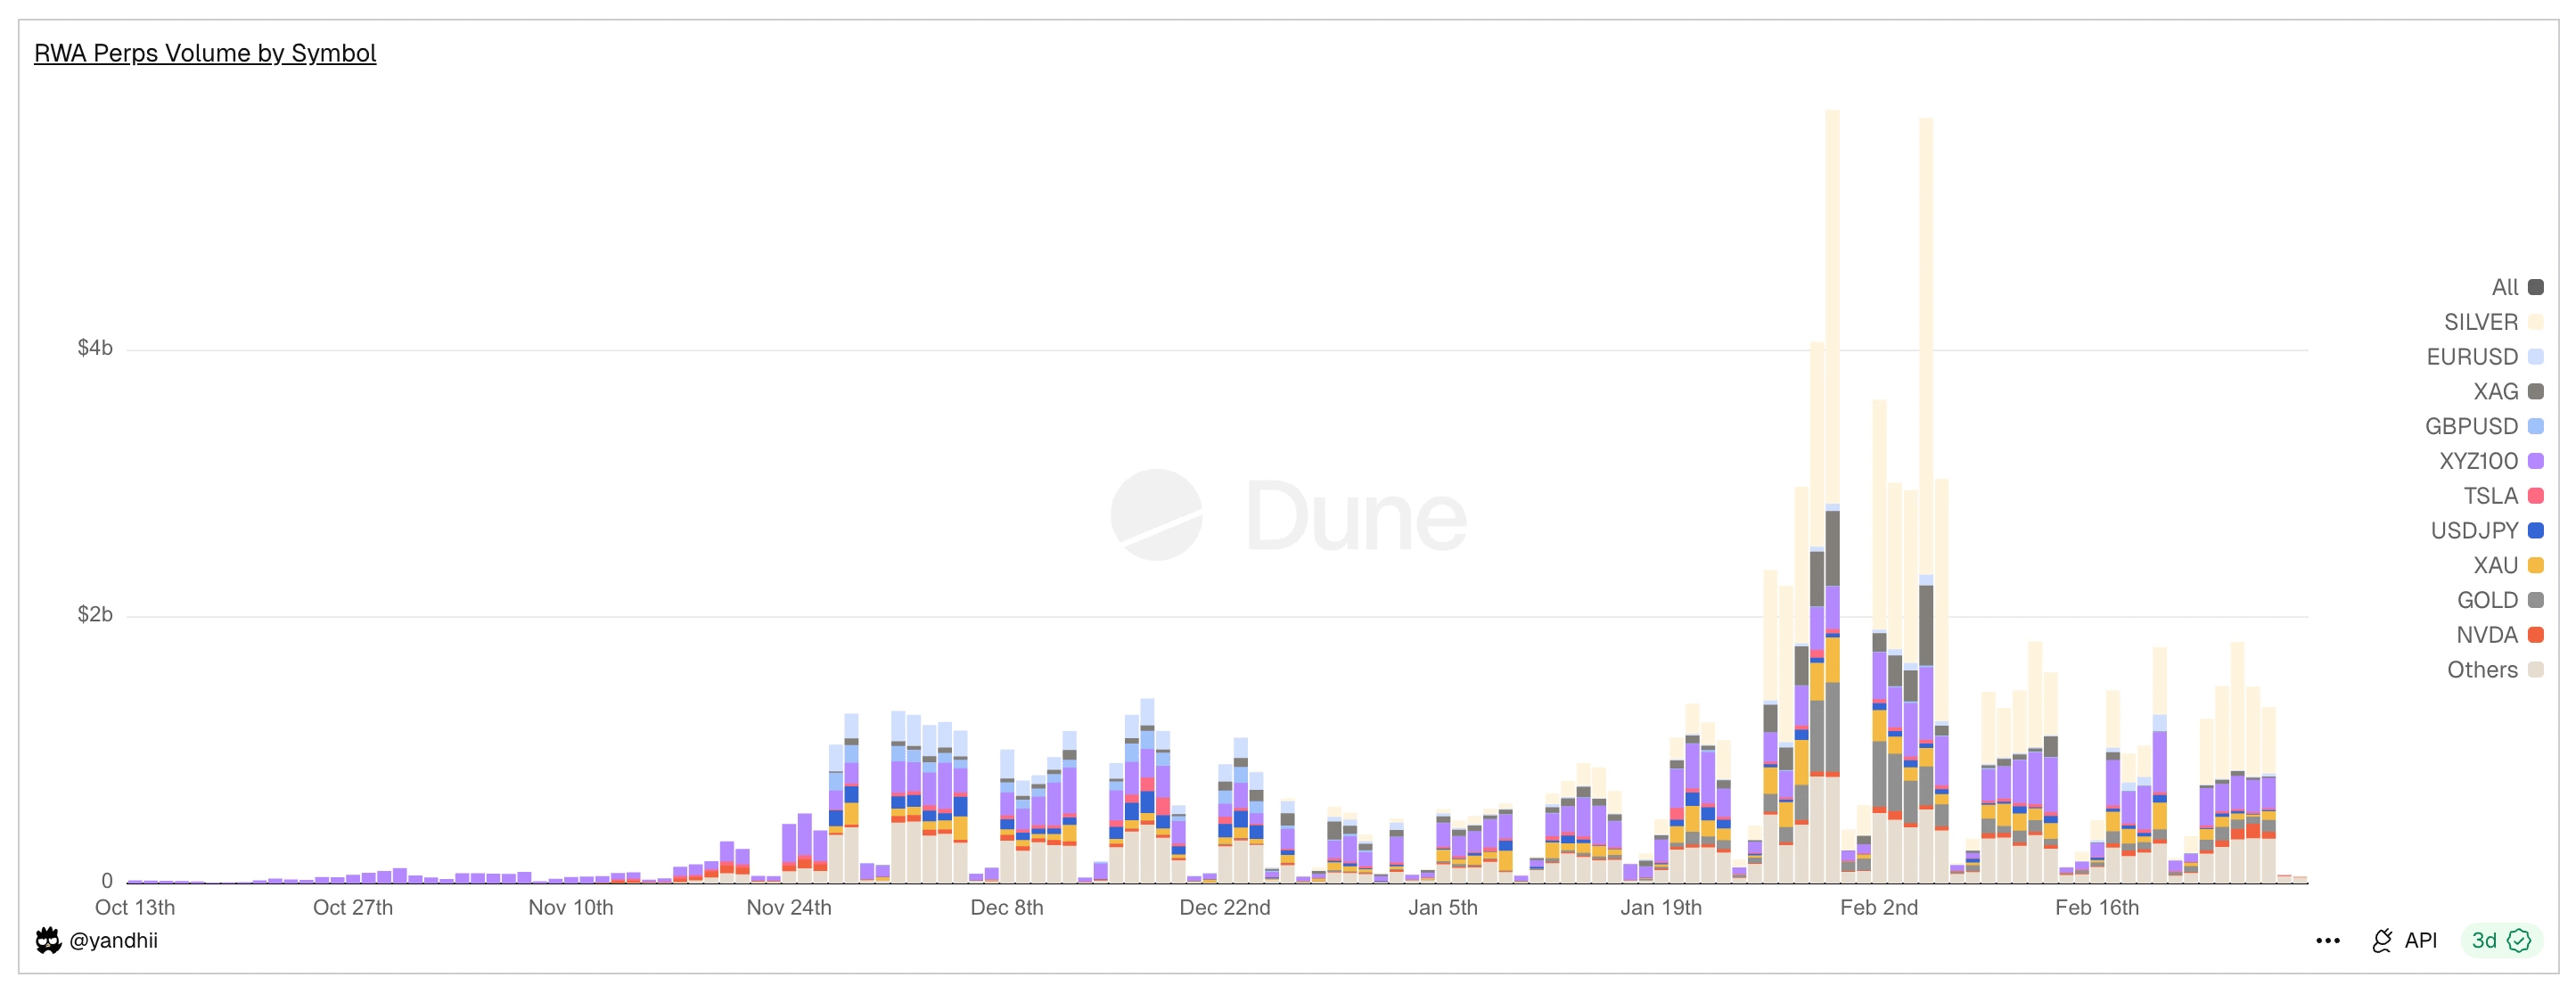
Figure: Daily trading volume of RWA Perps Dex, showing that weekend trading volume will drastically shrink.
The core contradiction of RWA Perps always revolves around 'the dislocation of physical time': although various RWA Perps Dex platforms have generated over $20 billion in trading volume within 30 days, trading volume during weekends drastically shrinks by 70-90%. This data reveals the true state of the industry: although DeFi attempts to break free from the gravity of traditional finance, liquidity still heavily relies on the opening times of TradFi.
Faced with this dislocation, the market has evolved into two distinctly different architectural paradigms: the active hedge pool model represented by Ostium and the internal pricing order book model represented by Trade.xyz in the Hyperliquid ecosystem.
3.1 Early RWA Perps Projects Synthetix, Gains Network
Before Ostium and Hyperliquid attempted to reconstruct RWA trading through complex hedging mechanisms or order books, the DeFi market had already conducted the first round of experiments with 'synthetic assets.' Early protocols like Synthetix and Gains Network completed the concept validation of RWA Perps, demonstrating the strong demand for on-chain capital exposure to traditional assets, but also fully exposing the ceiling of first-generation mechanisms in capital efficiency and risk control.
Synthetix: Global Debt Pool Model
Synthetix is one of the earliest protocols to attempt to bring real asset prices onto the chain. Between 2020 and 2021, Synthetix aggressively tried to launch mirrored stocks like sAAPL and sTSLA, aiming to bring US stocks on-chain.
As the pioneer of the 'pool counterparty' model (where the counterparties are all SNX stakers), Synthetix's design philosophy is to establish a model of exchange without an order book and unlimited liquidity: all synthetic assets are freely exchanged at prices provided by oracles, and users do not need to match trading counterparties. This greatly solved the liquidity cold start problem in the early stages, especially under the incentive of liquidity mining at that time.
Synthetix delisted most RWA assets after 2021, primarily due to the lack of proactive hedging mechanisms at the protocol level, making stocks like sTSLA vulnerable to attacks when prices cannot be updated during market closures.
Overall, Synthetix pioneered the model of providing on-chain RWA mirrored asset liquidity with derivative collateral pools, and the design of no order book + oracle pricing remains influential today. However, the product side has essentially begun to exit the RWA Perps market around 2022.
Gains Network (gTrade): A market-making pool model driven by oracle pricing.
Gains is another early exploration representative project for on-chain RWA synthetic leveraged trading, supporting various trading pairs such as cryptocurrencies, forex, and US stocks. Its design philosophy is to use independent asset pools as counterparties: users use USDC, DAI, and ETH as collateral to open synthetic leveraged positions, and the profit and loss of trades are borne by the capital pool (gToken Vault).
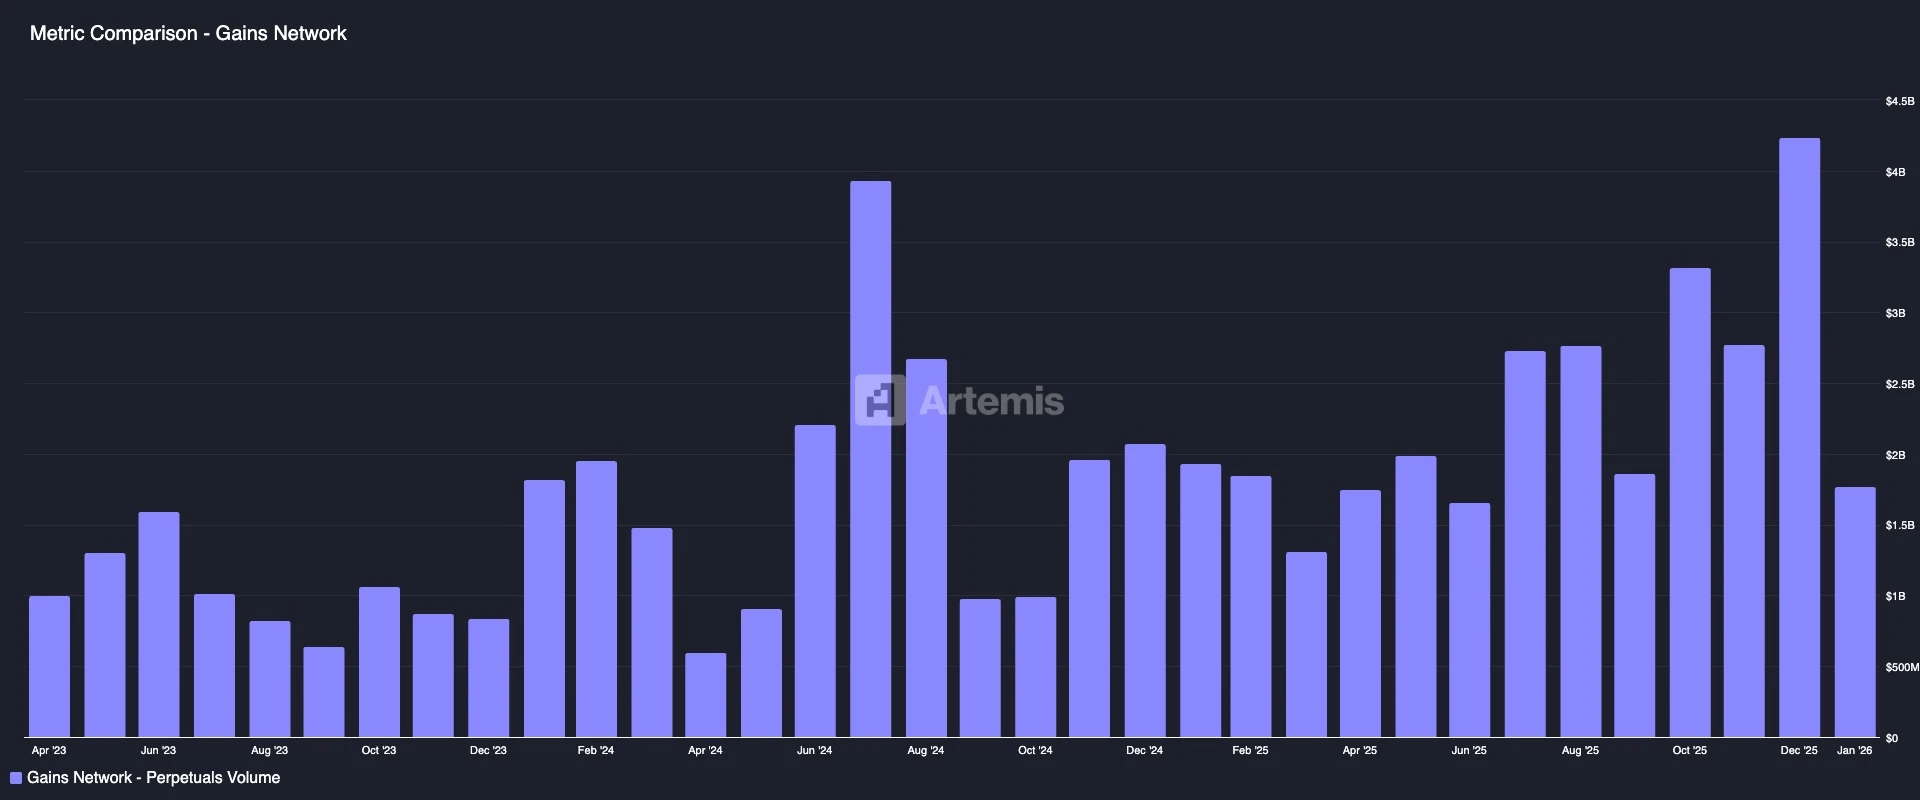
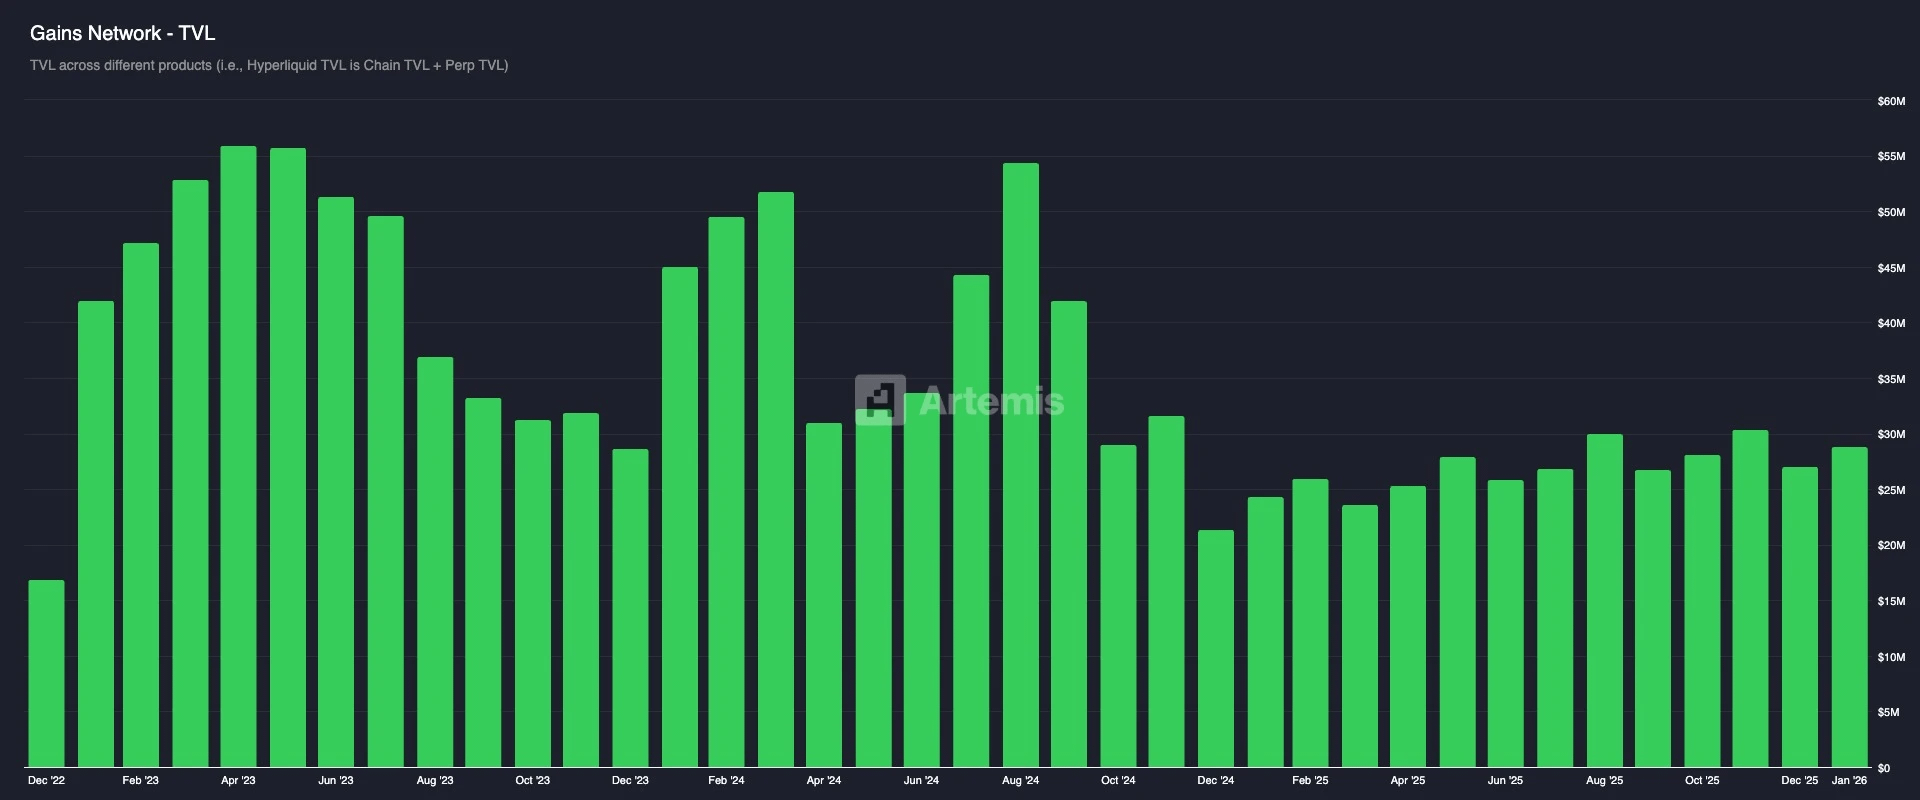
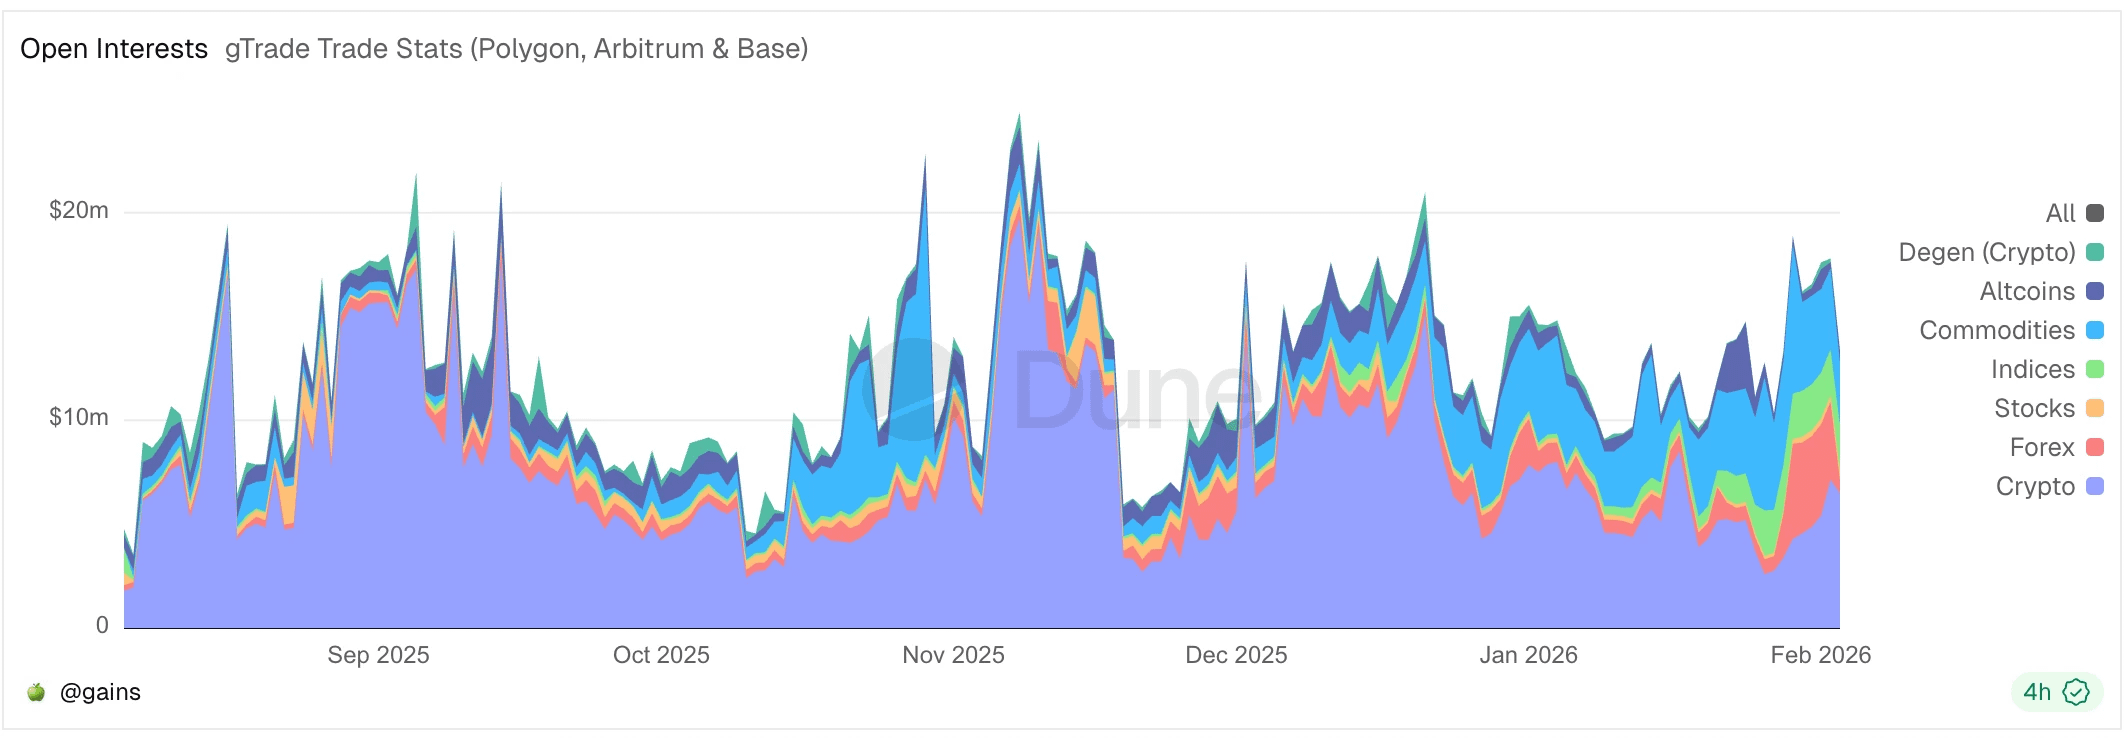
Liquidity Model and Market Making Game Mechanism:
One-sided treasury: Gains' market-making capital pool mainly consists of stablecoins like USDC/DAI.
GNS token as a risk buffer and incentive: To prevent the market-making capital pool from being penetrated under extreme market conditions, the protocol introduces GNS token as the last line of defense. When the market-making capital pool has surplus, the protocol will repurchase and burn GNS tokens using excess profits from the pool to reduce inflation. When the market-making capital pool incurs losses, the system will issue additional GNS and sell it off-market to replenish market-making funds.
In terms of pricing, Gains obtains real-time prices based on Chainlink and adds a fixed spread; the spread income is distributed as fees to LPs and GNS stakers. Risk control incorporates price impact fees (additional fees charged for large orders to simulate slippage and compensate for capital pool risks), and maximum protection (setting upper and lower limits for single profits and losses to enforce profit-taking or forced liquidation) among other designs.
Overall, Gains provides a highly leveraged, multi-market coverage synthetic trading experience, seen as one of the important examples of decentralized exchanges benchmarking against centralized platforms, demonstrating that the 'oracle + funding pool' model can support large-scale trading under reasonable risk control. However, it also exposes challenges such as concentrated profit risks and missing hedging mechanisms that funding pools must bear, providing experience for subsequent project mechanism innovations.
3.2 Ostium: Breaking the Limitations of the Pool-Based Model, Creating an On-Chain CFD Brokerage
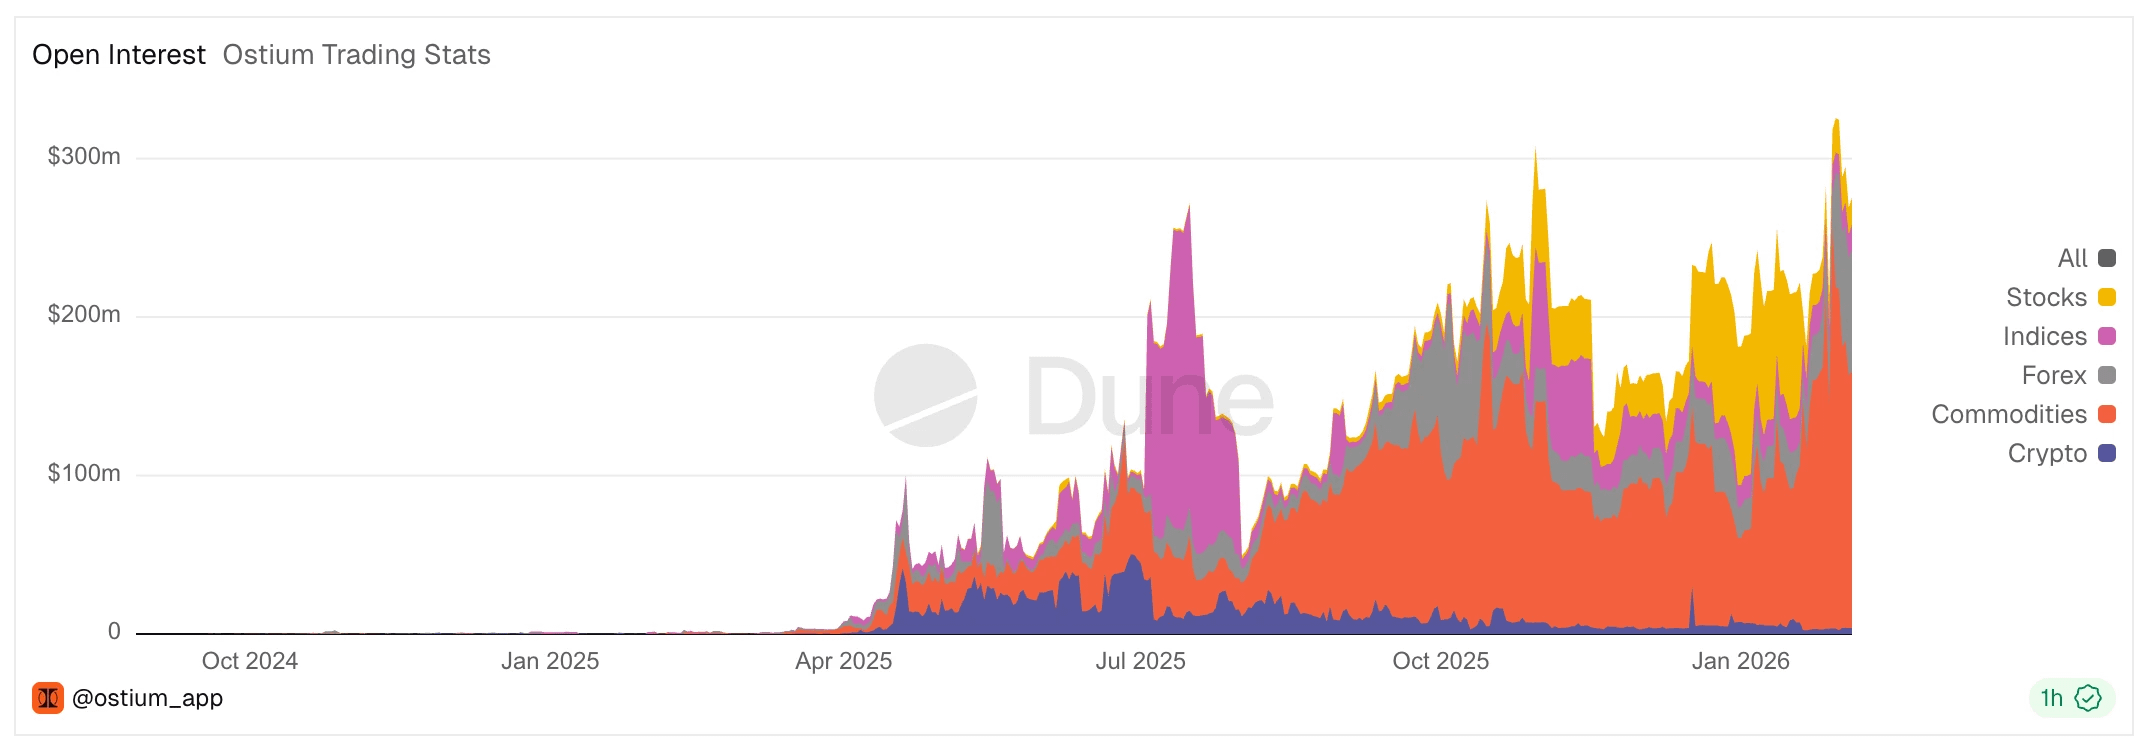
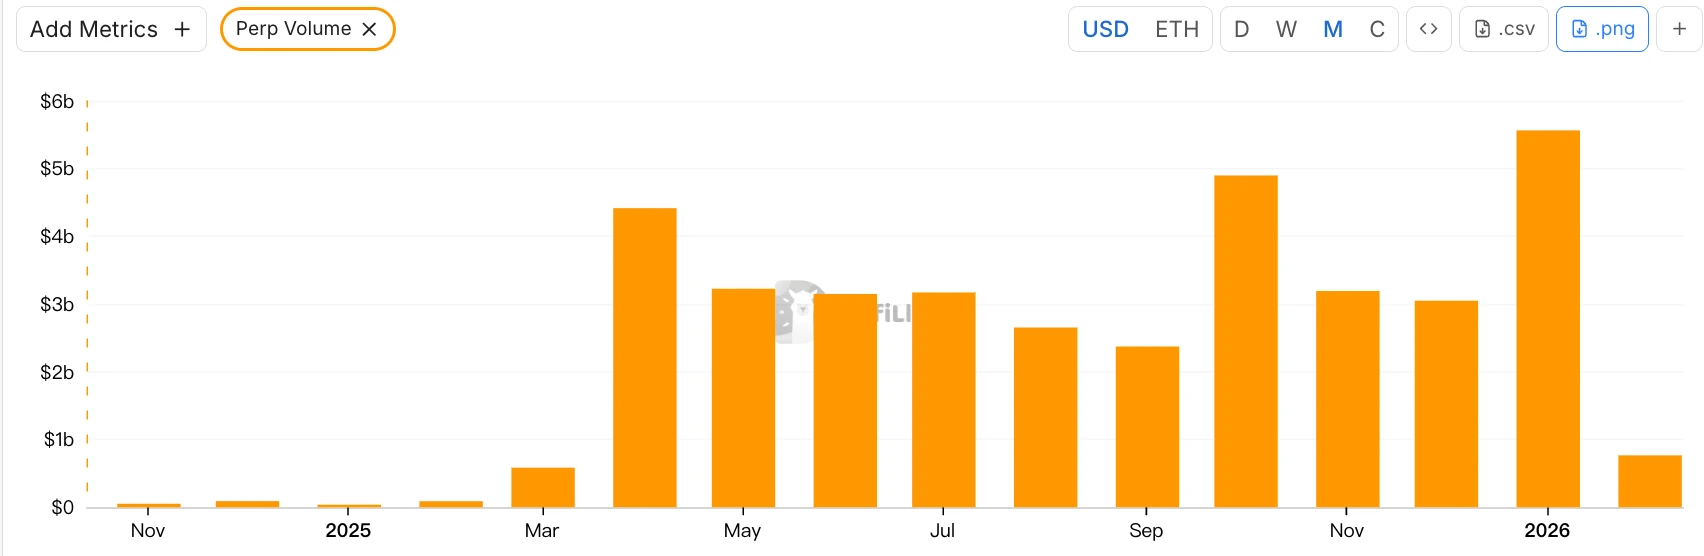
Ostium is a rising RWA Perp DEX, officially launching on the Arbitrum mainnet in August 2025. In terms of liquidity supply and order execution mechanisms, Ostium still chooses the pool-based model as its core architecture. However, they have reflected on the mechanisms of early pool models like GMX and Gains Network and deeply realized that the adversarial game relationship of 'traders profit means LP loss' in traditional pool models is long-term detrimental to LPs. More importantly, it limits trading volume ceilings and cannot broaden market scale (as analyzed in previous Perp Dex studies). Therefore, they have made some special designs to integrate the traditional broker's A-Book (hedging) and B-Book (internal digestion) on-chain to alleviate this zero-sum game conflict.
Interpretation of the liquidity model and market-making game mechanism.
Basic Liquidity Model (Two-Tier Pool Architecture)
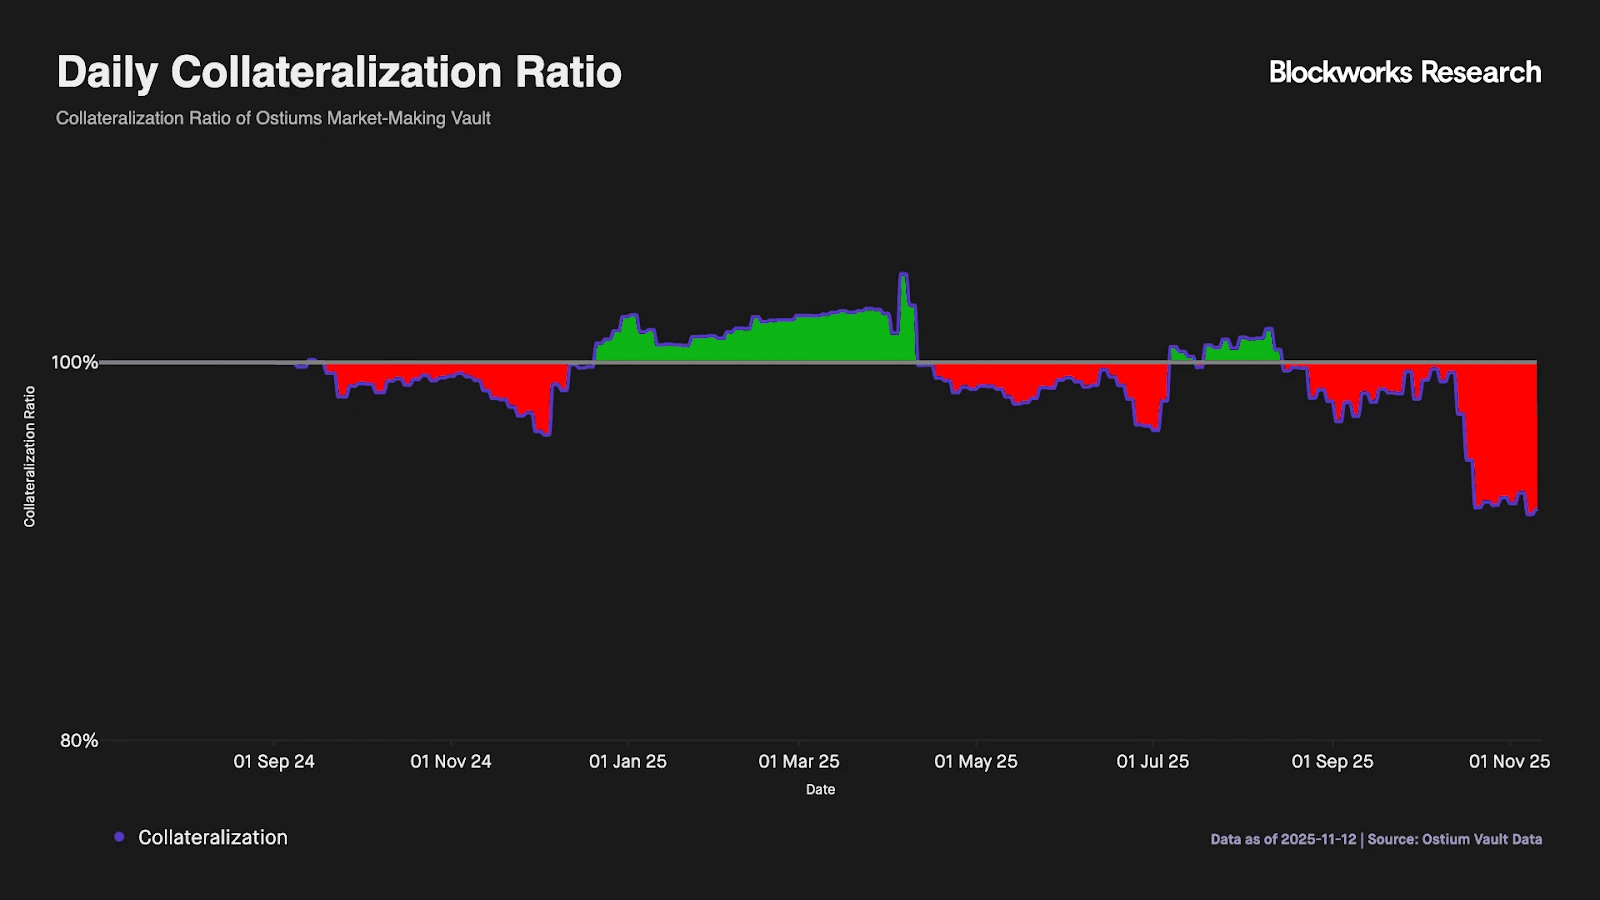
Primary Buffer: Liquidity Buffer This is the 'moat' that the protocol has, accumulated from protocol revenue. Traders' profits are first paid from here, and losses also first enter here. Although the details of the mechanism differ, the role is similar to the market-making pool protection pad in Gains Network.
Secondary Buffer: Market Making Treasury (OLP Vault) This is the pool funded by LPs. Only when the Liquidity Buffer funds are exhausted will the OLP intervene as a direct counterparty.
The core evolution that breaks the main limitations of the original pool-based model: Completely separating 'settlement' from 'market making': Ostium recognizes that the simple two-tier buffer cannot handle long-term directional imbalances (the data displayed in the following figure indeed proves this, as the funds in the liquidity buffer layer are easily exhausted, and when the v1 version of the product only has the above two basic layers, LP still faces long-term one-sided risks). Therefore, Ostium has introduced a more important design—completely separating the functions of settlement and market making from the original passive market-making pool of LPs.
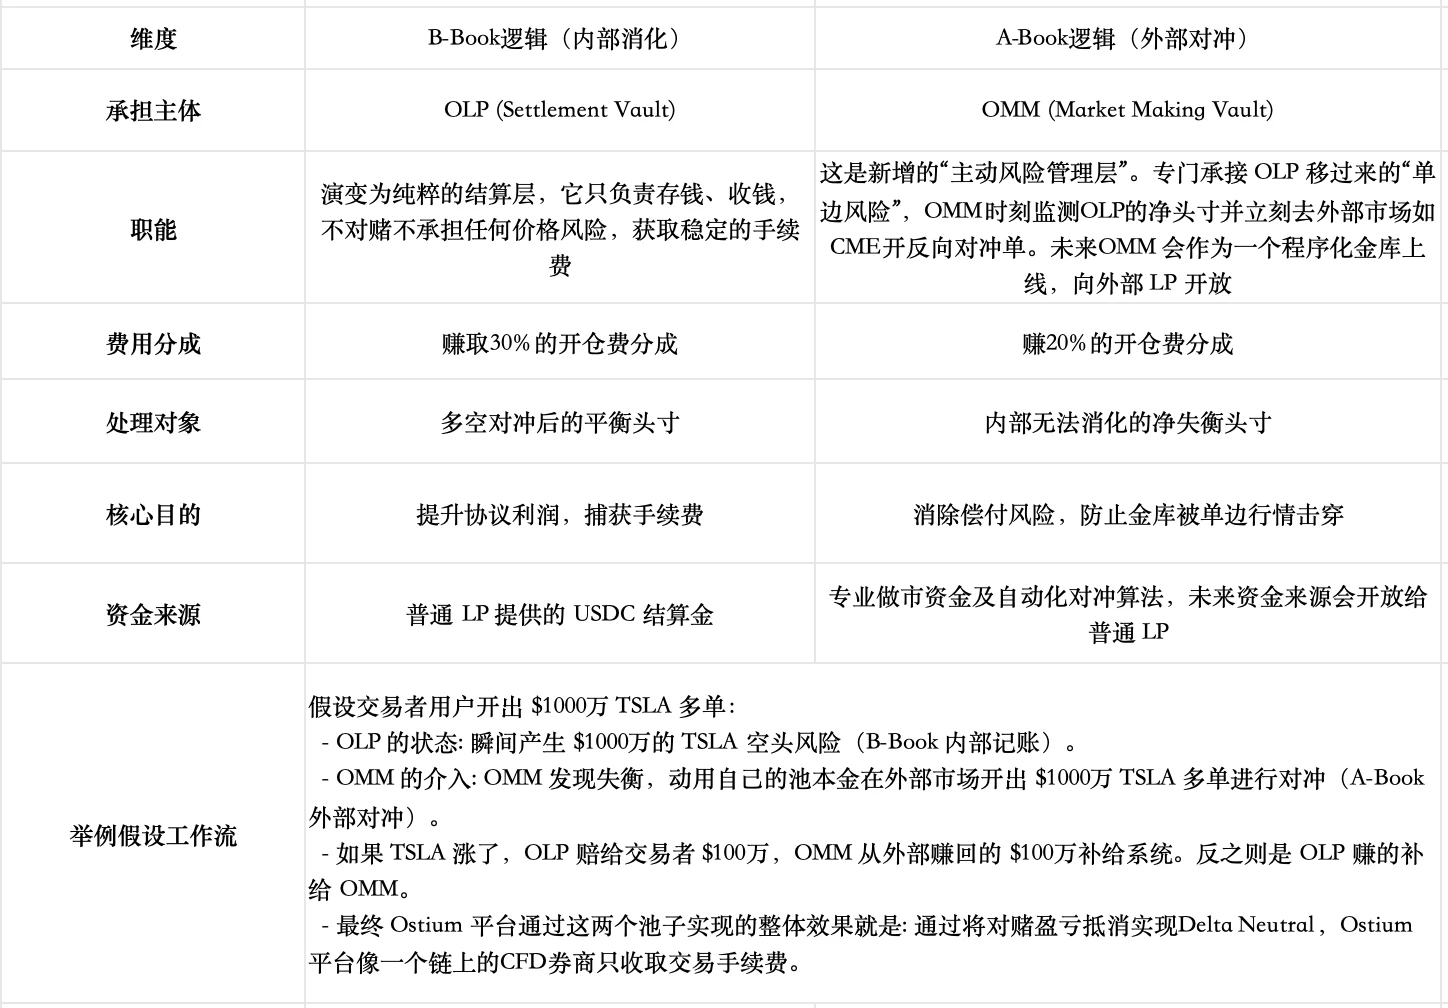
Currently, the OMM market-making hedge vault has not officially launched, and it can be expected that when it bears a high trading volume, the product will require a professional market-making team with strong execution capabilities, which remains a significant challenge: the team needs not only to have compliance qualifications to connect with traditional financial entities but also must achieve millisecond-level cross-market hedging to avoid oracle and external real market basis risks; at the same time, they need strong capital scheduling capabilities to overcome the mismatch of capital flow timelines on-chain and must monitor Delta net position imbalances in real time, flexibly employing dynamic spreads or impact fees for precise risk control.
Risk Control During Market Closures
Ostium deeply aligns with U.S. stock trading hours, using built-in timestamps in the oracle to ensure that market orders are only executed when the market opens, effectively eliminating the risk of price vacuum during market closures. To address the common gap risk in U.S. stocks, the platform has established strict 'liquidation checkpoints': 15 minutes before daily closing, the system automatically forcibly liquidates positions with leverage exceeding a threshold (such as 10x), reverting daily maximum leverage of 100x to a safe range.
Why haven’t existing Pool Based projects like GMX implemented similar designs?
GMX's long-term adherence to a pool model without separating directional risk is mainly due to the significant trade-off and differing market starting points: the current design has achieved relative balance through internal mechanisms (such as adaptive funding fees, price impact, long/short pool separation), introducing external/independent hedge vaults would sacrifice revenue, increase complexity, and centralization risks. Additionally, GMX's pool actually bears the comprehensive exposure of all traders, and in the highly volatile crypto market, individual random bets tend to statistically approach a negative expected value. The pool captures the positive expected value. On the other hand, Ostium focuses on markets like stocks and other RWA markets, which have significantly lower volatility, and they aim to penetrate the traditional CFD brokerage market.
Additionally, in August 2025, there was a proposal in the GMX governance forum for a Global Hedge Vault (GHV) that aimed to introduce external market maker mechanisms to achieve a Delta Neutral-like effect, indicating that other Pool Based projects are also paying attention to this new trend.
Why choose a pool model instead of an order book?
Ostium founder Kaledora has a clear theoretical logic for why she insists on choosing a Pool Based model and not opening weekend trading. She has previously faced attacks from the Hyperliquid community for criticizing the order book projects like Trade that showed outrageous high funding rates during weekends.
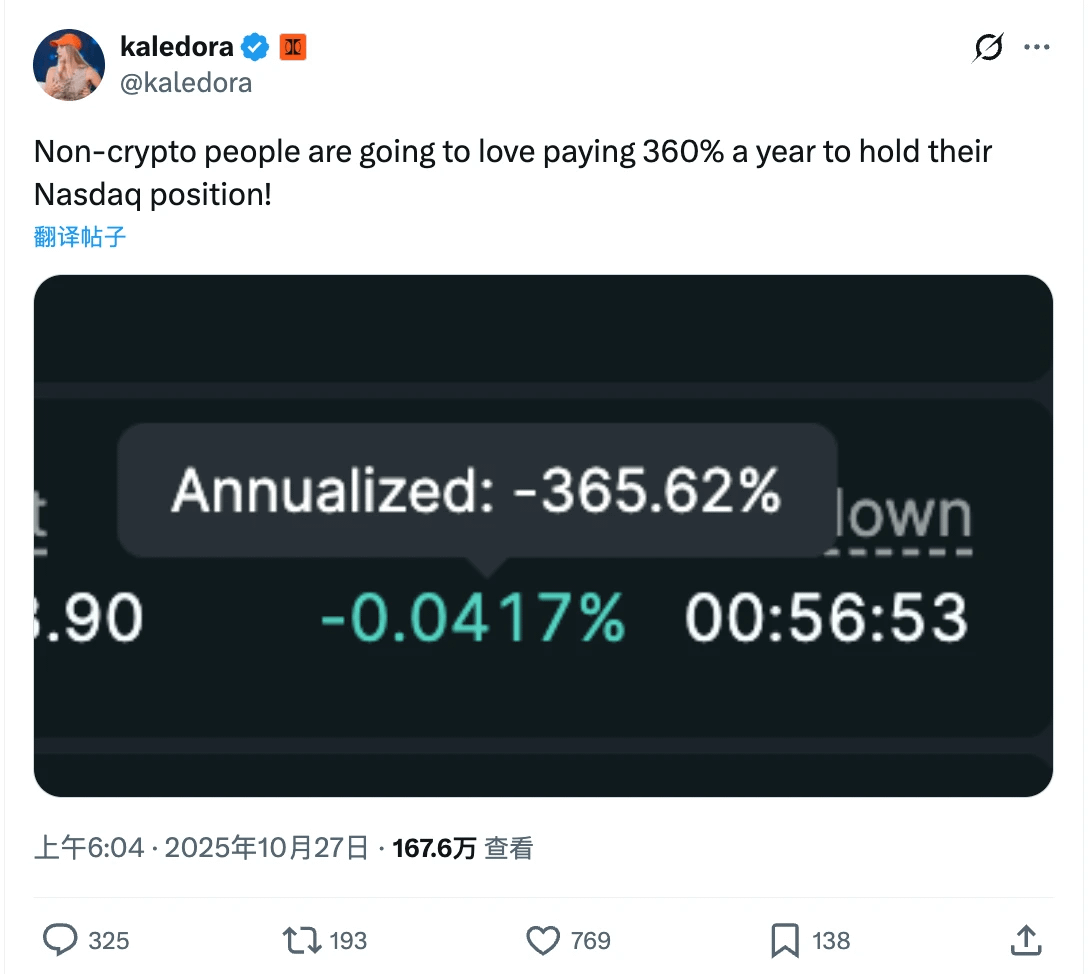
Figure: Ostium founder points out that traditional market opening times for Trade.xyz result in outrageous funding rates during weekends.
Her theory is that the limitations of the traditional pool-based model (where LPs bear one-sided directional risks, and the system's capital constraints limit trading volume ceilings) have already been addressed by her new design. By introducing a mixed risk control of A-Book and B-Book, unilateral risks are transferred in real time to a liquidity-unlimited global market. Once unilateral risks are technically resolved, the OI ceiling is no longer constrained by the size of the pool; the protocol's trading volume ceiling will entirely depend on its distribution capacity (similar to the business model of top CFD brokers).
In comparison, she believes that the core function of the order book is price discovery, which is very meaningful for crypto-native assets but represents a significant waste of resources in the RWA space. Because prices for stocks and forex already have extremely perfect real-time discovery in top global exchanges like NASDAQ and CME, recreating an on-chain order book means you must compete with these trillion-dollar giants in a 'bloodless' environment. This depth from traditional exchanges' dimensionality reduction makes any large trader prefer brokers that can reference global prices rather than an order book with shocking slippage.