

Summary: From models, computing power to cloud and security, OpenClaw may impact the profit logic of US stocks.
Author: Viee I Biteye content team
In November 2025, an independent Austrian developer Peter Steinberger quietly submitted a project on GitHub - Clawdbot (now renamed OpenClaw).
At that time, no one cared; everything spiraled out of control at the end of January 2026.
Between January 29 and 30, the project quickly gained tens of thousands of GitHub stars and swiftly broke through 100,000. By March 3, this number had swollen to nearly 250,000, topping the star rankings, surpassing Linux. For reference, star projects like React (one of the most popular front-end development frameworks globally) and Linux (the operating system kernel that supports internet servers) typically take over ten years to accumulate around 200,000 stars, while OpenClaw's curve is almost vertical.
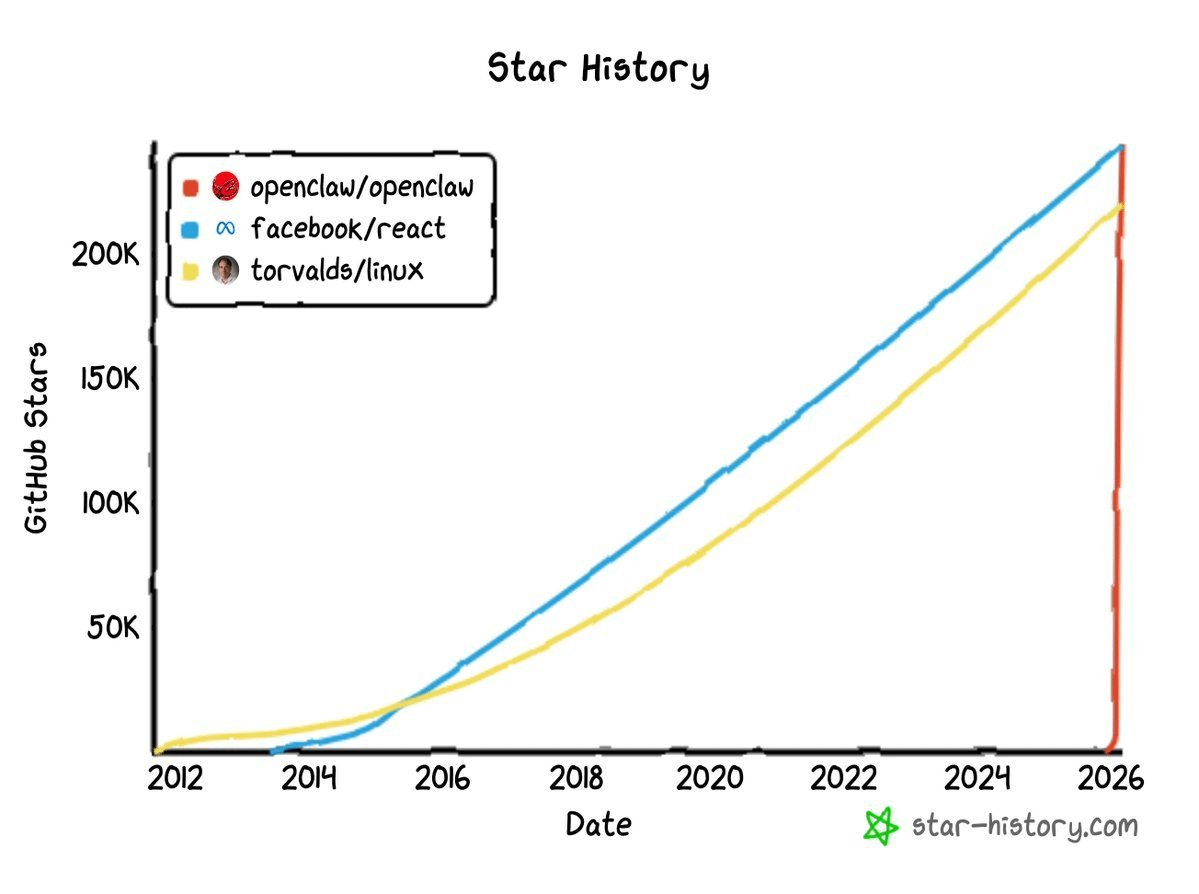
OpenClaw's original name Clawdbot sounds like Claude; Anthropic sent a lawyer's letter on January 27 demanding a name change, and the project went through Moltbot before finally being named OpenClaw. However, the change of name has not slowed down its spread; instead, it has created more topics. On February 16, Sam Altman announced that Steinberger would join OpenAI, and OpenClaw would be handed over to an independent open-source foundation supported by OpenAI.
From an independent developer's project to a strategic piece for tech giants, this little crayfish took less than three months.
The popularity of OpenClaw in the tech circle is evident to all; where has this fire now spread? This article attempts to outline the beneficiary industrial chain behind OpenClaw's explosive popularity from the perspective of the capital market, as well as US companies that may be revalued.
One, what is OpenClaw? Why does it have an impact on US stocks?
Let's get to the essence. OpenClaw is not just another chatbot; it is an open-source AI Agent framework.
What's the difference? Chatbots receive your questions and return a piece of text. OpenClaw receives your instructions and then takes action. It can operate a browser, execute code, call APIs, manage file systems, and connect to more than 12 messaging platforms.
The differences in their operating models can be summarized in a table:
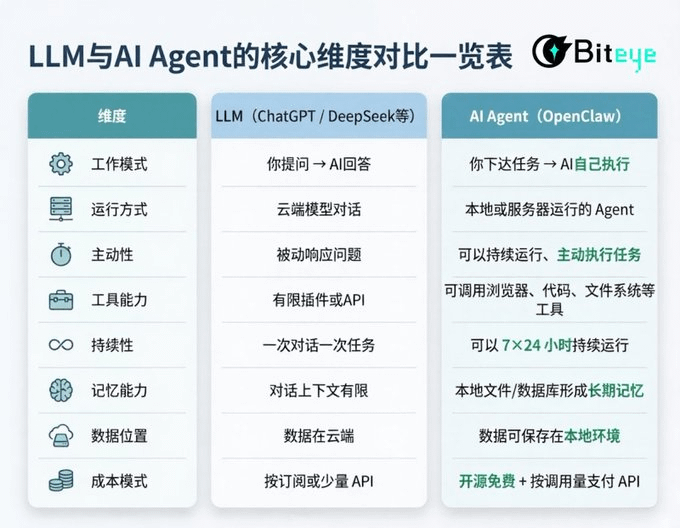
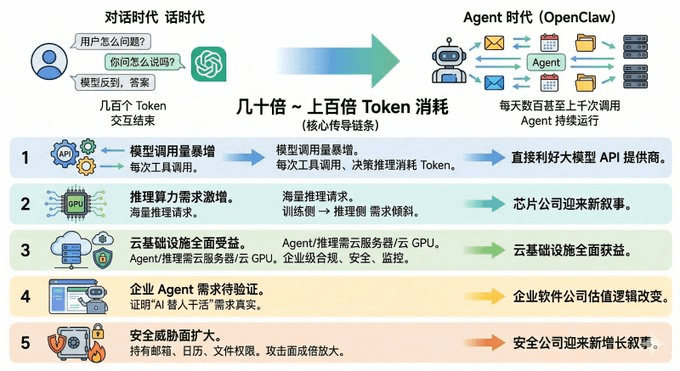
In summary, to put it more plainly, it has evolved from a chatbot into a real digital employee, which also means that the business paradigm of AI is undergoing a profound change. In the dialogue era, users would ask a large model a question, and the model would return an answer, consuming hundreds of tokens, ending the interaction. But in the Agent era, an OpenClaw may initiate hundreds or even thousands of calls to the model every day. The token consumption generated by a single Agent user can even be dozens or hundreds of times that of traditional chat users.
This consumption multiplier is the core transmission chain of how OpenClaw affects US stocks:
First layer: Explosive growth in model call volumes. Each tool call and each decision reasoning by Agents consumes tokens, directly benefiting large model API providers.
Second layer: Explosive demand for reasoning computing power. Massive Agent calls mean massive reasoning requests, shifting the demand logic for GPUs from the 'training side' to the 'reasoning side', bringing a new narrative for chip companies.
Third layer: Cloud infrastructure benefits comprehensively. Agents need cloud servers to run, model reasoning requires cloud GPUs for computing, and enterprise-level Agents need compliant, secure, and monitorable cloud infrastructures.
Fourth layer: The demand for enterprise Agents is yet to be verified. OpenClaw has proven the real demand for 'AI doing work for people' in an open-source manner, and enterprises that are commercializing Agent capabilities may see changes in their valuation logic.
Fifth layer: The security threat surface expands. When Agents hold email, calendar, and file system permissions for a long time, the attack surface is exponentially enlarged, providing new growth narratives for security companies.
Next, let's follow this chain and analyze the beneficiary US stocks one by one.
Two, the token killer: the super flywheel of large model service providers.
If Agents become the mainstream paradigm for AI interaction, the API revenues for large model vendors will see exponential growth.
However, the two largest Agent model suppliers, OpenAI and Anthropic, have not yet gone public. Therefore, the most direct corresponding public targets in the capital market are MSFT and GOOGL.
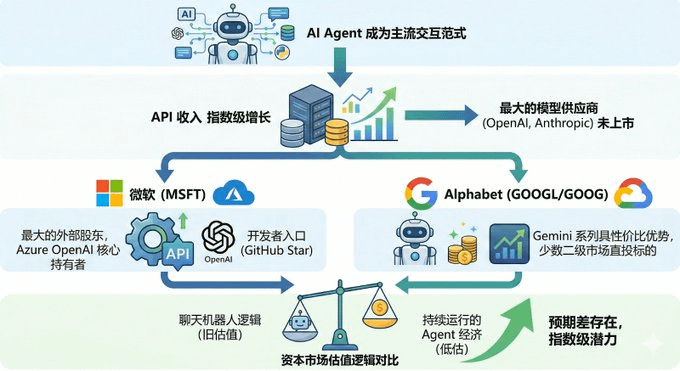
Firstly, Microsoft, as the largest external shareholder of OpenAI, contributes revenue to its cloud business with every API request made through Azure OpenAI Service to call GPT-4o or o1. The OpenClaw founder's joining OpenAI and handing the project over to an OpenAI-supported foundation means that the OpenClaw ecosystem will likely be more closely tied to OpenAI models in the future. If OpenClaw's default model recommendation list ranks OpenAI first, then Microsoft has effectively gained access to a developer with 240,000 GitHub stars.
Alphabet is another beneficiary from a different dimension, which is the publicly traded company to which Google itself belongs (stock codes GOOGL / GOOG). Google's Gemini series is one of the mainstream models supported by OpenClaw, and Gemini 2.0 Flash boasts a highly competitive reasoning cost-performance ratio. More critically, among several leading model providers, Alphabet is one of the few AI model providers that can be directly invested in through the secondary market.
What’s more noteworthy is that the market currently seems to not have fully priced in the API consumption logic driven by Agents. GOOGL has not shown significant increases since February due to the emergence of OpenClaw, and MSFT has undergone a round of valuation adjustments. In other words, the expectation gap still exists, meaning the capital market is still valuing model companies with the 'chatbot' logic rather than the continuously operating Agent economy.
Three, reasoning is never enough: a new narrative for chip companies.
If token consumption is the gasoline of the Agent era, then GPUs are the engine driving this machine, and the most direct beneficiaries remain GPU manufacturers NVIDIA and AMD.
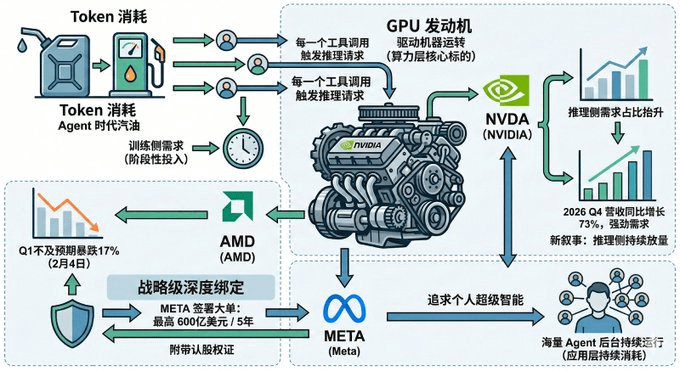
In the past three years, the valuation logic for chip companies in the market has mainly been based on the training side, with various manufacturers competing to purchase GPUs to train increasingly larger foundational models. However, training is more like a periodic investment, while reasoning is a continuous consumption process. For example, every call made by an Agent triggers new reasoning requests constantly. As Agents move from the lab to millions of users, the proportion of demand from the reasoning side is expected to significantly increase.
This also explains NVIDIA's new narrative. Because if the marginal slowdown on the training side continues, what else can sustain GPU demand? The answer given by Agents is the continuous increase on the reasoning side. NVIDIA's latest financial report shows that Q4 2026 revenue grew by 73% year-on-year, with demand still strong, and the rise of the Agent paradigm provides a more sustainable underlying explanation for this strength.
Let’s take a look at AMD. On February 4, AMD plummeted 17% due to Q1 financial reports falling short of expectations, and panic spread. However, just 20 days later, Meta announced it had signed an AI chip supply agreement worth up to $60 billion (over 5 years) with AMD, including a maximum of 16 million shares, about 10% of warrants, resembling a strategic deep binding.
Why does Meta need so much reasoning computing power? Because it is pursuing so-called personal superintelligence, and achieving this vision relies on a large number of Agents running continuously in the background. OpenClaw validates not just a product direction but the demand logic for large amounts of computing power needed by the entire Agent.
In other words, the growth in reasoning demand driven by Agents will first transmit to the computing power layer, with corresponding core targets being NVDA and AMD, while among the companies that continuously consume computing power at the application layer, META may also become an important demand driver.
Four, the true carrier of Agent scaling: cloud computing.
As mentioned earlier, GPUs are the engine of the Agent era, while cloud computing platforms are the infrastructure for these Agents to run long-term. From the perspective of the capital market, the core targets corresponding to this chain are the three major cloud platforms AMZN, MSFT, GOOGL, and at the upstream data center infrastructure level, EQIX and DLR may also become indirect beneficiaries.
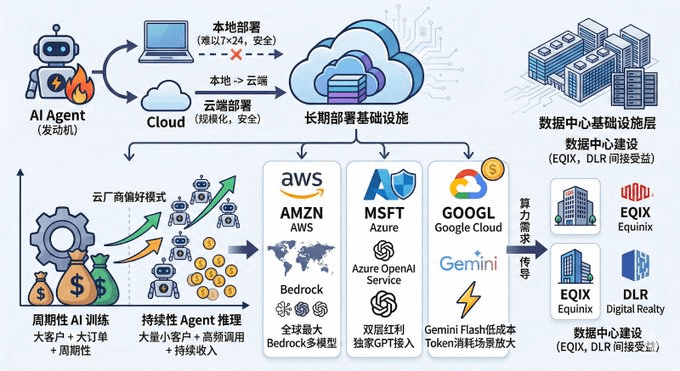
Although OpenClaw boasts local deployment, the reality is that due to security and permission issues, most users will not run an AI Agent on their laptops 24/7. For both individuals and enterprises, the endpoint of large-scale deployment is likely to be cloud deployment. Alibaba Cloud and Tencent Cloud have already launched one-click deployment services in the Chinese market, which indirectly verifies the authenticity of demand.
Moreover, there is an easily overlooked detail here: the value of Agents to the cloud is not just computing power but also long-tail reasoning traffic. Because AI training orders are 'large clients + large orders + periodic', while Agent reasoning is 'large numbers of small clients + high-frequency calls + continuous revenue', which is a business model preferred by cloud vendors.
In the global market, the three major cloud providers each possess unique advantages. AWS, as the largest cloud platform globally, supports multiple model API access through its Bedrock platform, making it one of the common deployment environments for developers. Azure simultaneously benefits from both model API and cloud infrastructure, with the exclusive GPT access capabilities of Azure OpenAI Service being further amplified in Agent scenarios. Google Cloud's differentiation lies in its cost structure. The reasoning prices of models like Gemini Flash are significantly lower than many flagship models, and in scenarios where long-term operation of Agents consumes tokens, this price difference will be rapidly magnified.
Another logical point to pay attention to is that if Agents run at scale, the demand for computing power from cloud providers will eventually feed into data center construction, and Equinix and Digital Realty may also benefit indirectly.
Fifth, the logic of enterprise Agents needs verification, which is beneficial for AI native companies.
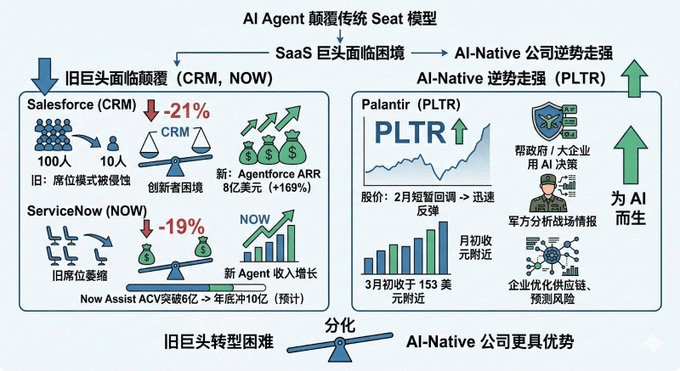
The popularity of OpenClaw verifies a trend: people are willing to let AI do work for them, rather than just chat with them. However, for traditional enterprise software tracks, this is seen by the market as the prelude to the 'SaaSpocalypse'.
As the year 2026 begins, SaaS giants are under collective pressure: Salesforce has dropped 21% since the beginning of the year, and ServiceNow has dropped 19%. The root of the panic comes from a structural game between Agents and software. In the past, we needed a software interface to command the system to do things; now, Agents can directly call the system to complete tasks, diminishing the presence of software itself. This change brings two fundamental issues.
First, the impact of AI is not limited to just the 'per head charge' model but extends to the entire software value chain. Taking Adobe as an example, its stock price fell from a high of $699.54 to $264.04, a drop of 62%; educational software company Chegg plummeted from $115.21 to $0.44, almost zero; tax software giant Intuit also saw a 16% drop within a week in January 2026. The market is concerned not about a specific charging model being overturned but that generative AI tools (like Anthropic) are automating core business workflows, reducing reliance on traditional software functions, thus permanently compressing the revenue potential of the entire SaaS platform.
Secondly, the more powerful the Agent, the more fragile traditional business models become. Taking ServiceNow as an example, Microsoft is eroding its pricing power through the bundling strategy of 'Agent 365', slowing down the speed of acquiring new customers. A simple deduction is enough to make investors shiver: if one AI Agent can accomplish the work of 100 employees, do companies still need to purchase 100 software seats? The emergence of OpenClaw essentially accelerates the realization of this logic.
Of course, several giants have not been idle. Salesforce's AgentForce has achieved $800 million ARR, a year-on-year growth of 169%; ServiceNow's Now Assist annual contract value has exceeded $600 million, expected to hit $1 billion by the end of the year. But it's never easy for elephants to dance; they are caught in the classic innovator's dilemma: new Agent revenues are growing, but old seat revenues are shrinking, and the outcome of the two curves racing is still unclear. For CRM and NOW, the core contradiction lies in whether the increment from Agents can fill the gap left by the seat model. The market has already voted with its feet.
At the same time, Palantir told a completely different story. This company focuses on helping governments and large enterprises make critical decisions using AI: the military uses it to analyze battlefield intelligence, companies use it to optimize supply chains and predict risks, deploying AI into the most complex and sensitive business scenarios. After a brief pullback in February, PLTR quickly rebounded, stabilizing around $153 in early March.
While the SaaS sector is being hit by the 'SaaS apocalypse', Palantir is going against the trend. This differentiation may indicate that the winners in the Agent era may not be the old giants that transform the fastest but rather the companies that were born for AI from the start.
Six, hidden benefits for security companies.
This is currently the most underestimated clue in the market.
Imagine you configured email, calendar, Slack, Google Drive, and GitHub for OpenClaw. It needs these keys to help you work, but what if this Agent is compromised? The OpenClaw community has discussed related security risks multiple times, such as credential leakage, privilege abuse, and even data theft.
This is precisely why security companies are starting to position themselves early. In the current security industry, CrowdStrike (CRWD) and Palo Alto Networks (PANW) are the two most capable leading firms.
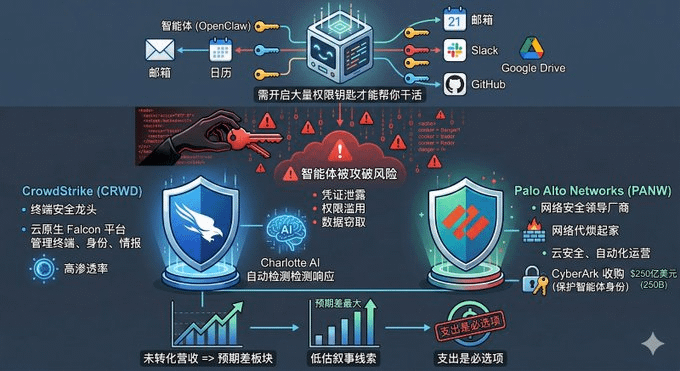
CrowdStrike is considered a leader in the endpoint security field. Its Falcon platform unifies management of endpoints, identities, and threat intelligence through a cloud-native architecture, with extremely high penetration rates among large global enterprises. In recent years, the company has continuously introduced AI into security operations, such as Charlotte AI, which can automatically complete threat detection and response.
Palo Alto Networks is a leading player in the global cybersecurity industry. Starting from next-generation firewalls, it has gradually expanded into cloud security, identity security, and automated security operations, acquiring CyberArk for $25 billion in 2025 to protect intelligent agent identity security.
At the moment OpenClaw has just exploded in popularity, security issues have not yet translated into significant revenue growth, but this precisely means that security companies may have the largest 'expectation gap' in the entire Agent narrative. Moreover, security spending is a necessity.
Seven, conclusion: short-term look at sentiment, medium-term look at reasoning, long-term look at ecology.
Returning to the initial question, what stocks has OpenClaw really leveraged in the US? We can reason through different timelines.
Currently (in the past month), regarding stock price performance, the direct pulse of OpenClaw on individual stocks is quite limited. GOOGL and MSFT have not shown abnormal fluctuations driven by the Agent narrative since February. The only clear event-driven factor comes from AMD, as Meta's massive chip order has propelled its single-day surge. Overall, the AI sector may be undergoing a round of valuation calibration, and the explosive popularity of OpenClaw has not translated into immediate stock price catalysts.
In the short term (3 months), the market may continue to digest the squeeze of the AI valuation bubble, but the cognitive shock brought by OpenClaw may change the buyers' cognitive anchor points regarding the Agent track. This cognitive change will not immediately reflect in stock prices and may reshape analysts' expectation models.
In the medium term (6-12 months), the key catalyst is whether the demand for Agent reasoning computing power can be verified in financial reports. If OpenClaw and subsequent Kimi Claw, MaxClaw, and enterprise-level Agent solutions can bring observable growth in API call volumes and cloud resource consumption, the narratives around the reasoning aspects of NVDA, AMD, and the three major cloud providers may be confirmed.
In the long term (1-3 years), the real winners will be companies that occupy positions in the Agent ecosystem, such as CrowdStrike and Palo Alto Networks, which are establishing standards in the Agent security field.
We also need to know that OpenClaw may not be the ultimate product. It has security vulnerabilities, high token costs, and an uncertain business model. But it has at least done one key thing: it has shown the world the potential of AI Agents. This is no longer product iteration; it is a profound paradigm shift.
Once the paradigm shift occurs, it will not stop; we can only prepare well to wait for that day.