


Author: G3ronimo
Compiled by: Deep Tide TechFlow
HyperLiquid has evolved into a mature crypto-native exchange, with most of its net fees programmatically distributed to token holders through the 'Assistance Fund' (AF). This design makes $HYPE one of the few tokens that can be valued based on cash flow. To date, most of the valuations of HyperLiquid still rely on traditional multiple methods, comparing it with mature financial platforms like Coinbase and Robinhood, using EBITDA or revenue multiples as references.
Unlike traditional company stocks, company management typically retains and reinvests earnings based on their own judgment, while HyperLiquid systematically returns 93% of transaction fees directly to token holders through the aid fund. This model creates predictable and quantifiable cash flows, which are very suitable for detailed discounted cash flow (DCF) analysis, rather than static multiple comparisons.
Our method first determines the capital cost of $HYPE, then we reverse the current market price to determine the market's implied future earnings. Finally, we apply growth forecasts to these earnings streams and compare the resulting intrinsic value with today’s market price, revealing the valuation gap between current pricing and fundamental value.
Why choose discounted cash flow (DCF) over multiples?
While other valuation methods compare HyperLiquid with Coinbase and Robinhood using EBITDA multiples, these methods have the following limitations:
Differences in corporate and token structures: Coinbase and Robinhood are corporate stocks, with capital allocation guided by the board of directors, and earnings retained and reinvested at the discretion of management; whereas HyperLiquid systematically returns 93% of transaction fees directly to token holders through the aid fund.
Direct cash flows: HyperLiquid's design generates predictable cash flows, making it very suitable for DCF models, rather than static multiple methods.
Growth and risk characteristics: DCF can clearly model different growth scenarios and risk adjustments, while multiple methods may not adequately reflect growth and risk dynamics.
Determine an appropriate discount rate
To determine our cost of equity, we start from publicly available market reference data and adjust for crypto-specific risks:
Cost of equity (r) ≈ risk-free rate + β × market risk premium + crypto/illiquidity premium
Beta analysis
Based on regression analysis with the S&P 500 index:
Robinhood (HOOD): Beta of 2.5, implied cost of equity of 15.6%;
Coinbase (COIN): Beta of 2.0, implied cost of equity of 13.6%;
HyperLiquid (HYPE): Beta of 1.38, implied cost of equity of 10.5%.
At first glance, $HYPE's low beta means its cost of equity is lower than that of Robinhood and Coinbase. However, the R² value reveals an important limitation:
HOOD: The S&P 500 explains 50% of its returns;
COIN: The S&P 500 explains 34% of its returns;
HYPE: The S&P 500 only explains 5% of its returns.
The low R² of $HYPE indicates that traditional stock market factors are insufficient to explain its price volatility, necessitating consideration of crypto-native risk factors.
Risk assessment
Despite the low beta of $HYPE, we adjusted its discount rate from 10.5% to 13% (more conservative compared to COIN's 13.6% and HOOD's 15.6%) for the following reasons:
Lower governance risk: Direct programming of 93% fee allocation reduces concerns associated with corporate governance. In contrast, COIN and HOOD do not return any earnings to shareholders, with capital allocation determined by management.
Higher market risk: $HYPE is a crypto-native asset, facing additional regulatory and technological uncertainties.
Liquidity considerations: Token markets are generally less liquid than mature stock markets.
Obtain market implied price (MIP)
Using the 13% discount rate we set, we can reverse engineer the earnings expectations implied by the current price of approximately $54 for the $HYPE token:
Current market expectations:
2025: Total revenue of $700 million
2026: Total revenue of $1.4 billion
Terminal growth: continuous growth of 3% per year thereafter
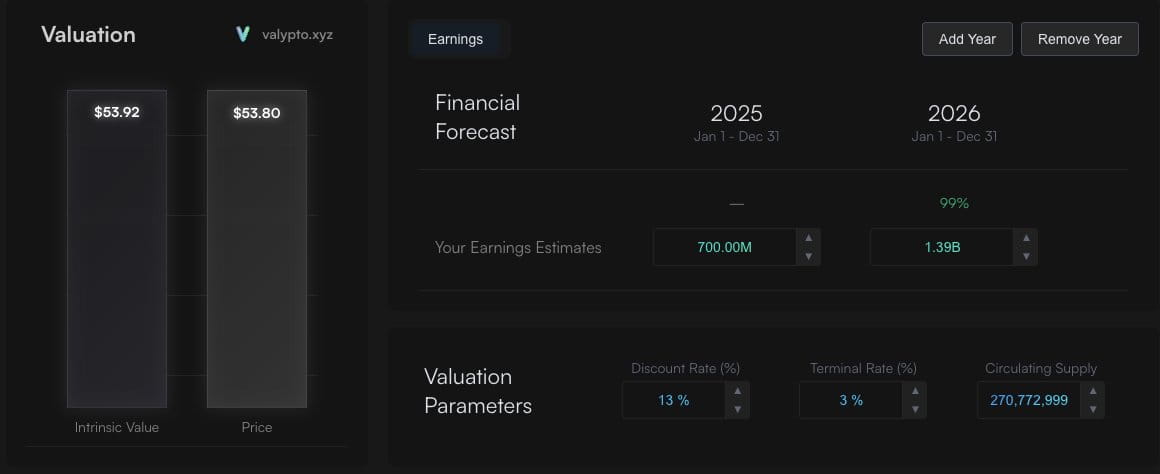
The intrinsic value derived from these assumptions is approximately $54, consistent with the current market price. This indicates that the market is pricing moderate growth based on the current fee levels.
At this point, we need to ask a question: does the market implied price (MIP) reflect future cash flows?
Alternative growth scenarios
@Keisan_Crypto proposed an attractive 2-year and 5-year bull market scenario.
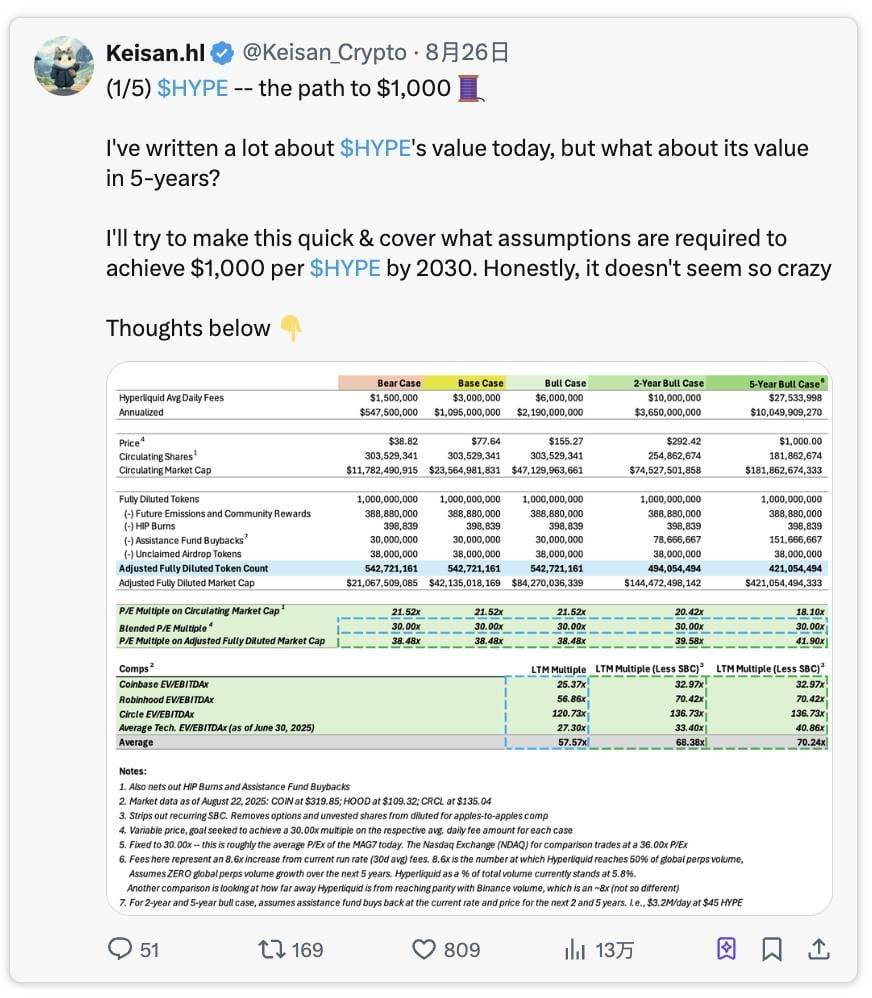
Original tweet link: Click here
Two-year bull market forecast
According to @Keisan_Crypto's analysis, if HyperLiquid reaches the following goals:
Annual transaction fees: $3.6 billion
Aid fund revenue: $3.35 billion (93% of fees)
Result: The intrinsic value of HYPE is $128 (undervalued by 140% based on the current price)
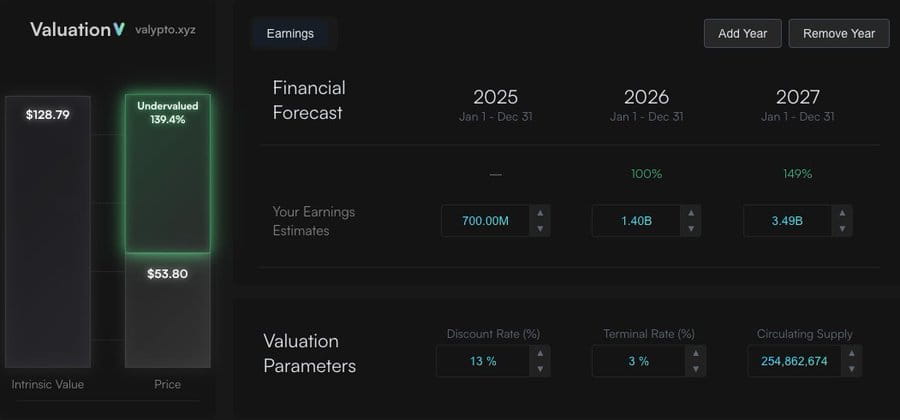
Related links
Five-year bull market scenario
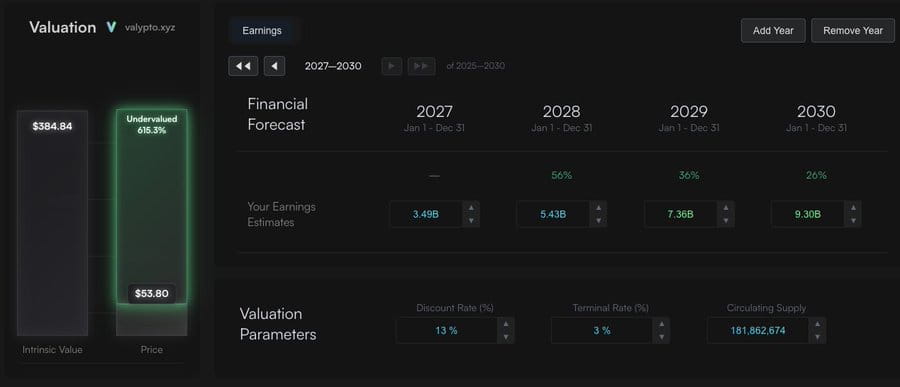
In a five-year bull market scenario (related links), it is predicted that fees will reach $10 billion per year, of which $9.3 billion belongs to $HYPE. It is assumed that HyperLiquid's global market share will grow from the current 5% to 50% by 2030. Even if the 50% market share is not reached, these figures could still be realized through small market shares as global trading volume continues to grow.
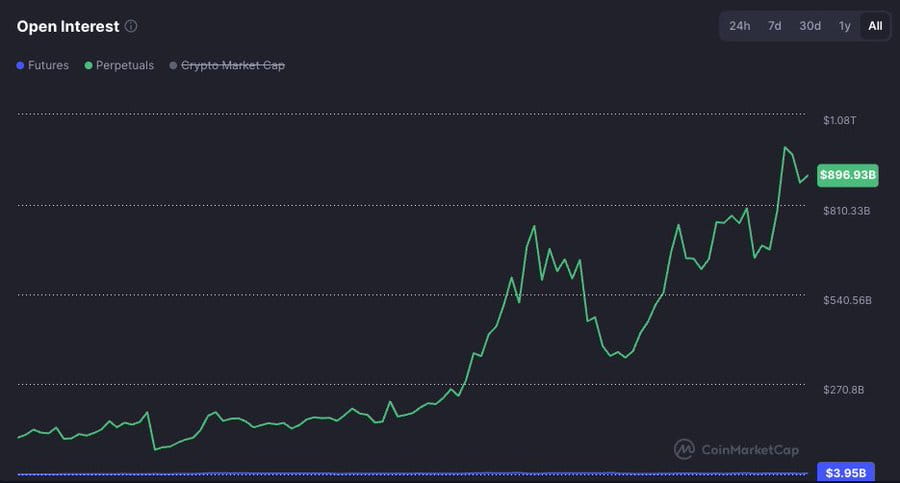
Five-year bull market forecast
Annual transaction fees: $10 billion
Aid fund revenue: $9.3 billion
Result: The intrinsic value of HYPE is $385 (undervalued by 600% based on the current price)
Related links
Although this valuation is below Keisan's $1,000 target, the difference arises from our assumption that earnings growth normalizes to 3% per year thereafter, while Keisan's model uses cash flow multiples. We believe there is an issue with predicting future value using cash flow multiples, as market multiples are volatile and may change significantly over time. Furthermore, multiples themselves incorporate earnings growth assumptions, and using the same cash flow multiple in 5 years as in 1-2 years implies that the growth level from 2030 onwards is consistent with the growth levels of 2026/2027. Therefore, multiples are more suited for short-term asset pricing. However, regardless of which model is used, $HYPE remains undervalued; it is just a matter of nuance.
Additional value drivers: USDH
Under the Native Market model, USDH will allocate 50% of stablecoin income for repurchases similar to the aid fund. Therefore, $HYPE can add $100 million (50% of $200 million) in free cash flow annually.
Looking ahead to the next five years, if USDH's market cap can reach $25 billion (which is still one-third of USDC currently, and even smaller in proportion to the total stablecoin market size five years later), then its annual income is expected to reach $1 billion. Using the same 50% allocation model, this would bring an additional $500 million in free cash flow to the aid fund each year. This would value each token at over $400.
Exclusion of value drivers: HIP-3 and HyperEVM
This DCF analysis intentionally excludes two important potential value drivers that are not suitable for cash flow modeling. Clearly, they would provide additional incremental value, and thus could be evaluated separately using different valuation methods and then added to this valuation result.
Summary
Our DCF analysis indicates that if HyperLiquid can maintain its growth trajectory and market position, the value of the $HYPE token is significantly undervalued. The unique feature of programmed fee distribution makes it particularly suited for cash flow-based valuation methods.
Methodology explanation
This analysis is built on the research findings of @Keisan_Crypto and @GLC_Research.
The DCF model is open source and can be modified at the following link:
https://valypto.xyz/project/hyperliquid/oNQraQIg
Market data and forecasts may change, and the model should be updated promptly based on the latest information.