


Author: TTx0x, Crypto KOL; Translation: Golden Finance Xiaozou
1. Introduction
Galaxy Digital (NASDAQ: GLXY) can be seen as an undervalued opportunity at the intersection of two powerful long-term trends—cryptography and artificial intelligence. The market is misassessing Galaxy, viewing it as a volatile crypto company while overlooking the immense value of its 'crown jewel' asset, the Helios data center. Helios is a world-class AI infrastructure platform expected to generate stable, high-margin, long-term cash flows.
The core of this investment view is that the market will ultimately re-rate GLXY due to its successful transformation from a digital asset service company to a top AI infrastructure operator. The recent 15-year main lease signed with AI supercomputing service provider CoreWeave—covering the currently approved 800 megawatts of total power for Helios—validates its business model and indicates an annual recurring revenue stream of approximately $720 million and an EBITDA profit margin of 90%.
Galaxy has a clear advantage over competitors attempting to pivot from 'Bitcoin miners to AI' primarily due to its fortress-like balance sheet with over $1.8 billion in net cash and investments, a management team with deep expertise, and a clear path to expand Helios to a potential 3.5-gigawatt campus.
2. Investment viewpoint: Unlocking top-tier AI infrastructure targets
(1) Core mispricing
Galaxy consists of two distinctly different business segments: traditional digital asset financial services and emerging AI data center infrastructure. However, the market currently evaluates GLXY through a single lens—namely, as a cryptocurrency company. GLXY's price movements remain highly correlated with Bitcoin, indicating that investors have yet to price in the tailwinds provided by its AI data center business.
(2) Unexpected acquisition opportunities
At the end of 2022, Galaxy acquired the Helios data center campus from Argo Blockchain for a mere $65 million through a distressed sale. At that time, Argo was facing bankruptcy and needed to liquidate assets. Galaxy obtained this world-class infrastructure asset at a price far below the current replacement cost. This transaction occurred before ChatGPT triggered a surge in AI-driven power and data center demand, repositioning Galaxy's growth trajectory for the next decade.
(3) Helios's strategic assets
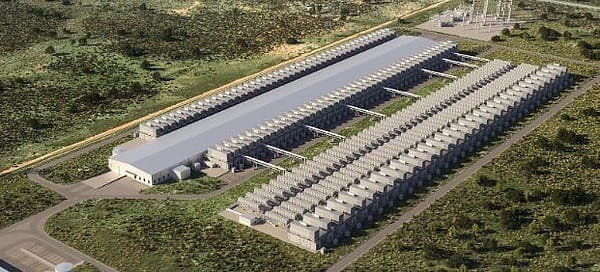
Helios is far from an ordinary data center; it is a first-class infrastructure asset designed to meet the demands of the AI revolution.
Power advantages:
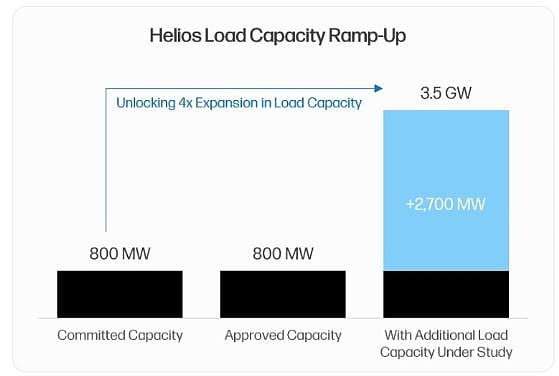
The biggest constraint facing the AI data center industry is power supply. Power contracts are the 'restrictive factor' that supercomputing service providers compete to deploy GPU capabilities. Helios has secured an 800-megawatt power contract with Texas power operator ERCOT, allowing tenants to bypass the usual new grid connection wait time of over 36 months. Furthermore, the campus has a clear expansion path, with an additional 1.7 gigawatts of capacity currently under load study, making the initial site's potential capacity reach 2.5 gigawatts. The latest announcement in Q2 2025 revealed that the company acquired adjacent land and submitted a 1-gigawatt grid connection application, raising the total potential power capacity of the campus to an astonishing 3.5 gigawatts, placing it among the largest data center sites in the world.
Scale and location advantages:
AI supercomputing service providers prefer centralized facilities to achieve economies of scale and performance advantages. Helios, as a single scalable campus, perfectly fits this model. Its geographical location in West Texas allows access to the cheapest and most reliable power resources in the U.S. Crucially, Galaxy is investing in building a long-haul fiber network to ensure a 10-15 millisecond transmission delay in the Dallas/Fort Worth metro area. This distinguishes Helios from the growing number of purely AI training facilities—its low latency connection characteristics unlock AI inference use cases, thereby ensuring premium pricing power.
Future-oriented design:
Any data center currently under construction faces the risk of becoming outdated within a few years. Galaxy mitigates this risk through a phased development plan, allowing for the integration of cutting-edge technologies in each new construction cycle. This includes advanced cooling solutions, such as direct chip liquid cooling, which are crucial for the next generation of GPUs. The campus's 10 million gallon freshwater retention pond supports these critical cooling needs.
(4) CoreWeave partnership
The partnership with CoreWeave is the most important validation of Galaxy's AI data center strategy. In Q2 2025, CoreWeave committed to leasing all of Helios's currently approved 800 megawatts of total power.
Transaction economics:
Its 15-year triple net lease agreement is highly attractive. The first 600 megawatts of power are expected to generate approximately $720 million in annual revenue (including a 3% annual increase clause). Due to the triple net lease structure (the tenant bears all operating costs), this revenue is expected to convert to EBITDA with a profit margin of up to 90%.
Risk resolution and value validation:
This milestone agreement achieves several key objectives. First, it provides long-term predictable cash flow visibility, reducing Galaxy's financial risk. Second, it strongly validates Galaxy's operational capability, establishing the company as a reliable partner. This is crucial for attracting other hyper-scale tenants—who prefer partners with a verified track record.
3. Galaxy's traditional business: a profitable cornerstone with synergy effects
Common bearish viewpoints on Galaxy suggest that its traditional cryptocurrency business is a negative asset that increases volatility and risk. This view is misguided. In fact, Galaxy's digital asset business is a highly profitable, market-leading entity that provides capital and credibility synergies for its other businesses.
Galaxy's digital asset business mainly consists of two major units: global markets (including institutional trading, lending, and investment banking services) and asset management and infrastructure solutions (including a series of asset management products and on-chain services such as staking).
Its Q2 2025 financial data confirms the strong profitability of this business:
After adjustments, the gross profit of the digital assets segment reached $71.4 million, a 10% quarter-over-quarter increase;
The global market outperformed the market, with institutional loan accounts growing by 27% to $1.1 billion, indicating increased demand for its credit products;
The investment banking business demonstrates its strength in M&A advisory, serving as the exclusive financial advisor in Bitstamp's acquisition by Robinhood;
Assets under management and infrastructure solutions platform total assets grew by 27% quarter-over-quarter to nearly $9 billion;
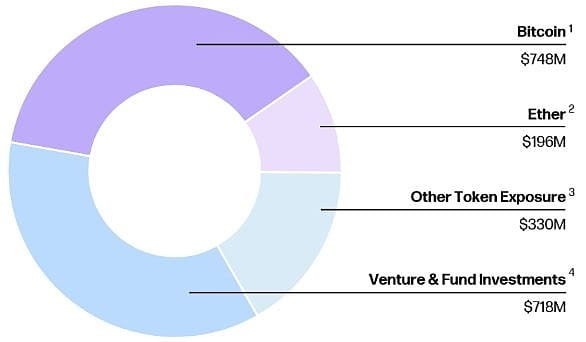
The Q2 balance sheet shows holdings of $1.18 billion in cash and stablecoins, as well as $1.27 billion in digital assets (primarily BTC and ETH).
Galaxy's profitable digital asset business not only generates cash flow but also strengthens its balance sheet, enabling the company to self-fund the significant equity contribution required for Helios's construction. Moreover, this business segment has proven its ability to execute large-scale complex transactions—such as the recent sale of over 80,000 Bitcoins (worth over $9 billion) to a single client. All these attributes assure potential supercomputing clients that Galaxy is an experienced, reliable, and well-capitalized partner capable of delivering multi-billion dollar infrastructure projects. This synergy creates a powerful self-reinforcing cycle between the two business segments.
4. Competitive landscape: The leader in AI transformation
Galaxy Digital is often confused with the group of Bitcoin miners attempting to pivot their assets toward AI computing hosting services. However, the following comparison shows that Galaxy stands out as the most attractive investment in this theme. The competitive landscape can be divided into two tiers: companies that have signed AI agreements (such as Core Scientific, TeraWulf) and those that merely claim strategic intent (such as IREN, Hut 8, Riot). Compared to signed peers, Galaxy demonstrates clear advantages across all key dimensions.
Galaxy's leading position in key dimensions is specifically reflected in:
Agreement attractiveness: The lease between Galaxy and CoreWeave has better economics. Its annual rental income per megawatt is higher ($1.8 million compared to $1.4-1.6 million), EBITDA profit margin is better (90% compared to 75-80%), and it includes a 3% annual rent increase clause that competitors lack.
Balance sheet strength: Galaxy has $1.8 billion in net cash and investments. In contrast, competitors like CORZ and WULF bear significant net debt burdens—CORZ recently emerged from bankruptcy restructuring, while WULF avoided a similar fate through significant equity dilution. These competitors' mining businesses continue to consume cash flow, while Galaxy's traditional business remains profitable.
Expansion capability: The potential capacity of a single Helios campus is 3.5 gigawatts, which dwarfs the scattered and limited power capacity of its competitors, allowing Galaxy to capture a larger share of future demand.
Strategic focus: Galaxy has made a strategic decision to completely exit the Bitcoin mining business, dedicating 100% of its efforts to AI data center opportunities. Competitors, on the other hand, are attempting to adopt a hybrid model, spreading attention and capital across two distinctly different businesses.
5. Helios valuation analysis
Helios's data center business should be valued against other top publicly listed data center REITs (Real Estate Investment Trusts) and recent private market transactions. Publicly comparable companies like Digital Realty and Equinix trade at multiples of about 25x adjusted EBITDA. Private merger and acquisition transactions for data center assets also achieve similar multiples.
Baseline scenario (only currently approved 800 megawatts):
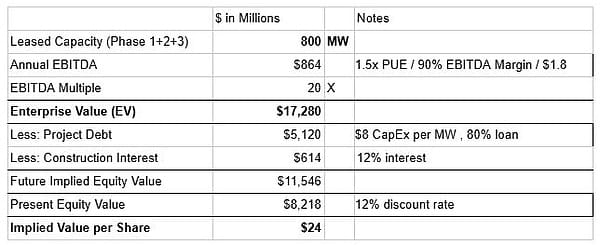
Assuming only the currently approved 800 megawatts are leased at an average price of $1.8 million per megawatt. Applying a 20x EBITDA multiple, this would generate approximately $17.28 billion in enterprise value. After deducting approximately $5.73 billion in project-level debt and interest, Helios's corresponding equity value would be about $11.54 billion. Since we expect this year's EBITDA to be realized in 2028, we apply a 12% discount rate, resulting in a present value equity value of $8.2 billion, or $24 per share.
Bull market scenario (as of FY2026, leasing 1,600 megawatts):
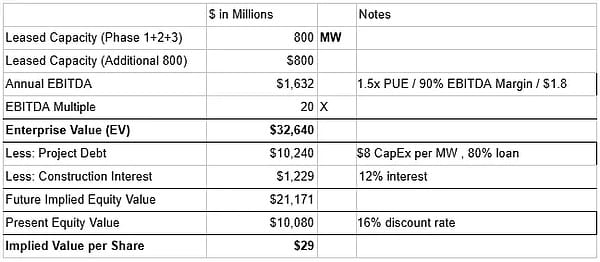
Assuming the subsequent 800 megawatts of power expected to be approved in Q4 2025 is leased at an industry average of $1.6 million per megawatt. A total of 1,600 megawatts would generate approximately $1.63 billion in annualized EBITDA. Applying a 20x multiple yields about $34.5 billion in enterprise value. After accounting for about $11.46 billion in project-level debt and interest, Helios's corresponding future equity value would be approximately $21.1 billion. Since we expect the 1,600 megawatts capacity to be fully operational by 2030, we apply a higher discount rate of 16% to account for additional execution risk. This results in a current equity value of $10.01 billion, or $29 per share.
GLXY's current trading price is approximately $24 (as of September 2, 2025). The baseline scenario for the Helios project has already reached a per-share valuation of $24. Our valuation has not included the traditional digital asset business profits of Galaxy. Bullish recently completed its IPO at a valuation of $5.4 billion, despite reporting a net loss in Q1 2025. If Galaxy's digital asset business valuation approaches Bullish's IPO valuation, this alone could add about $8-10 to the per-share value.
6. Key risks and mitigation factors
(1) CoreWeave tenant concentration and credit risk
The most prominent bearish argument centers on the concentration risk associated with the single tenant, CoreWeave, and the questioning of credit reliability due to its debt burden and lack of investment-grade rating.
Risk mitigation: CoreWeave's business model has high revenue visibility, with 96% of its revenue coming from long-term committed contracts. Its debt mainly consists of delayed draw term loans, specifically used to finance growth capital expenditures based on signed customer contracts. This credit has been fully underwritten by mature investors such as Blackstone—who led significant financing arrangements for CoreWeave. Additionally, CoreWeave has built a durable moat through a strategic alliance with Nvidia, allowing it to prioritize access to the latest GPUs and be the only operator capable of meeting the scale demands of top AI labs like OpenAI with its 'Neocloud'.
(2) Project execution and timeline risks
The renovation and expansion of Helios is a complex multi-billion dollar infrastructure project with significant execution risks.
Risk mitigation: Galaxy's management team (especially Chief Investment Officer Chris Ferraro) has deep expertise in project financing and capital markets, which can alleviate this risk. The company's strong balance sheet (recently bolstered by approximately $500 million in financing) provides significant financial cushion for unexpected costs or delays. The phased development strategy lowers risk by breaking projects down into manageable stages.
(3) Regulatory and grid risks
Future expansions beyond currently approved capacity may face scrutiny or delays from Texas grid operator ERCOT—this agency is closely monitoring new large load connection requests.
Risk mitigation: Galaxy's existing 800 megawatts of approved access capacity is a significant de-risked asset, shielding it from the maximum bottleneck faced by new projects. This approved power is secured. Furthermore, Texas regulators generally have a pro-business and anti-regulatory stance, providing significant benefits for future growth compared to more restrictive jurisdictions.
7. Conclusion
In summary, Galaxy Digital is an undervalued investment opportunity. The market continues to evaluate GLXY through the narrow lens of volatile cryptocurrency proxies, failing to recognize its fundamental transformation into a top-tier AI infrastructure provider.
The core of this investment thesis lies in the Helios data center—this world-class asset hedges risk through a milestone 15-year triple net lease signed with supercomputing giant CoreWeave. This partnership not only ensures a predictable high-margin revenue stream but also validates Galaxy's status as a trusted partner in achieving its ambitious future expansion plans.
Our valuation analysis indicates that the Helios asset alone supports the current stock price. Its profitable traditional digital asset business continues to differentiate it from other 'AI transformation' competitors, prominently reflected in its fortress-like balance sheet, diverse non-correlated revenue streams, and highly focused management team. While there are risks related to tenant concentration and project execution, Galaxy's experienced management and robust financial position offer effective mitigation. As the company executes its clear roadmap and the market gradually absorbs the scale and stability of Helios's cash flows, we expect its stock to undergo a value reassessment.