

Original | Odaily Planet Daily (@OdailyChina)
Author | Ding Dong (@XiaMiPP)
The beginning of 2026 dealt a heavy blow to DAT (Digital Asset Treasury) companies.
BTC has retraced from a peak of 120,000 USD in 2025 to around 60,000 USD, a decline of nearly 50%. ETH has also not been spared, falling below the 2,000 USD mark, nearly erasing all gains since May 2025. This was precisely the time when a group of DAT companies, represented by SharpLink and Bitmine, publicly announced strategic transformations and made significant allocations to crypto assets.
What does this mean? It means that those listed companies or institutions that once regarded BTC and ETH as 'corporate strategic reserves' have now collectively fallen into a state of unrealized losses, with paper losses easily exceeding hundreds of millions or even billions of dollars. Leading players like Strategy and Bitmine are still gritting their teeth to increase their holdings, attempting to maintain the narrative stability of being 'long-term believers'; however, more small and medium-sized or highly leveraged DAT companies have begun to show substantial reductions in holdings or even phased liquidations.
Crypto has never lacked stories; if 2025 was the year 'writing faith into financial reports', then 2026 is the test of 'how faith can survive the bear market'. When prices pull back, leverage tightens, and the financing environment reverses, can these DAT companies still sustain their balance sheets?
Odaily Planet Daily will break down several representative cases that have already begun 'selling coins to stop the bleeding', examining how much they sold, why they sold, and where they will go after selling.
Cango Inc. (NYSE: CANG): The leverage limit of the mining model.
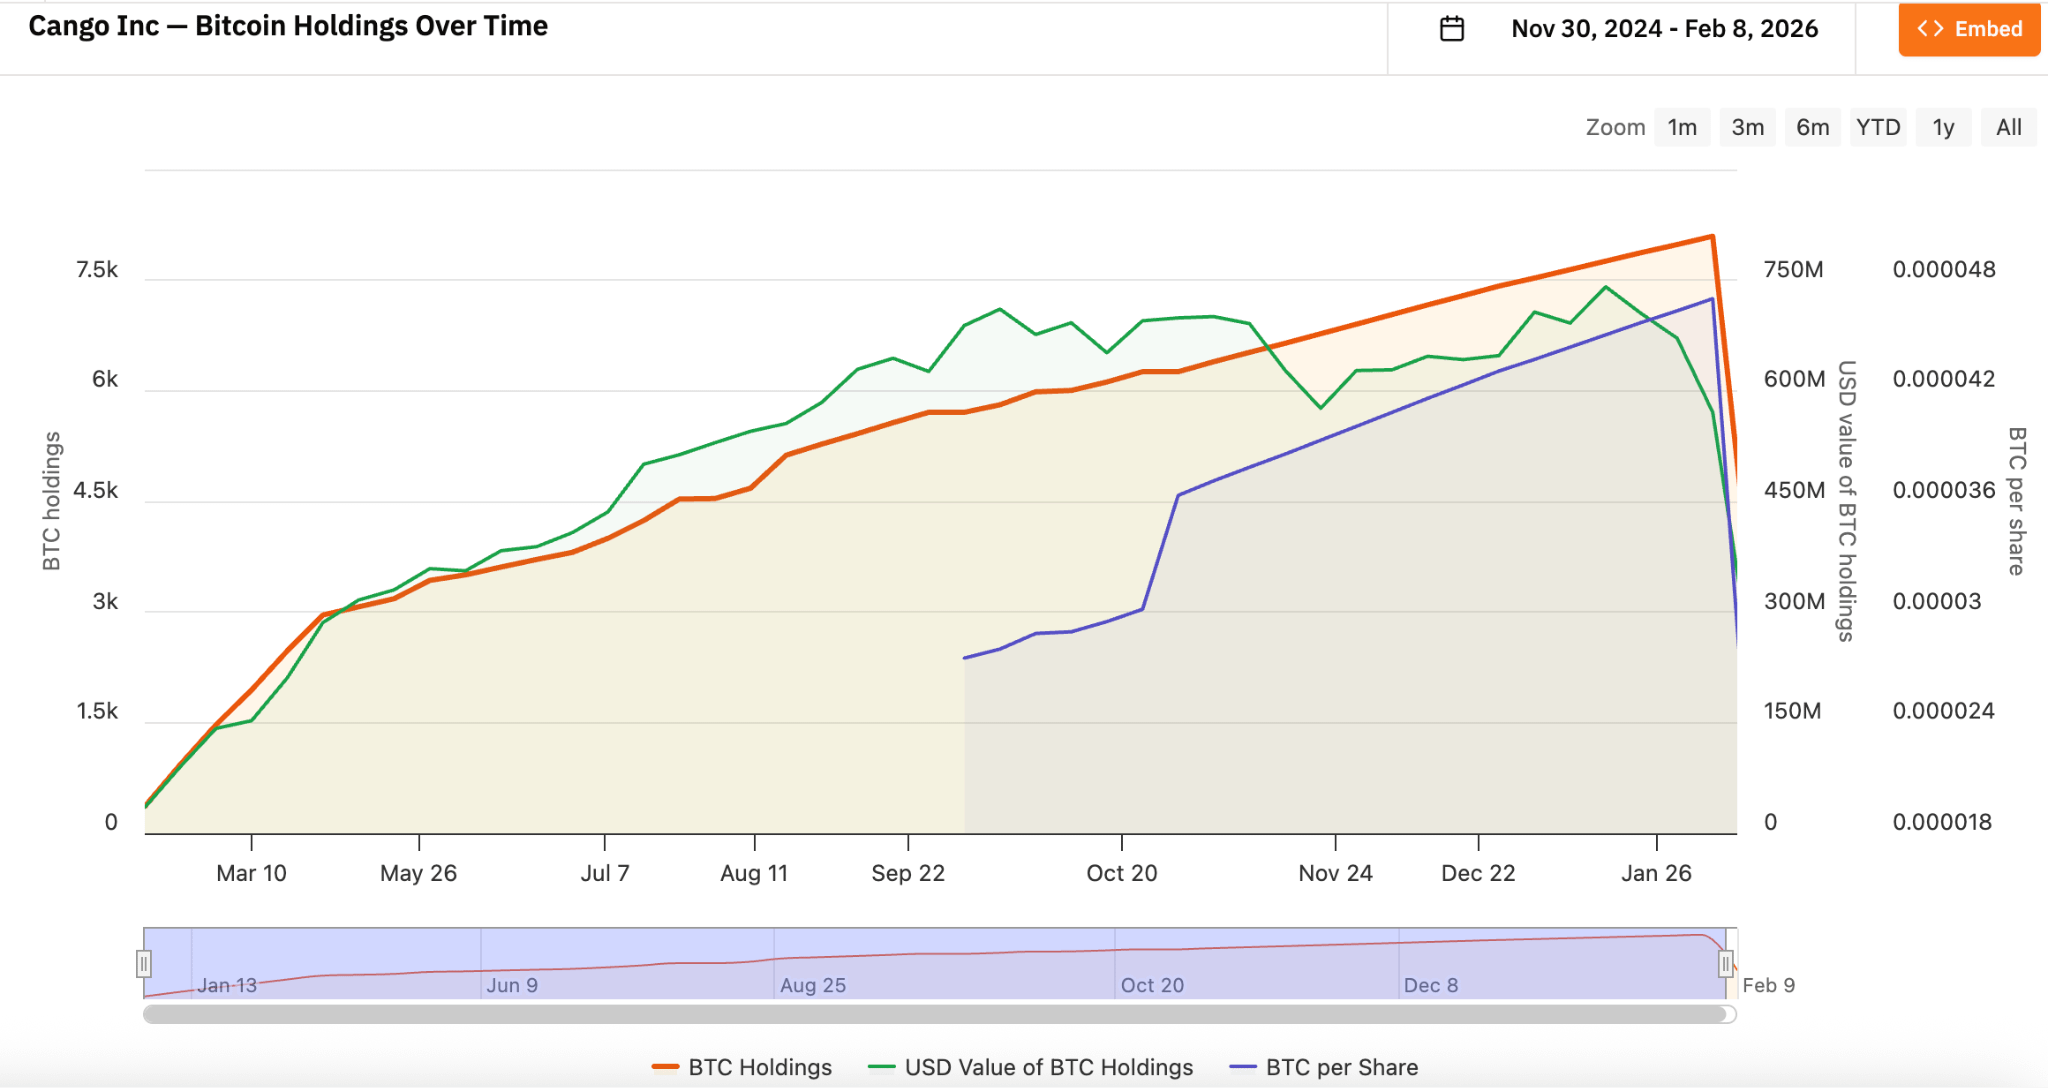
February 9, Cango disclosed that it has sold 4,451 bitcoins on the open market, with a net profit of approximately $305 million, and will use all the funds to repay a loan secured by BTC. This transaction size is close to half of its previous holdings, leaving only 3,645 BTC on the books after the sale.
Cango was founded in 2010 and is headquartered in China. Initially, it was a well-known automotive trading service platform. Since November 2024, Cango has officially entered the digital asset field, transforming into a bitcoin mining company through business restructuring and strategic shift, viewing BTC as the company's core reserve asset. Cango's bitcoin strategy early on leaned towards HODL + mining accumulation, meaning not selling coins but continuously increasing holdings through computing power. This model can self-reinforce during price upswings: rising coin prices enhance asset net worth, increased asset net worth boosts financing capability, and financing capability in turn supports computing power expansion.
Cango has been continuously accumulating bitcoins since November 2024, and its bitcoin holdings were once the second largest mining company in the world, second only to MARA Holdings.
Related reading (Exploring potential crypto stocks: How can Cango leap from an automotive company to become the world's second-largest bitcoin mining company?)
However, mining is inherently a leveraged industry. Equipment procurement, mining site construction, and power contracts all require upfront capital expenditure, while mining companies often use their BTC as collateral to obtain equipment from manufacturers and delay payments, or borrow USD/stablecoins from institutions/platforms to expand mining sites, procure equipment, and maintain operations. The downside of this model is that when the BTC price significantly corrects, the collateral ratio deteriorates rapidly, amplifying leverage risks, while fixed costs such as electricity, maintenance, and equipment depreciation do not decrease, leading to extreme cash flow pressure.
According to the third-quarter data released in December 2025, Cango's average mining cost (including depreciation) is approximately $99,000 per coin, while the cash cost excluding depreciation is about $81,000 per coin. The bitcoin price is far below its shutdown price, forcing it to 'stop the bleeding' by reducing BTC to improve its balance sheet and reduce financial leverage.
It is worth noting that Cango has announced that it will shift some resources towards artificial intelligence computing infrastructure, seeking business diversification to reduce dependence on the price of a single asset.
Empery Digital Inc. (NASDAQ: EMPD): The reverse pressure of bull market financing logic.
Empery Digital was founded in February 2020 (originally named Frog ePowersports Inc., later renamed Volcon Inc.) and is headquartered in Texas, USA. It was originally a company focused on fully electric off-road powered vehicles.
In July 2025, the company announced its bitcoin treasury strategy. Looking back now, this timing coincided closely with the peak of the current bitcoin price cycle. The company raised approximately $450-500 million through private placements and credit financing, gradually increasing its holdings by about 4,000 bitcoins between July and August 2025, with an average cost of around $117,000 per coin. Based on current prices, the unrealized loss is close to 57%.
On February 6, Empery Digital announced the sale of 357.7 BTC at an average price of approximately $68,000 per coin, raising about $24 million to fund stock buybacks and repay part of its debt. It has now repurchased over 15.4 million shares at an average price of $6.71, aiming to narrow the NAV discount. Currently, Empery has approximately 3,724 bitcoins remaining.
The case of Empery Digital actually reflects the typical dilemma faced by small and medium-sized DATs. They initially underwent aggressive transformations and relied on bull markets for financing, but when prices corrected, they were forced to 'sell coins for buybacks + deleverage'. Compared to Cango's mining background, Empery feels more like 'pure financial play'. Its original main business is unsustainable, so it borrowed heavily to buy BTC at high prices during the bull market, attempting to replicate the Strategy-style path, but the significant pullback in BTC exposed its leverage risks, and it lacks the space for long-term issuance and capital market operations. Once prices continue to pull back, ongoing reductions almost become an inevitable option.
Bitdeer Technologies Group (NASDAQ: BTDR): From price speculation to prioritizing cash flow.
Bitdeer was established in December 2021 by crypto OG Wu Jihan (former co-founder of Bitmain) and is listed alongside MARA and Riot as a major global bitcoin mining company.
Bitdeer provides a full-chain solution from equipment procurement, logistics, data center design/construction, equipment management to daily operations through a vertically integrated model, while also expanding into cloud computing, hosting services, and self-developed ASIC mining machines. This has shifted Bitdeer's business from pure mining to diversified high-performance computing, buffering the impact of bitcoin price fluctuations to some extent.
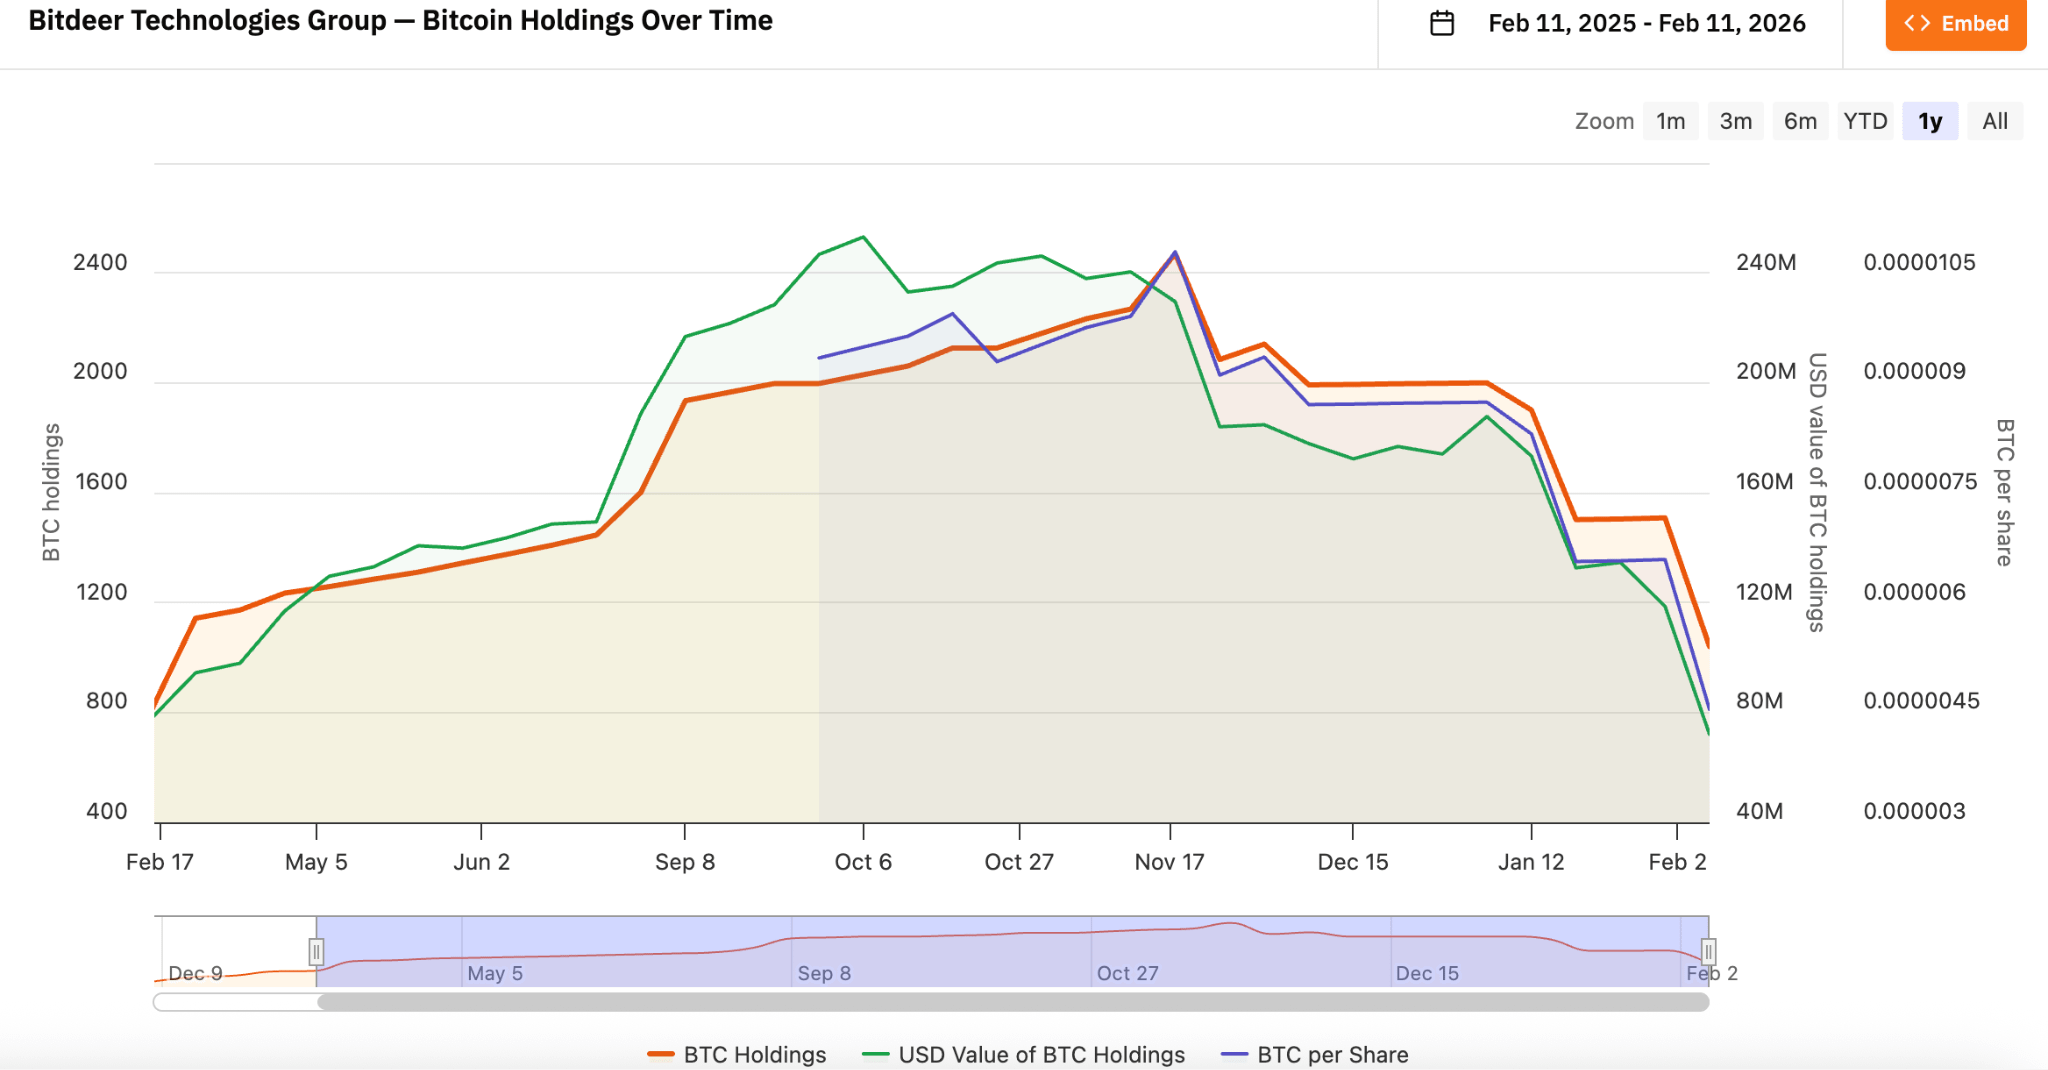
According to data from bitcointreasuries.net, since November 2025, Bitdeer's BTC strategy has shifted to 'mining and selling', no longer fully HODLing, but maintaining cash flow and operational stability through partial monetization. Prioritizing cash flow over long-term holding reflects the industry's sensitivity experienced through multiple cycles of bull and bear markets.
Sequans Communications S.A. (NYSE: SQNS): Selling coins to repay debts has become a turning point for the industry.
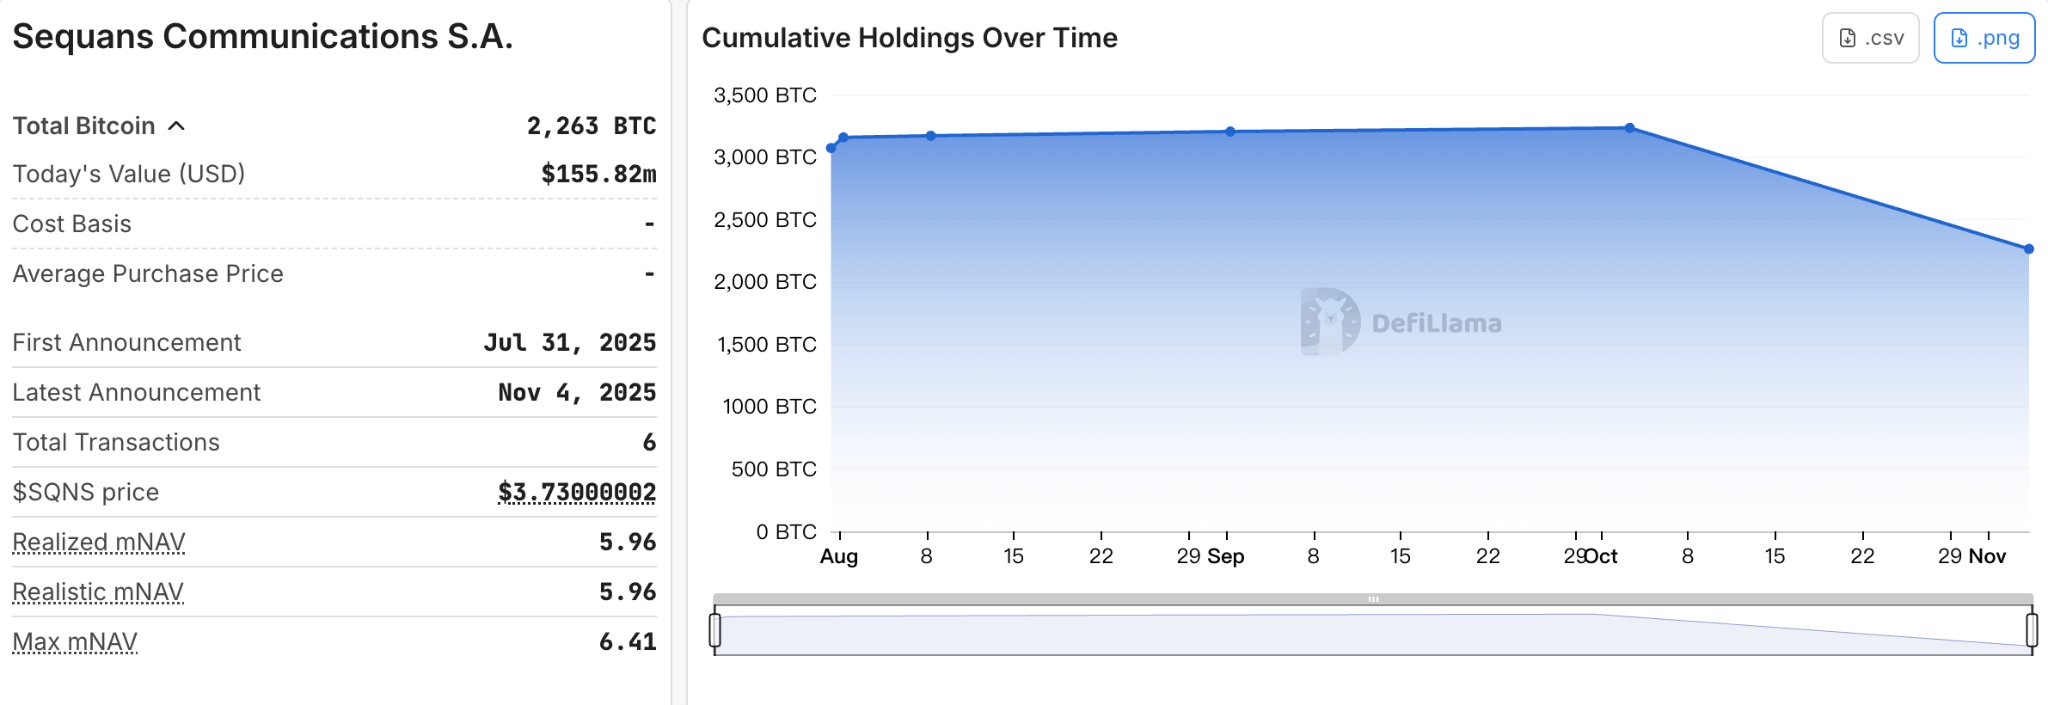
Sequans was founded in October 2003 and was originally a semiconductor company focused on wireless cellular technology chips and modules. In June 2025, the company raised approximately $380 million through private equity and convertible bonds to accumulate bitcoins, transforming itself from a pure IoT chip manufacturer to a hybrid of 'IoT + BTC DAT'.
Between July and October 2025, Sequans accumulated an additional 3,233 bitcoins, roughly estimating the average cost at around $116,000.
In November 2025, it made its first large reduction, selling 970 BTC, to redeem approximately 50% of its convertible bonds, reducing the company's total debt from $189 million to $94.5 million. The company referred to this as 'strategic asset redistribution', not a surrender strategy. However, the market views Sequans as the starting point of the BTC treasury 'bubble burst'—the first publicly acknowledged DAT company that needs to sell coins to pay debts.
ETHZilla Corporation (NASDAQ: ETHZ): A sample of deleveraging in the ETH treasury.
ETHZilla Corporation was originally a clinical-stage biotechnology company focused on drug development and treatment for chronic pain, inflammation, and fibrosis. The company faced issues such as cash shortages, poor liquidity, and slow R&D progress, leading to a prolonged decline in stock price.
In August 2025, it raised $425-565 million through private placements, with investors including Electric Capital, Polychain Capital, GSR, and others, as well as Peter Thiel-related entities holding approximately 7.5%. This funding was directly used to purchase ETH, establishing an Ethereum treasury. At its peak, ETHZilla had increased its holdings to approximately 102,000 ETH, valued at about $210 million, with an average acquisition cost of $3,841.
On November 13, 2025, ETHZilla began its first reduction of 8,293 ETH; on December 25, ETHZilla disclosed that it had sold 24,291 ETH, raising approximately $74.5 million. This transaction was part of redeeming outstanding senior secured convertible notes and is the first sample of ETH treasury reduction. Currently, ETHZilla's ETH holdings are approximately 65,700.
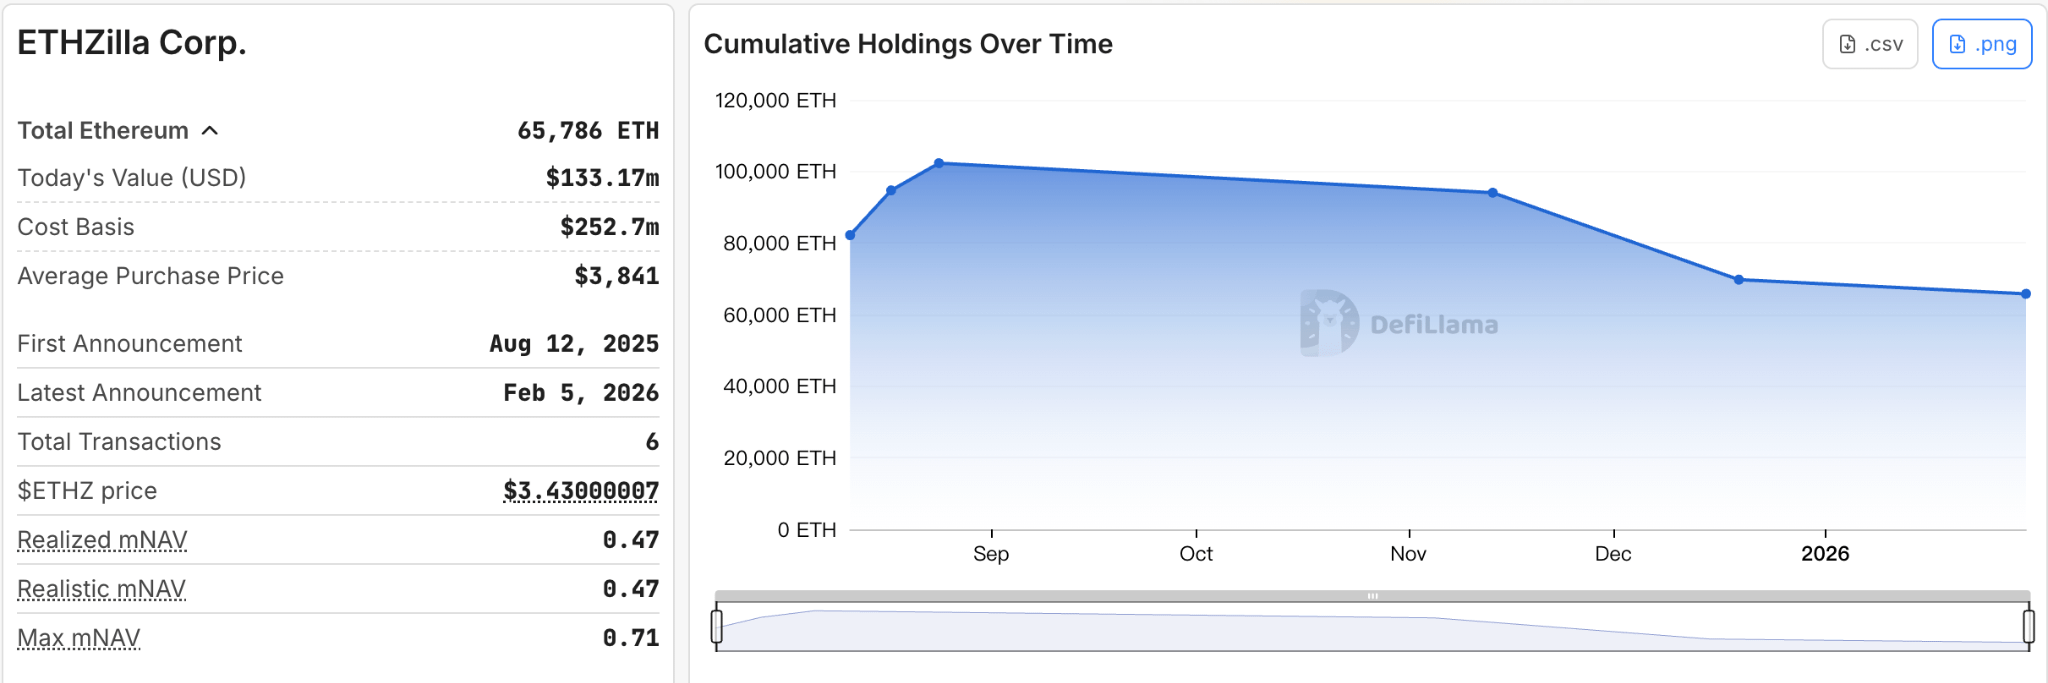
Similar to Empery, ETHZilla is also forced down the path of selling coins to deleverage. However, the company is accelerating its transformation towards RWA (Real World Asset Tokenization), focusing on areas such as auto loans, home loans, and land/commercial real estate, and expects to launch its first RWA token product in early 2026, attempting to reshape value through business innovation.
Conclusion
The above are just a few representative samples, most of which are in the middle range of the industry, neither having the capital market pricing power of Strategy nor the ability to quietly exit the stage like the smallest companies. Beyond them, some smaller and structurally weaker DAT companies have already quietly disappeared in this round of pullbacks; others that originally planned to transform and had not yet truly implemented treasury strategies have chosen to hit the pause button after the financing environment tightened suddenly, or even announced termination before their projects had started.
The correction in 2026 was like a mirror reflecting the fragility and resilience of the DAT model. Companies that relied solely on 'storytelling + leverage' are now paying the price for their aggressive expansion. Crypto faith may still exist, but it ultimately needs to coexist with the realities of cash flow, leverage management, and business sustainability.
The gap between leading players and small and medium-sized companies is continuously widening in this process. Rather than saying this is the end of the DAT model, it is more accurate to say it is the starting point for its entry into a layered phase.