

Written by: Thejaswini M A
Translated by: Block unicorn
Foreword
Anatoly Yakovenko was furious.
That was in 2017 when it was reported that the Bitcoin conference would stop accepting Bitcoin payments because the transaction fees had surged to $60-70.
The world's premier cryptocurrency conference was unable to accept cryptocurrency.
So, he did what any frustrated engineer would do. He went to Café Soleil in San Francisco, ordered two coffees and a beer, and stayed up until 4 a.m. pondering why Bitcoin was so slow.
In between his second espresso and last sip of beer, Yakovenko suddenly had an epiphany, which he called a 'moment of insight.' He suddenly thought of a way to encode the passage of time as a data structure.
He didn’t know that this function had a name (verifiable delay function), so he couldn’t Google it. He thought he had invented something entirely new.
In a sense, he did.
When Solana launched in 2020, it could handle 65,000 transactions per second. Today, the blockchain Yakovenko built in his garage peaked with a valuation of over $50 billion.
The Growth Path of a Systems Thinker
Yakovenko's blockchain journey began with an early immigrant story. Born in Ukraine in 1981, he moved to the United States with his family in the early 1990s, joining the wave of Eastern European immigrants seeking opportunities in the American tech boom.
As a teenager, he became fascinated with the C language, captivated by the precision and power of low-level systems programming. 'The possibility of writing a piece of code that could solve a significant problem in the world was just magical,' he later recalled about his early programming days during the internet bubble.
At the University of Illinois at Urbana-Champaign, Yakovenko studied computer science and founded his first startup, Alescere, in the early 2000s, a VoIP system aimed at small businesses. The company failed, but it provided him with valuable experience in real-time networking protocols.
In 2003, fresh from his experience at a startup, Yakovenko joined Qualcomm in San Diego. He initially started as a regular engineer but went on to tackle the most challenging technical problems the company faced over 13 years.
He worked on a variety of projects from QChat's push-to-talk server to the BREW mobile operating system, eventually becoming a senior engineering manager. He also optimized communication methods between different processors. Yakovenko became an expert in 'extending operating system services and protection domains securely to auxiliary processors,' essentially figuring out how to make different parts of computer systems work together without slowing each other down.
The patent portfolio from this period was like a blueprint for his later blockchain work: 'Exposing host operating system services to auxiliary processors' and 'Extending protection domains to coprocessors.' His work focused on minimizing overhead and improving coordination efficiency between distributed components.
'I started thinking about how we solved these scalability issues at Qualcomm using wireless protocols, which led me to dive deep into this field,' he said.
The cellular tower technology he worked on utilized a method called time-division multiple access, coordinating multiple signals by precisely managing time. In 2017, after over a decade at Qualcomm, Yakovenko began working at Dropbox on compression and distributed systems. But what truly changed everything was his side project.
He and Qualcomm's GPU head, Stephen Akritch, built hardware for deep learning and cryptocurrency mining to offset costs. It was originally about machine learning, not blockchain innovation.
But when Yakovenko observed their mining equipment coordinating with thousands of other computers, one question nagged at him: Why was proof of work so inefficient?
Bitcoin's transaction fees have skyrocketed to $60-70 per transaction. This network, which was supposed to be peer-to-peer electronic cash, can't even handle basic payments. The Bitcoin conference further fueled his frustration.
It was at that moment that Café Soleil's moment occurred.
Proof of Historical Breakthrough
Imagine: 10,000 people trying to agree on the timing of something, everyone shouting at each other; it’s chaos.
This is essentially how Bitcoin works. But the problems with Bitcoin are far more complex than just noise.
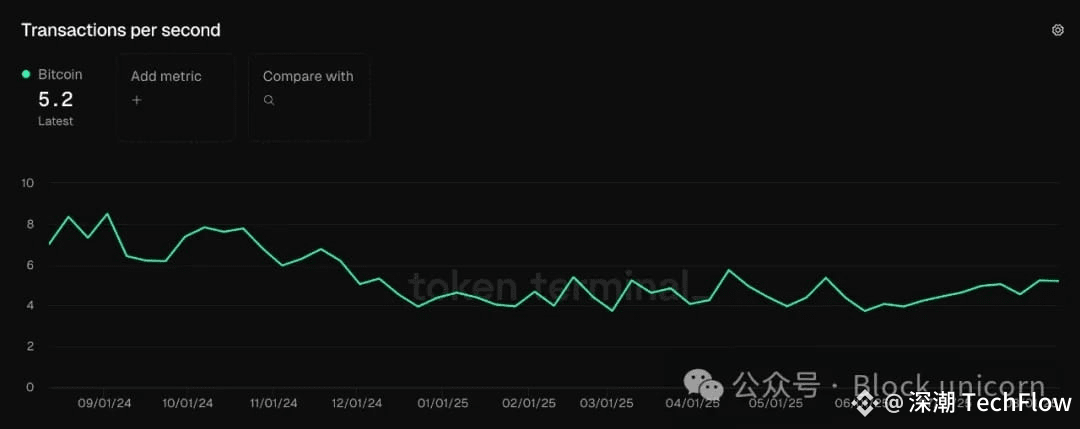
Bitcoin creates a new block every 10 minutes, representing a careful balance between security and speed. If it's too fast, the network could split into competing versions; if it's too slow, transactions take too long. This 10-minute rhythm means Bitcoin can only process about 7 transactions per second.
In contrast, Visa processes about 24,000 transactions per second.

The real problem is that in a distributed system with thousands of computers worldwide, there is no central clock. Each computer's clock runs slightly differently. Network message transmission takes time. The order of events appears different depending on the observer's location.
Thousands of Bitcoin computers spend most of their time debating some basic questions: 'Did this transaction happen before that one?' 'When was this block created?' 'Which version of the blockchain is correct?'
The more computers that joined, the more intense the arguments became.
Yakovenko had an idea: What if there was no need to argue about time?
What if the blockchain had a built-in unforgeable clock? Each transaction would automatically receive a timestamp that anyone could independently verify.
There was no longer a need for thousands of computers to constantly send messages to reach a consensus on time; they just needed to look at the same unforgeable clock to instantly know the order of events.
No more endless back-and-forth messaging; just a cryptographic stopwatch that keeps perfect time.
He called it 'Proof of History.'
Use computation instead of debate. There is no longer a need for thousands of conversations about time; just look at the clock. Simple and clear.
Building Solana
With this breakthrough, Yakovenko co-founded Solana Labs in 2018 with Greg Fitzgerald (another Qualcomm veteran) and Raj Gokal. The name is derived from their experiences surfing at Solana Beach in California.
The co-founders would wake up in the morning to surf, bike to work, code all day, and then return to the beach.
They built projects during the crypto winter of 2018-2019 when funding was scarce and enthusiasm waned. But Yakovenko saw it as an advantage. They could focus on engineering without facing hype and pressure.
'It was like the meteor that killed the dinosaurs. It was indeed a crypto winter, and you saw many teams disband. We’ve always been relatively conservative and never raised large amounts of money. Our runway was only about two years, so we were always thinking, 'We need to get this right as quickly as possible and really focus on the key products we believe will make a difference,' he recalled.
The team not only built Proof of History but also created a whole suite of innovations supporting high throughput:
Sealevel: A parallel smart contract runtime that allows the blockchain to run multiple transactions simultaneously by pre-declaring the accounts involved.
Turbine: A system inspired by BitTorrent that uses erasure coding and randomly weighted trees to propagate transaction data across the network.
Gulf Stream: A transaction forwarding system without a memory pool that sends transactions to future leaders before block generation.
Cloudbreak: A horizontal account storage system designed for high concurrent access.
Each innovation targets different bottlenecks. Together, they create something unprecedented: a blockchain that gets faster as it scales.
On March 16, 2020, the world was in chaos. Stock markets crashed, countries locked down, and startups collapsed. Yakovenko chose that day to launch Solana. Within months, it proved to be the perfect timing to launch the fastest blockchain in the world.
By the end of 2020, Solana processed 8.3 billion transactions, created 54 million blocks, and attracted over 100 projects across DeFi, gaming, and Web3 integration. Validator nodes expanded to over 300 globally, which is impressive for a network that had been established for less than a year.
Developers began building applications that were impossible to realize on slower blockchains. High-frequency trading systems, real-time games, and social media platforms became possible for the first time in blockchain history.
Interrupting Time
Success brought new challenges. Solana's high throughput made it a target for adversarial traffic, exposing its systemic weaknesses.
On September 14, 2021: A surge in transactions during the Grape IDO led to a network fork, resulting in a 17-hour outage.
May 1, 2022: An NFT 'blind mint' bot caused a consensus collapse, taking the network offline for 7-8 hours.
May 31, 2022: An error in offline transaction processing caused a 4.5-hour outage.
October 1, 2022: A configuration error caused a 6-hour outage.
Critics point out that these events demonstrate that Solana sacrificed decentralization for speed. Its monolithic design means that once something goes wrong, the consequences can be severe.
The team responded with systematic improvements: better deduplication handling, improved random number handling, fixing fork selection errors, and introducing the QUIC protocol to enhance network reliability.
In November 2022, Solana faced its biggest test—FTX's collapse.
Sam Bankman-Fried was once one of the most prominent supporters of Solana. When his exchange FTX collapsed, panic spread quickly. Investors believed anything associated with FTX would fail, and Solana's token price plummeted as people rushed to sell.
The Solana community did not wait for others to solve the problem.
FTX controlled a popular trading platform, Serum, that many Solana users depended on. When FTX collapsed, the platform effectively became an 'orphan,' with no one knowing its fate.
Within hours, Solana's developers and community members swiftly took action. They copied all the code from Serum and created a completely independent version called OpenBook.
The technical term is 'fork,' meaning a new version with the same functionality but without the issues of ownership has been created.
Throughout the crisis, Solana itself never stopped running.
Despite price crashes and panic spreading, the blockchain continued to process transactions. No outages. No technical failures.
Unlike traditional companies that might collapse if their CEO is arrested, Solana has grown beyond any individual or company that supports it. This technology and community can survive independently.
Vision for the Future
At 44, Yakovenko has achieved extraordinary milestones while maintaining a unique blend of engineering pragmatism and crypto idealism, which is a hallmark of successful blockchain founders.
He advocates for 'reasonable rules,' such as lawmakers trying to use the technology before regulating it.
Strangely, despite hoping for crypto-friendly policies, he opposed the government crypto reserve plan proposed by Trump. He felt it was too centralized, and this principled stance prompted skepticism about his suitability for politics. He preferred to see innovation thrive organically rather than letting bureaucrats control digital currency, even if those bureaucrats happened to like his blockchain.
His ultimate vision is to transform Solana into the backbone of global finance, allowing information to spread as quickly as news.
Although Solana is in direct competition with Ethereum in the so-called 'blockchain wars', Yakovenko rejects tribal thinking. He insists that different blockchains can coexist and complement each other rather than being a zero-sum game. This mature perspective is refreshing in the crypto industry, where people often predict competing protocols will 'go to zero' over minor technical differences.
Yakovenko used an insight that seems obvious in retrospect but had never been cracked before to build one of the world's most powerful distributed computers—turning time itself into a blockchain data structure.
His personal net worth is estimated to be between $500 million and $800 million, and his financial success allows him to focus on building rather than wealth accumulation.
But this recognition is just beginning to manifest in the most significant form in finance: other people's money. Currently, four publicly traded companies hold over $591 million worth of Solana tokens in their corporate treasuries, led by Upexi, which accumulated 1.9 million SOL tokens in just four months. SOL Strategies has taken a more systematic dollar-cost averaging approach. Classover Holdings announced plans to invest $500 million in Solana, and Trump's proposed U.S. strategic cryptocurrency reserve listed Solana alongside Bitcoin and Ethereum as strategic assets. When publicly traded companies start treating your blockchain tokens like treasury bonds, you may have built something truly significant.
The adoption by institutions indicates that Yakovenko's vision of Solana as the global financial infrastructure may not be far off. Asset management firms like Franklin Templeton and Fidelity are applying for Solana spot ETFs, and the logic of companies choosing SOL as treasury reserves is similar to holding BTC or ETH: it is a store of value while potentially powering the future financial system.
If that frustrating night at Café Soleil indeed led to the breakthrough that allowed money to flow at the speed of light, corporate CFOs had already begun to take notice.