


Author: Stacy Muur
Translation: Tim, PANews
In the past 15 months, the liquidity landscape of DeFi has been reshaped across chains, with projects driven by hype gradually exiting the stage, and liquidity quietly concentrating in places with strong fundamentals rather than market speculation.
Core Insights
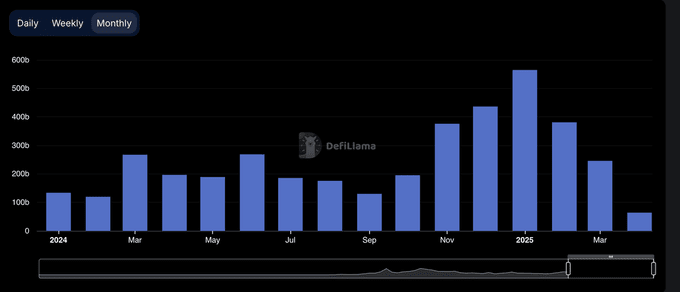
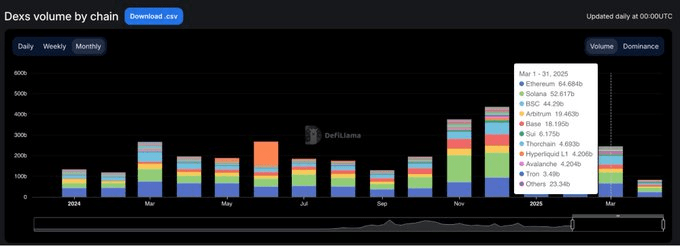
After DEX trading volume hit a historic high of $380 billion in January 2025, it fell 35% in the following two months, suggesting that January may have formed a short-term peak.
Currently, the top ten DEXs account for nearly 80% of total trading volume; just Uniswap and PancakeSwap together account for about 40% of the share.
Solana-based DEXs have quietly taken the lead in the rankings, holding 5 out of the top 10 spots, with their market share growth primarily driven by trading volume from the meme coin craze.
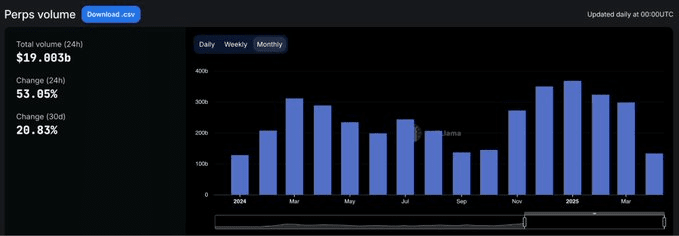
Hyperliquid has completely changed the landscape of perpetual contracts, rising from an industry newcomer to holding over 60% market share by March 2025.
All insights in this article are based on publicly available data. Special thanks to DefiLlama for continuously providing high-quality statistical data.
Cycles defined by surges and slowdowns
In early 2024, DEX trading volume performed strongly in March and May, then gradually slowed before mid-year.
The situation changed dramatically in the fourth quarter, with trading volume surging in November and December, a momentum that continued into January 2025, reaching an explosive peak of $380 billion.
However, this rebound was short-lived. By February, market trading volume plummeted to $245 billion, a 35% cliff drop that marked the end of three months of vertical surges. This decline set the tone for a more cautious second quarter.
DEX dominance: Leading protocols hold the power.
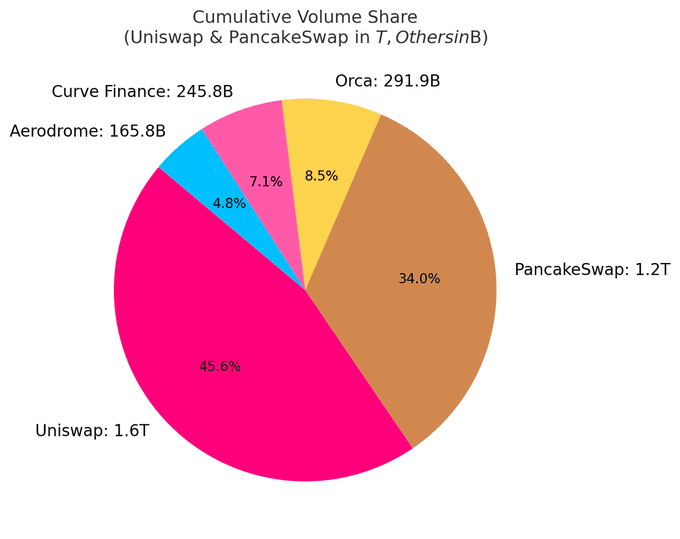
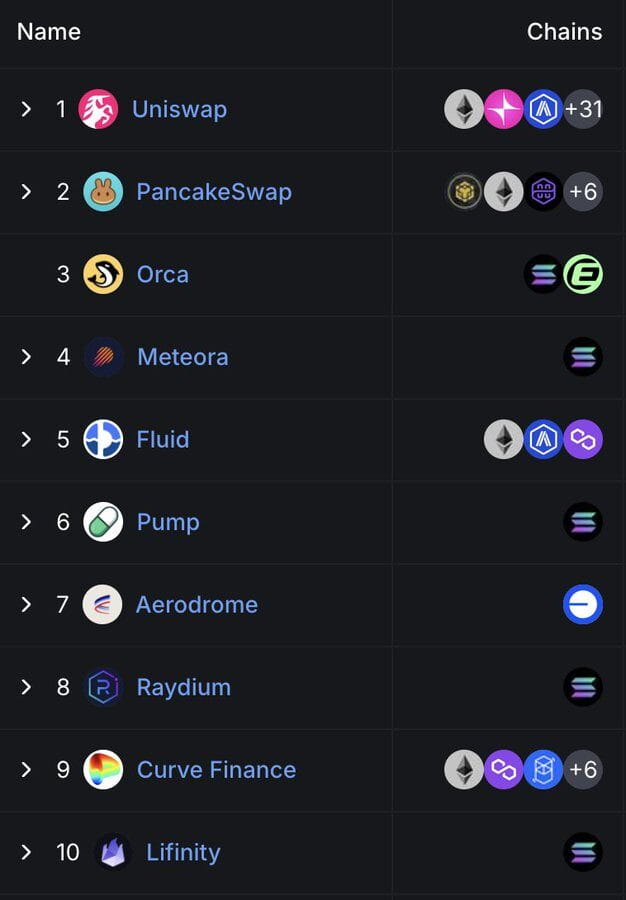
The market landscape for DEX remains highly concentrated. Currently, the top ten protocols account for 79.5% of daily trading volume, with the top five alone accounting for 59.1%.
Uniswap and PancakeSwap account for about 40% of DEX trading volume, being the only two platforms to have surpassed a total trading volume of one trillion dollars. Their leading position stems from first-mover advantage, extensive support for multi-chain ecosystems, and deep liquidity.
Uniswap Labs has also launched Unichain, an Ethereum Layer 2 network built on the Optimism Superchain. This chain aims to achieve fast, low-cost transactions through native multi-chain interoperability.
The quiet rise of Solana
Notably, Solana's position in the DEX space is becoming increasingly prominent. Among the currently top ten DEXs, five are natively developed based on Solana: Orca, Meteora, Raydium, Lifinity, and Pump.fun.
Orca (8.02%) and Meteora (6.70%) together account for about 15% of global decentralized exchange activity.
This growth stems from low GAS fees, fast block times, and the Solana meme coin craze. The rise of Pump.fun into the top ten is a vivid proof of this.
Emerging protocols: Fluid and Aerodrome
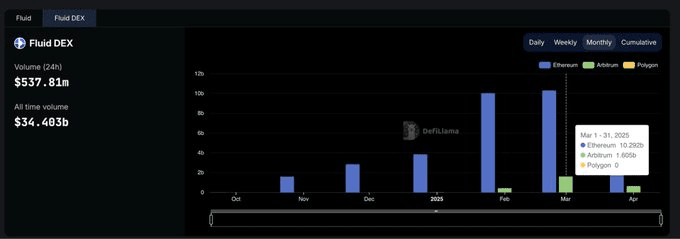
Fluid (7.09%) is the most capital-efficient platform among the top five DEXs. The protocol is active on Ethereum, with monthly liquidation amounts exceeding $10 billion. Its performance has been particularly impressive since the launch in the Arbitrum ecosystem: trading volume surged from $426 million in February to $1.6 billion in March, demonstrating its adoption speed far exceeding the industry average.
Aerodrome, as the native project of Base, showcases the continued growth of liquidity on Base L2.
Although Hyperliquid does not rank high in the spot market, it holds a dominant position in the perpetual contract market, with a market share exceeding 60%.
Market share of DEX across chains: Growth is easy, retention is hard.
The last 15 months have clearly indicated a phenomenon: most blockchain projects can attract attention, but only a few can maintain their appeal. From January 2024 to March 2025, the market share of chain-level decentralized exchanges changed rapidly, with very few projects truly possessing user stickiness.
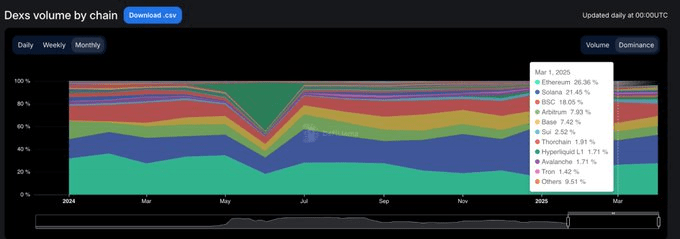
Solana achieved the biggest breakthrough. It steadily climbed in 2024, driven by the TRUMP and MELANIA meme coin craze, reaching a peak market share of 45.8% in January 2025. However, by March, its market share was halved to 21.5%, yet it still maintained a solid average share of 25.1% across public chains.
Ethereum is the complete opposite. It started early 2024 with about 32% market share, fell to 15.3% in January 2025, and then rebounded to 26.4% in March. Of course, even if Ethereum loses growth momentum, its ecological resilience remains.
Base can be considered the most robust contender. It grew steadily from 3% in March 2024 to 12.4% in December, then fell back to 7.4% in March 2025, maintaining an average share of 6.6% during this period. Without hype support, it only has slow yet sticky growth.
BNB Chain maintains stability with an average share of 14.7%. It has neither surged nor plummeted, consistently maintaining a steady flow of retail funds.
Arbitrum started strong (16% share) but weakened afterward, falling to 4.8% by January 2025, surpassed by both Base and Solana.
Blast peaked at a market share of 42.3% in June 2024 but vanished the following month. This is a clear case of incentive-driven trading volume with a zero user retention rate.
Summary: The dominance of DEX across public chains is highly volatile. Solana once rose sharply, Ethereum achieved value restoration, and Base gradually expanded its ecosystem, with the market speculation cycle showing significant ups and downs. Ultimately, the public chain that occupies dominance is not the loudest but the one with the highest actual usage.
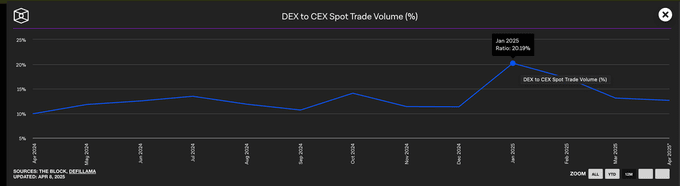
Centralized exchanges still dominate spot trading volume.
Although DEX saw explosive growth in early 2025, centralized exchanges still dominated the spot market. Even in January when DEX trading volume peaked, CEXs accounted for nearly 80% of total trading volume.
Although the dominance of centralized exchanges dropped from 90% in early 2024 to a low of 79%, the broader trend is clear: DEXs continue to grow, but CEXs remain the default choice for most traders.
Market share of perpetual protocols
The landscape of on-chain perpetual contracts underwent a fundamental change in 2024.
After dYdX firmly held the top position in perpetual contract trading for over two years, Hyperliquid emerged, redefining what dominance means. The platform first reached the top in February but was briefly surpassed by SynFutures mid-year. After reclaiming the top spot in August, it surged ahead. As of March 2025, Hyperliquid accounted for nearly 59% of the total trading volume in perpetual contracts, solidifying its position as the preferred platform for professional traders.
This rise has attracted significant market attention, with its product experience closer to centralized exchanges than ever before. In contrast, dYdX's market share has rapidly declined, dropping from 13.2% in early 2024 to just 2.7% by March 2025, as users flocked to faster, more streamlined, and modern alternative platforms.
Jupiter's perpetual contracts have forged a new path, leveraging Solana’s native liquidity and its spot DEX’s flow, rising to second place with an 8.8% market share. Although it rose quickly, it lacked sustaining power and ultimately fell behind Hyperliquid. Other projects like SynFutures, Vertex Protocol, and Paradex have also briefly emerged.
Perpetual contract chain: Execution layer completes reconstruction within a cycle.
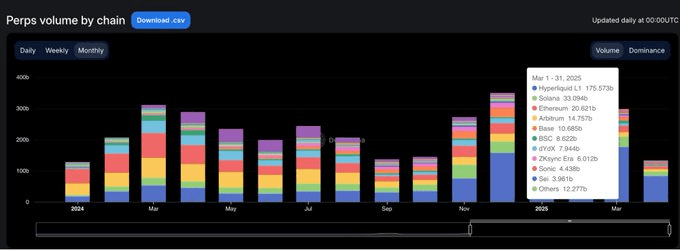
The biggest change in the perpetual contract infrastructure sector over the past year is not which protocols users prefer, but rather which chains they trust to execute trades.
By March 2025, the trading volume share of perpetual contracts for Ethereum and Arbitrum had plummeted to 11.8%, a stark contrast to their combined market dominance of over 65% in January 2024, as newer and faster execution layers had fully taken over.
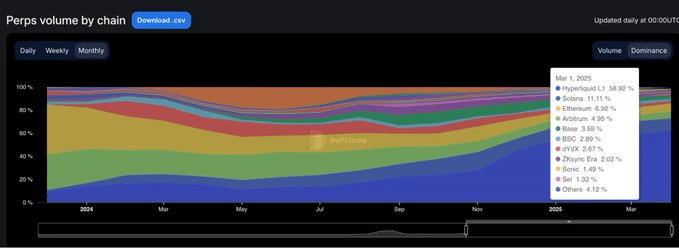
The driving force behind this transformation is Hyperliquid's independently developed blockchain. Within the same period, it significantly increased its market share from 13.6% to 58.9%, replacing various Layer 1 and Layer 2 solutions that once defined industry standards, becoming the default execution environment for perpetual contract trading. Its advantages not only lie in faster transaction speeds but, more importantly, in providing the reliability and low latency guarantees demanded by professional traders.
Solana also experienced a strong rise driven by Jupiter and Phoenix projects at the end of 2024, with its market share peaking at nearly 16%. However, it ultimately stabilized in the 10-11% range, failing to maintain its breakthrough growth momentum. Meanwhile, the Base and ZKsync ecosystems showed vitality (with peak market shares reaching 6-7%) but never managed to break into the top public chain ranks.
At the same time, Blast became a cautionary case: this ephemeral project reached a market share of 18.8% in June 2024 but disappeared at the same astonishing speed. In a field driven by product quality and user retention, mere speculation is hard to sustain. New industry execution standards are now clear: performance-driven public chains have redefined the competition benchmark, and traditional infrastructure no longer holds a default advantage.
The future of DeFi does not lie in multi-chain expansion but belongs to those protocols that can transform industry narratives into user habits.
(The above content is excerpted and reprinted with permission from partner PANews, original link)
Statement: The views in this article only represent the personal opinions of the author and do not reflect the views and positions of Block客. All content and opinions are for reference only and do not constitute investment advice. Investors should make their own decisions and trades, and the author and Block客 will not bear any responsibility for direct or indirect losses formed from investors' trades.
"The migration of on-chain liquidity: After 15 months of fluctuations, who stands firm as speculation wanes?" This article was first published on (Block客).