


Author: Thinking Weird
First, although Bittensor officially touts itself as a 'fair mining' project, the underlying Subtensor is neither a PoW public chain nor a PoS public chain; it is a single-chain managed by the Opentensor Foundation (the foundation of Bittensor), with a very opaque mechanism.
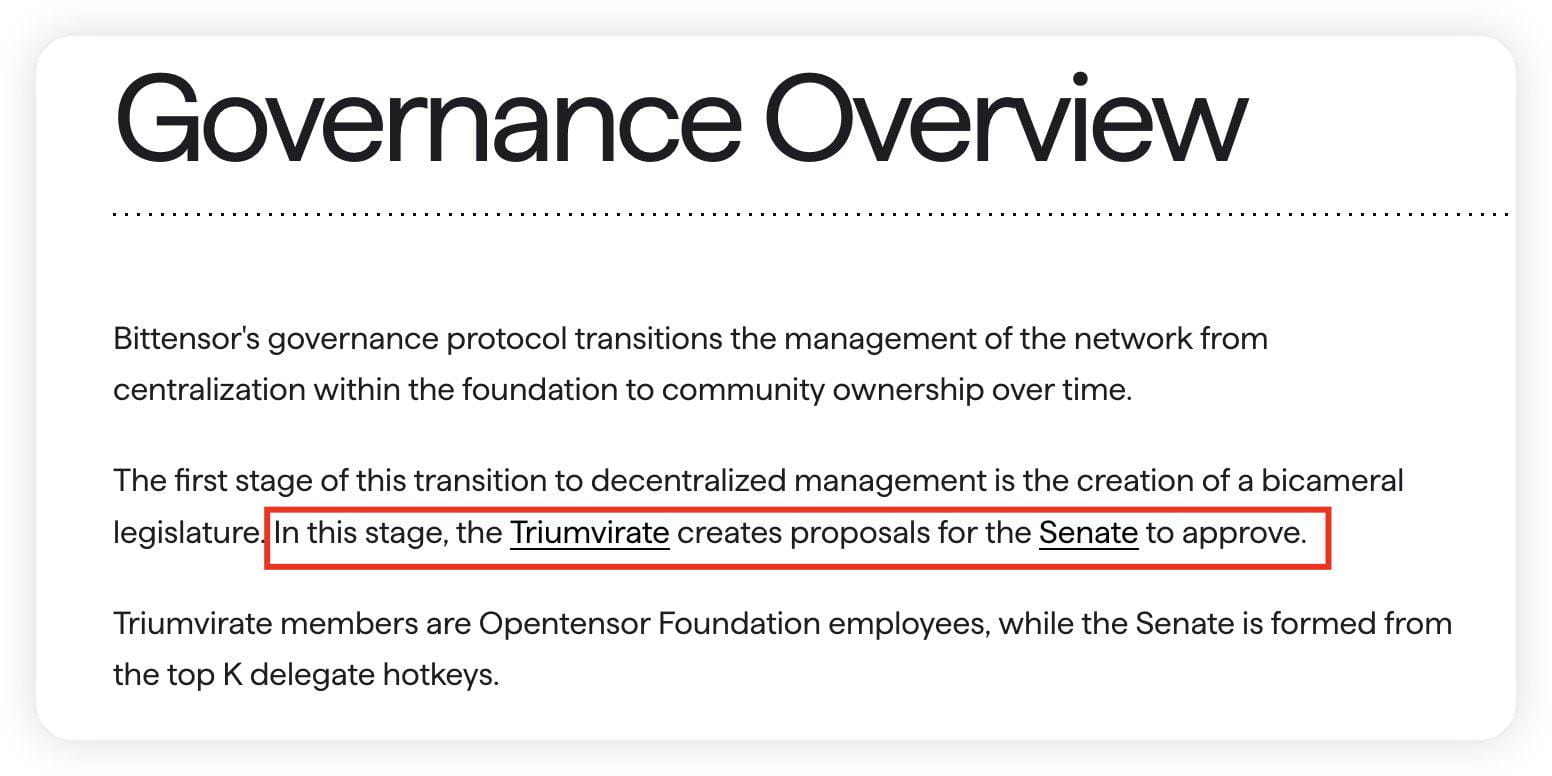
As for the so-called 'three giants + senate' dual governance structure, the three giants are three employees of the Opentensor Foundation, and the senate consists of the top 12 verification nodes, all of whom are either insiders or stakeholders.

Secondly, on January 3, 2021, 'Kusanagi' was released, marking the activation of the Bittensor network and allowing miners and verifiers to begin receiving the first batch of TAO rewards. From network activation to the launch of subnets on October 2, 2023, Bittensor has mined a total of 5.38 million TAO. However, there are no documents or materials explaining the rules for distributing the tokens generated during the period from January 3, 2021, to October 2, 2023, when subnets were launched, nor where they ultimately went.
It can be reasonably speculated that this portion of tokens is divided among internal members and interest groups since Bittensor is not like Bitcoin; it is incubated and invested by VCs.
If this part of the tokens is divided by the current issuance of 8.61 million, at least 62.5% of TAO is in the hands of internal members and interest groups. Moreover, the Opentensor Foundation and some investing VCs also operate verification node businesses on Bittensor, so the proportion of chips in their hands will only be more than this 62.5%.
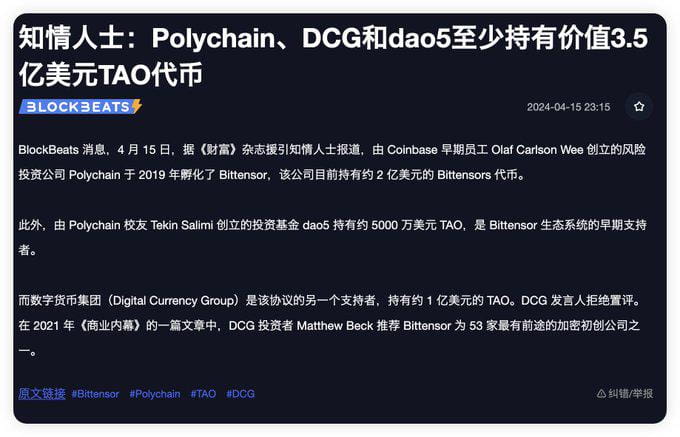
Similar to the OM that collapsed a few days ago, all projects you don't know why their market cap is so high often have their distorted market caps created by poor circulation.
Billions market cap backed by poor liquidity.
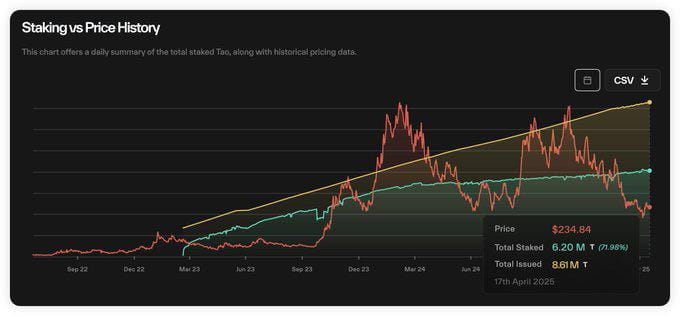
The chart below shows the historical staking situation of TAO; do not be fooled into thinking that the staking rate of TAO has gradually increased from low to high. It is depicted this way because TAO is experiencing severe inflation.
In fact, the staking rate of TAO has never been lower than 70%, peaking close to 90%. Based on TAO's current market cap of 2 billion USD, this means that at least 1.4 billion USD of TAO has never participated in circulation. The actual market cap of TAO is only 600 million USD, while the corresponding FDV is as high as 5 billion USD, which is a typical case of low circulation and high market cap.
The so-called number one AI project by market cap, how the bubble was inflated by the major players, please savor.
Ultimately, the so-called dTAO upgrade is more like providing OGs with an opportunity to exit liquidity. It allows you to buy the highly inflated subnet tokens while taking over the TAO held by interest groups.
According to the three plate theory, the dTAO upgrade of Bittensor in February this year had to introduce a new Ponzi scheme model of 'splitting plate' and 'mutual assistance plate' to deleverage due to the unsustainability of the 'dividend plate'. The core purpose is to fabricate a new narrative to attract new external liquidity to continue extraction as the old narrative weakens and external liquidity is quickly drained.
First is the 'splitting plate': by allowing all subnets to issue tokens, TAO successfully positions itself as the base currency for all Bittensor subnet tokens, its value supported by dozens of (and increasing) subnet tokens.
Due to the deep transaction pool, subnet tokens often have astonishing increases. This allows Bittensor to present a facade of an ecosystem that can provide high ROI opportunities to the outside world. Meanwhile, the exaggerated nominal ROI offered by subnet Alpha tokens artificially creates massive buying pressure for TAO, and provides cover for root network verification nodes to sell off TAO.
Unfortunately, Bittensor's closed ecosystem, combined with the market environment turning from bull to bear, has resulted in the dTAO upgrade failing to attract enough external liquidity, and even internal liquidity (those TAO staked in the root network) has not been sufficiently activated.
At the same time, the lowering of entry thresholds and the unlimited number of subnets has led to excessive and rapid issuance diluting the overall liquidity of the Bittensor ecosystem, which was already limited.
Secondly, there is the 'mutual assistance plate'. Unfortunately, the issuance of tokens by Bittensor's subnets cannot establish a mutual assistance model like Pump.fun on Solana, where funds can circulate highly, because Bittensor's network infrastructure is very poor, and even different subnet tokens cannot be exchanged, making it difficult for participants of subnet tokens to migrate liquidity between different subnets. This further exacerbates the liquidity dilution issue caused by high splitting rates, making it impossible to keep funds continuously participating in speculation.
Once the large stakers of the root network begin to collectively flee, liquidity both on and off the market will quickly dry up.
The moment you sell, game over.
So are the large holders fleeing? The answer is 'they are fleeing'!
Since the launch of dTAO:
➤ The Bittensor protocol injects 450,000 TAO into the subnet pool.
➤ 150,000 TAO (33%) flowed to root network verification nodes through an 'automatic sell' mechanism.
➤ The staking volume of the root network (τ₀) has decreased by 150,000 (5.86 million → 5.71 million).
This means:
300,000 TAO (≈70 million USD) successfully fled from the root network and may be liquidated in CEX.
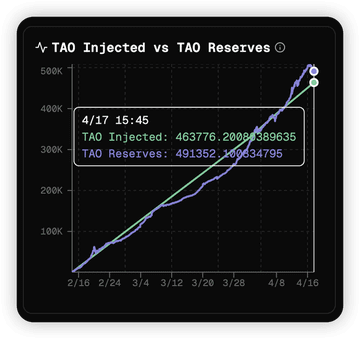
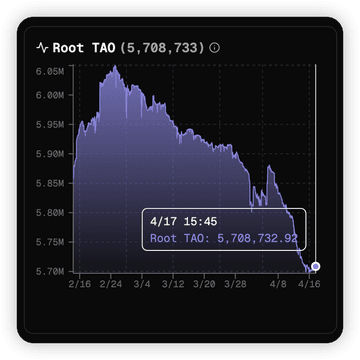
Moreover, previously Bittensor's foundational support was from subnets and miners. Bittensor's earlier model was like a VC, providing funds to projects so they could focus on building valuable business models without immediately worrying about how to ensure a balanced income. This was the core reason for attracting projects to create subnets on Bittensor.
And the project has attracted miners to provide computing power (what Bittensor refers to as 'intelligence'), this 'good for you, good for me, good for everyone' situation is the core reason why Bittensor can become the largest market-cap crypto AI project.
However, after the dTAO upgrade, the interests of subnet project parties, miners, and verification nodes are no longer aligned, and the previous 'good for you, good for me, good for everyone' situation no longer exists. The dTAO model offers no benefits to subnet project parties; the collapse of the economic model is currently the biggest and most fundamental issue facing Bittensor.
In Bittensor's dTAO model, subnet Alpha tokens are a kind of 'warrant' obtained from staking TAO in the subnet, and are not generally tradable tokens.
This makes it difficult for subnet project parties to invent any effective tokenomics for these tokens. These Alpha tokens have no utility for retail investors other than being able to generate more Alpha tokens.
Based on my observations, subnet project parties now most commonly declare to use project revenue to buy back Alpha tokens to boost the token price, such as Chutes (SN64).
But if Subnet Owners can only empower Alpha tokens in this way, then the funny thing will happen. The 18% Alpha tokens allocated to subnet project parties from dTAO will forever be stuck in the hands of the project parties themselves. After all, you have already announced that you will use project revenue for buybacks, so why sell your own tokens?
Selling and buybacks are contradictory.
Therefore, subnet owners cannot earn any income from the dTAO model and even have to subsidize it: creating external income and injecting it into their subnet Alpha tokens.
This means that subnet project parties and miners are essentially working for verification nodes.
As the privileged class of the Bittensor network, verification nodes can do nothing of value, and since the dTAO upgrade began, they can continuously sell subnet Alpha tokens, with TAO flowing to the root network accounting for up to 1/3 of daily emissions.
The reason Bittensor can attract other projects to establish subnets on it is fundamentally due to the prior TAO emissions, which served as a good subsidy mechanism for emerging projects without revenue, allowing them to focus solely on their business models.
If this subsidy mechanism not only disappears but is even reversed, why would subnet project parties still want to establish subnets on Bittensor?
Going solo, keeping all the income to oneself, doesn't that sound good?
Thus, the dTAO model, as a means for interest groups to offload their tokens, is damaging the foundational support that Bittensor has developed up to now.
Although the business models of most subnets in the Bittensor ecosystem are terrible, without them, Bittensor would lose its last shred of decency.
References for this article:
1. Bittensor Official Documentation: docs.bittensor.com
2. @harry_xymeng Teacher's research report (Bittensor: When Does the Music Stop): prism-pancake-61a.notion.site/Bittensor-432c
3. @thecryptoskanda Teacher's (Three Plate Theory - The Ultimate Guide to Ponzi Construction): https://x.com/thecryptoskanda/status/1872193691479351519