Author: Jacob Zhao
The recent crypto market has been lackluster, and conservative and stable returns have become a demand in the market. Therefore, combining my investment insights from recent years and concentrated research results in the stablecoin field at the end of last year, I would like to discuss the ancient but evergreen topic of stablecoin yields.
The current categories of stablecoins in the crypto market mainly include the following types:
· USDT, which is conditionally compliant but has the highest market share: It has a sufficiently broad application scenario (trading pairs on exchanges, crypto industry company payrolls, real international trade, and offline payment scenarios). Users hope for a large entity that cannot fail, and Tether has the backing capability.
· Compliant stablecoins pegged 1:1 to fiat currency: USDC has the most chains and application scenarios, making it a true on-chain dollar, while other compliant stablecoins like PayPal USD and BlackRock USD have certain limitations in their application scenarios.
· Over-collateralized stablecoins: Primarily represented by MakerDAO's DAI and its upgraded version Sky Protocol's USDS; Liquity's LUSD has become one of the competitors with its zero collateral loan rate and 110% low collateral ratio micro-innovation.
· Synthetic asset stablecoins: The most representative of this cycle is Ethena's USDe, which has a revenue model based on capital fee rate arbitrage, one of the stablecoin yield models that will be analyzed in detail later in this article.
· RWA project stablecoins backed by U.S. Treasuries: The most representative of this cycle are Usual's USD0 and Ondo's USDY. Usual's USD0++ provides liquidity for U.S. Treasuries, similar to Lido's role in ETH staking, demonstrating innovation.
· Algorithmic stablecoins: After the collapse of Terra's UST, the track was essentially discredited. Luna lacked real value to support token prices, leading to extreme volatility, a death spiral of crashing, selling, and further crashing, before finally decoupling and collapsing. FRAX, which combines algorithmic stablecoins and over-collateralization models, still has some application scenarios, while other algorithmic stablecoins have lost market influence.
· Non-U.S. dollar stablecoins: Euro stablecoins (such as Circle's EURC and Tether's EURT) and other fiat stablecoins (BRZ, ZCHF, HKDR, etc.) currently have minimal influence on the U.S. dollar-dominated stablecoin market. A non-U.S. dollar over-collateralized stablecoin project I once invested in has essentially gone to zero. The only way out for non-U.S. dollar stablecoins lies in payment services under a compliant regulatory framework rather than being applied to the native crypto community.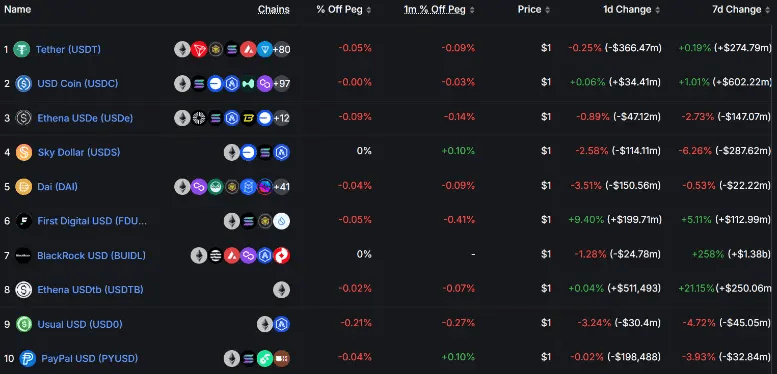 Stablecoin market capitalization rankings
Data source: https://defillama.com/stablecoins
Currently, the main categories of revenue-generating models through stablecoins are as follows, and this article will further analyze each type of revenue: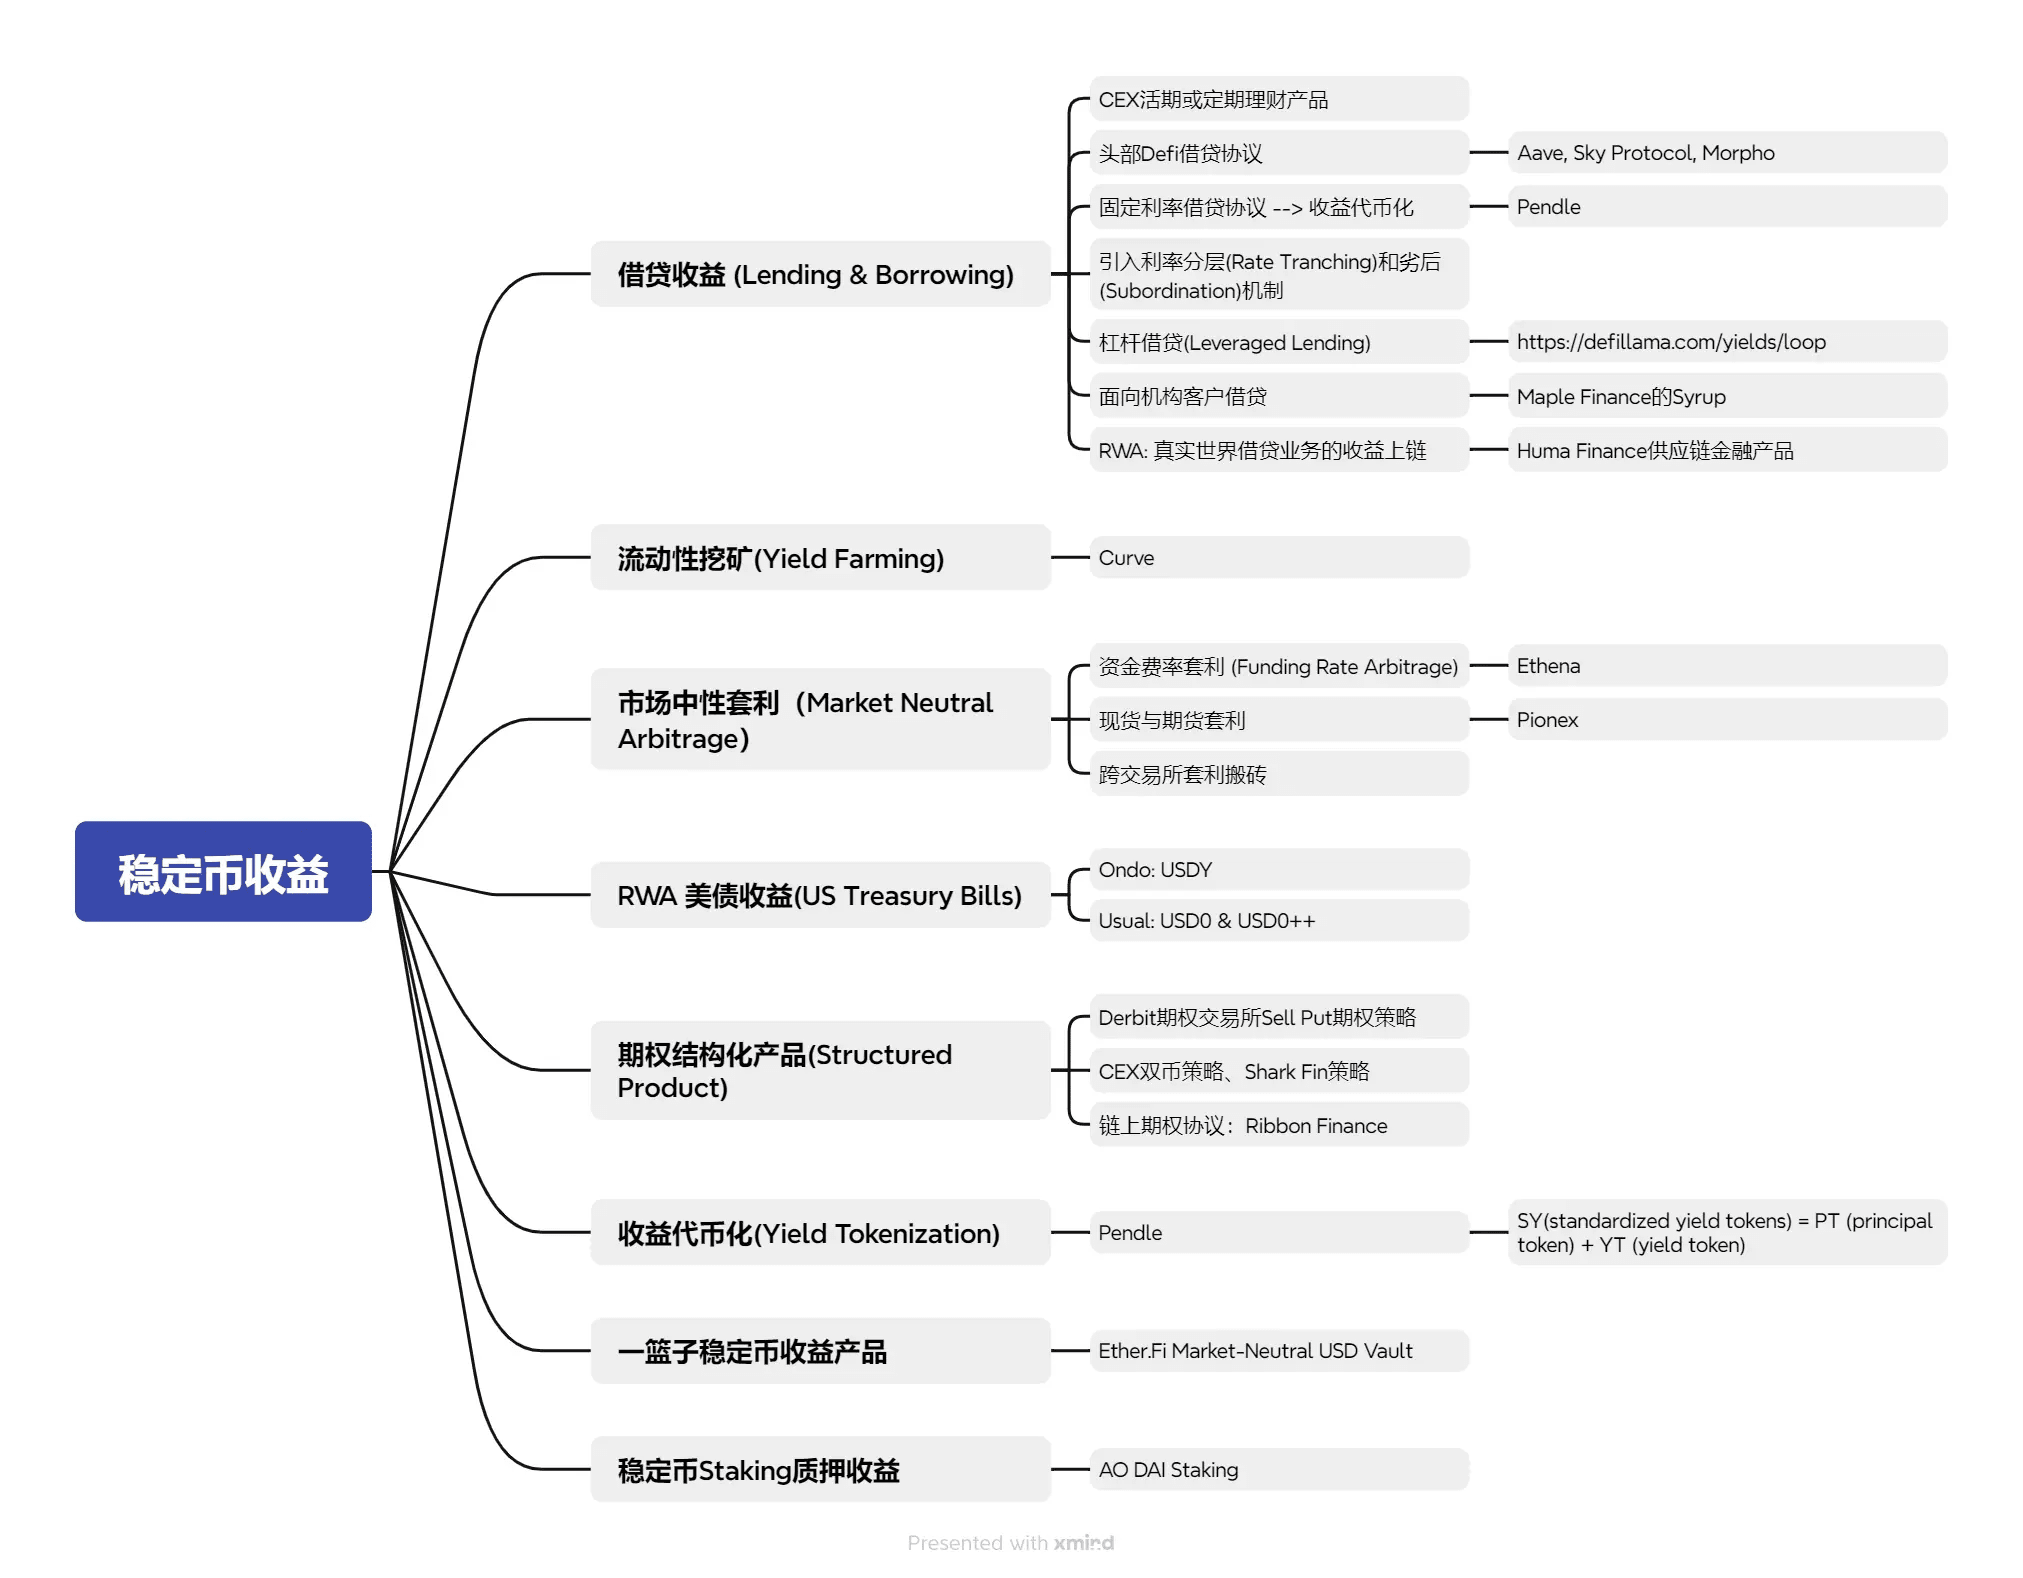
1. Stablecoin Lending & Borrowing:
Lending, as the most traditional financial revenue model, derives its essence from the interest paid by borrowers. It is necessary to consider the platform or protocol's security, the borrower's default probability, and the stability of returns. The current stablecoin lending products in the market include:
· CeFi platforms mainly feature liquid financial products from leading exchanges (Binance, Coinbase, OKX, Bybit).
· Leading DeFi protocols primarily include Aave, Sky Protocol (the brand after MakerDAO's upgrade), Morpho Blue, etc.
Leading exchanges that have weathered market cycles offer high platform security, and leading DeFi protocols also have high security. During market uptrends, the demand for lending leads to U's liquid yield easily soaring above 20%. However, during quiet market periods, general returns are lower, maintaining around 2%-4%. Therefore, flexible interest rates are also a very intuitive market activity indicator. Fixed-rate lending sacrifices liquidity, so most of the time, yields are higher than flexible rates, but during active market periods, it cannot capture the soaring returns of flexible rates.
In addition, there are some minor innovations in the overall stablecoin lending market, including:
· Fixed-rate lending DeFi protocols: The highly representative Pendle protocol, which started with fixed-rate lending and evolved into yield tokenization, will be detailed later in this article. Early fixed-rate DeFi projects like Notional Finance and Element Finance, though not successful, have design concepts worth referencing.
· Introduction of interest rate tranching and subordination mechanisms in lending;
· DeFi protocols offering leveraged lending;
· DeFi lending protocols aimed at institutional clients, such as Maple Finance's Syrup, which derives revenue from institutional lending.
· RWA projects bringing real-world lending business revenues on-chain, such as Huma Finance's on-chain supply chain financial products.
In summary, lending as the most traditional financial revenue model is easy to understand and will continue to be the main stablecoin revenue model due to its capacity to handle significant funds.
2. Yield Farming Income:
With Curve as a representative, its income comes from AMM trading fees shared with LPs and token rewards. Curve, as the holy grail of stablecoin DEX platforms, has become a significant indicator of new stablecoins' industry adoption when supported in Curve Pools. The advantage of Curve mining lies in its high security, while the downside is the low yield (0-2%), which may not even cover transaction gas fees if non-large and long-term funds participate in Curve's liquidity mining.
Meanwhile, Uniswap's stablecoin pool trading pairs face similar issues; non-stablecoin trading pairs on Uniswap may incur losses due to liquidity mining, while other smaller DEXs' stablecoin pool trading pairs, even with higher yields, still have rug pull concerns. All of these do not conform to the cautious and steady principles of stablecoin wealth management. We can see that the current DeFi stablecoin pools still predominantly follow the lending model, with Curve's classic 3Pool (DAI USDT USDC) only ranking in the top twenty for TVL.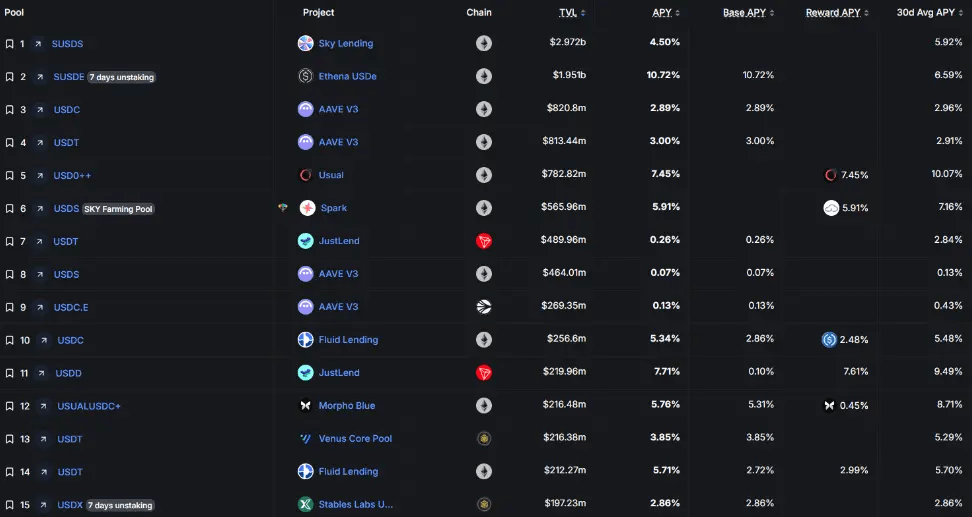
Stablecoin pool TVL rankings
Source: https://defillama.com/yields?token=ALL_USD_STABLES
3. Market Neutral Arbitrage Income:
Market-neutral arbitrage strategies have been widely applied in professional trading institutions for a long time. By simultaneously holding long and short positions, the net market exposure of the investment portfolio approaches zero. Specifically for crypto, it mainly includes:
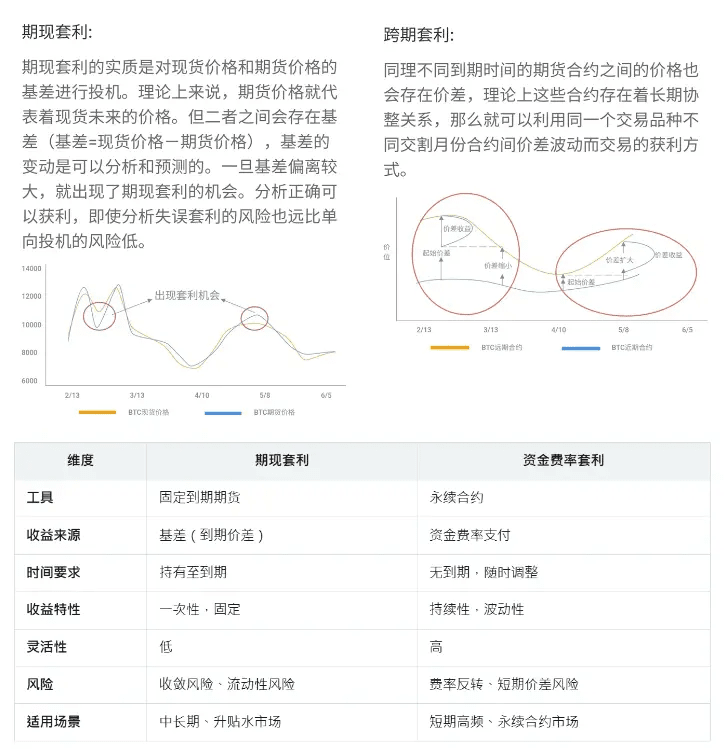
· Funding Rate Arbitrage: Perpetual futures have no expiration date, and their prices align with spot prices through a funding rate mechanism. The funding rate needs to be paid periodically, shortening the short-term price difference between spot and perpetual contracts.
· When the perpetual futures price is higher than the spot price (contango), longs pay shorts, and the funding rate is positive.
· When the perpetual futures price is lower than the spot price (backwardation), shorts pay longs, and the funding rate is negative.
· Historical drawdown data shows that the probability of a positive funding rate is long-term greater than that of a negative funding rate. Therefore, returns mainly come from buying spot assets in positive funding rate scenarios and shorting perpetual contracts to collect fees paid by longs.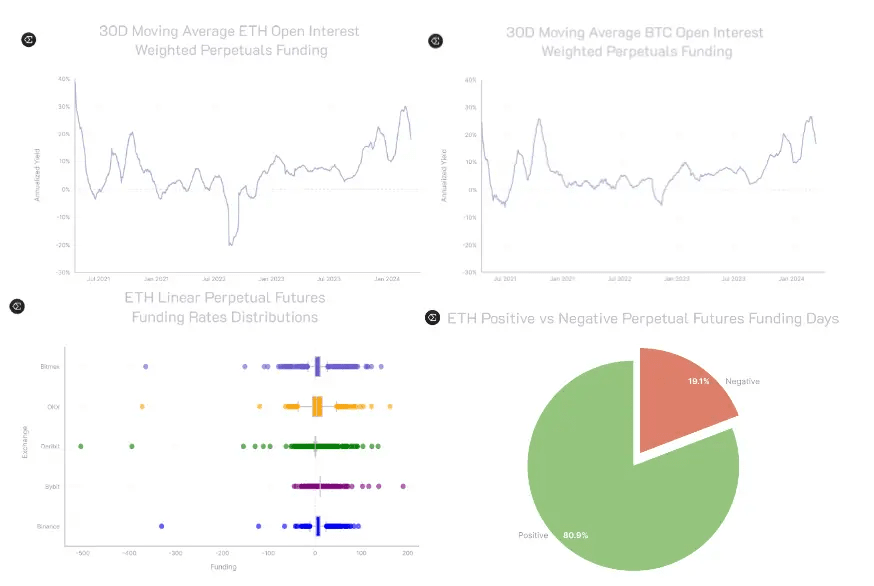 · Cash-and-Carry Arbitrage: This arbitrage takes advantage of price differences between the spot market and futures market at expiration by hedging positions to lock in profits. The core concept is the basis, which is the difference between the futures price at expiration and the spot price. It is typically operated in contango (futures price higher than spot) or backwardation (futures price lower than spot) markets. Cash-and-carry arbitrage is suitable for investors with substantial funds and those who can accept a lock-in period while being optimistic about basis convergence, commonly seen among traders with traditional financial thinking.
· Cross-exchange arbitrage: Utilizing price differences between different exchanges to build neutral positions has been a mainstream arbitrage method in the early days of the crypto industry. However, currently, the price differences among mainstream trading pairs across exchanges are already very low, requiring reliance on automated arbitrage scripts and being more suitable for high-volatility markets and low-market-cap coins. The participation threshold for retail users is high; they may refer to the Hummingbot platform.
Furthermore, there are triangular arbitrage, cross-chain arbitrage, and cross-pool arbitrage models in the market, which will not be elaborated on in this article.
Market-neutral arbitrage strategies, due to their high professionalism, are mostly limited to professional investors. The emergence of Ethena in this cycle brings the mature model of "Funding Rate Arbitrage" on-chain, allowing ordinary retail users to participate.
Users depositing stETH in the Ethena protocol will mint an equivalent amount of USDe tokens. At the same time, they can open an equivalent short position on a centralized exchange to hedge and earn positive funding rates. According to historical statistics, over 80% of the time, funding rates are positive, and in scenarios with negative funding rates, Ethena will compensate for losses through reserves; over 65% of Ethena's revenue hedges funding rates, and there are also some Ethereum staking, on-chain, or exchange lending revenues (35%) as supplementary income. Additionally, user assets are custodied at third-party custodians (Off Exchange Settlement) and regularly audited, effectively isolating exchange platform risks.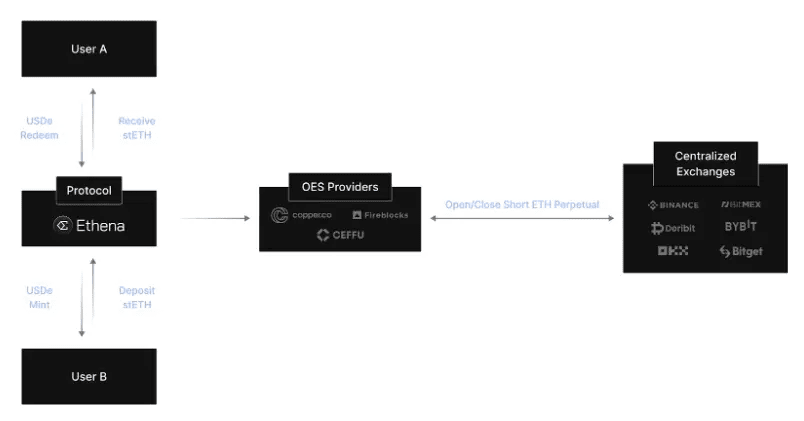 Regarding the risks of Ethena, aside from incidents involving exchanges and custodians, smart contract security issues, or the decoupling of pegged assets—factors beyond the project's control—the more critical core point is the long-term losses in negative funding rate scenarios where the protocol's reserved funds cannot cover them. Based on historical drawdowns, we can understand that this probability is low. Even if it occurs, it implies a failure of the generally applicable "Funding Rate Arbitrage" trading strategy within the industry. Therefore, under the premise that the team does not engage in malfeasance, the Ethena protocol is unlikely to experience the death spiral model of Terra's algorithmic stablecoin. What may happen is a gradual return of high yields subsidized by tokens back to a normal arbitrage yield range.
At the same time, we must acknowledge that Ethena has maximized data transparency, allowing users to clearly query historical yields, funding rates, positions across different exchanges, and monthly custody audit reports on its official website, surpassing other funding rate arbitrage products in the market.
Aside from Ethena's "Funding Rate Arbitrage" model, the Pionex exchange also offers a "Term Arbitrage" model for stablecoin wealth management products. Unfortunately, aside from Ethena, there are currently not many market-neutral arbitrage products available for retail customers to participate in with low thresholds.
4. U.S. Treasury Yield RWA Projects (US Treasury Bills)
The Federal Reserve's interest rate hike cycle from 2022 to 2023 pushed the U.S. dollar interest rate above 5%. Even though it has now shifted to gradual rate cuts, the interest rate above 4% remains a rare asset class in the traditional financial industry that balances high safety with relatively high returns. RWA businesses have high compliance requirements and operational models, and U.S. Treasuries, as a standardized asset with high transaction volume, are one of the few RWA products with a viable business logic.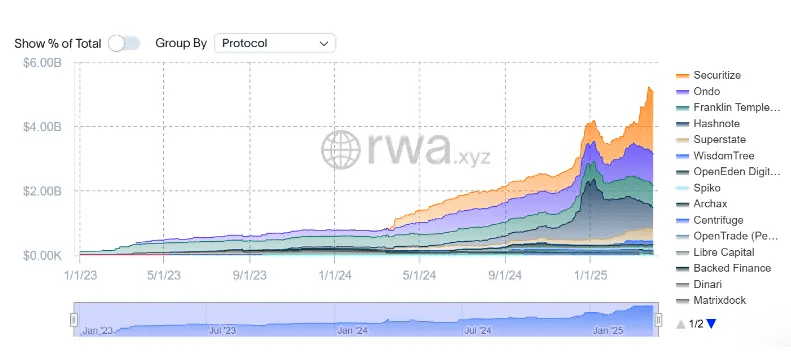 Ondo, with U.S. Treasuries as the underlying asset, offers USDY to non-U.S. general retail clients and OUSG to U.S. institutional qualified clients, both yielding 4.25%. In terms of multi-chain support and ecological applications, it is the leader in the RWA track. However, in terms of regulatory compliance, it is slightly inferior to Franklin Templeton's FOBXX and BlackRock's BUIDL. The Usual protocol, which has emerged strongly in this cycle, adds liquidity tokens USD0++ on top of the USD0 backed by a basket of U.S. Treasuries, similar to Lido's role in Ethereum staking, providing liquidity for locked U.S. Treasuries and allowing participation in stablecoin liquidity mining or lending pools to earn additional income.
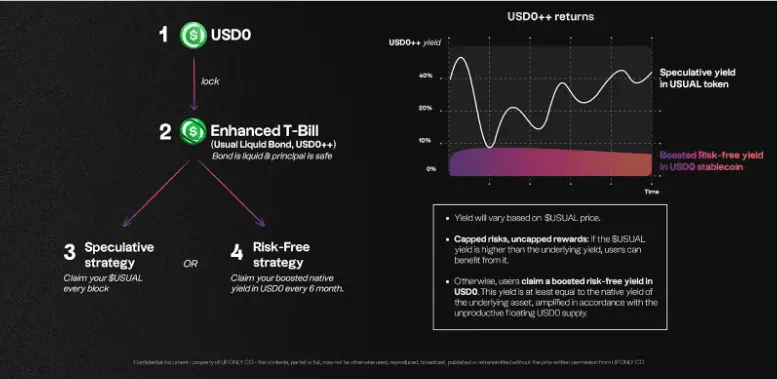 It is important to note that most U.S. Treasury RWA projects yield stable returns around 4%. Usual's stablecoin pool's higher yields primarily come from Usual token subsidies, Pills (Point) incentives, and liquidity mining, which are speculative additional revenues and lack sustainability. As the most complete U.S. Treasury RWA project within the DeFi ecosystem, it still faces the risk of slowly declining yields without catastrophic failures.
Although the redemption mechanism adjustment of USD0++ in early 2025 led to price decoupling and selling events, the root cause lies in the mismatch between its bond attributes and market expectations, compounded by governance failures. Nonetheless, its liquidity design mechanism remains an industry innovation worth emulating for other U.S. Treasury RWA projects.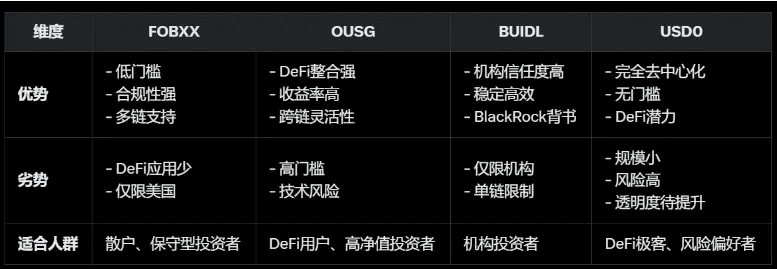 5. Structured Products (Options)
Currently, structured products and dual-currency strategies popular in most centralized exchanges originate from the 'selling options to earn premiums' strategies of options trading, specifically Sell Put or Sell Call strategies. U-based stablecoins primarily employ Sell Put strategies, with revenue stemming from the options premiums paid by option buyers, i.e., earning stable USDT options premiums or purchasing BTC or ETH at lower target prices.
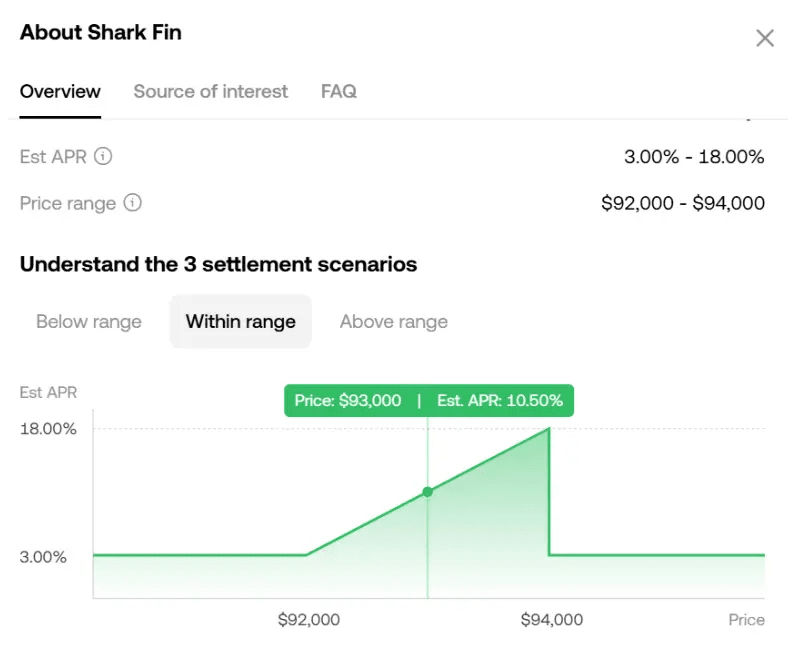
In practical applications, selling options strategies are more suitable for sideways market conditions, with Sell Put target prices set at the lower limit of the range and Sell Call target prices at the upper limit. For strongly bullish markets, the options premium income is limited, and it is more appropriate to choose Buy Call. In the case of a strongly bearish market, Sell Put can easily lead to a situation of buying at mid-levels and continuously incurring losses. Beginners in selling options trading may easily fall into the trap of pursuing short-term 'high options premium income' while ignoring the risk exposure brought by significant price declines, but setting the target price too low results in insufficient attractiveness of options premium yields. Based on my years of options trading experience, the Sell Put strategy is mainly employed during periods of market downturns and panic by setting lower buy target prices to earn high options premiums, while during market uptrends, choosing the yield from exchange liquid lending is more desirable.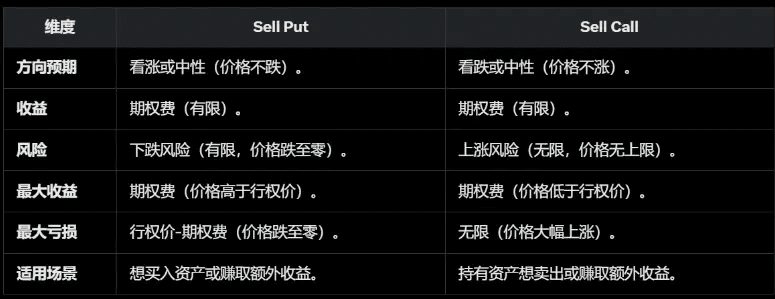 Regarding the Shark Fin principal protection strategy popular in exchanges like OKX recently, it adopts a Bear Call Spread strategy (Sell Call to collect premiums + Buy Call at a higher strike price to limit upside) + Bull Put Spread (Sell Put to collect premiums + Buy Put at a lower strike price to limit downside), allowing the entire options portfolio to earn options premium income within a range, while buying and selling options outside the range offsets with no extra income. This strategy is suitable for users who prioritize principal safety and do not seek to maximize options premiums or currency-based returns.
 The maturity of on-chain options is still under development. Ribbon Finance was once a leading options vault protocol in the previous cycle, and leading on-chain options trading platforms like Opyn and Lyra Finance can also manually trade options premium strategies; however, they are no longer as prominent as before.
6. Yield Tokenization
The highly representative Pendle protocol in this cycle originated from fixed-rate lending in 2020 and evolved into yield tokenization in 2024, allowing users to lock in fixed returns, speculate on future yields, or hedge yield risks by breaking down yield assets into different components.
· Standardized Yield Tokens (SY) can be split into Principal Tokens (PT) and Yield Tokens (YT).
· PT (Principal Token): Represents the principal portion of the underlying asset, redeemable at 1:1 for the base asset at maturity.
· YT (Yield Token): Represents the future yield portion, decreasing over time, with a value of zero at maturity.
Pendle's trading strategies mainly include:
· Fixed Income: Holding PT until maturity can yield fixed returns, suitable for risk-averse individuals.
· Yield Speculation: Purchasing YT to bet on future yield increases, suitable for risk-tolerant individuals.
· Risk Hedging: Selling YT to lock in current yields and avoid market decline risks.
· Liquidity Provision: Users can deposit PT and YT into liquidity pools to earn trading fees and PENDLE rewards.
Currently, their main stablecoin pool not only includes native yield from the underlying assets but also adds speculative YT income, LP income, Pendle token incentives, and Points, making its overall yield attractive. One downside is that Pendle's high-yield pools generally have shorter terms, requiring frequent on-chain operations to switch yield pools, unlike Staking or liquidity mining or lending pools, which can be set up once for lasting results.
7. A Basket of Stablecoin Yield Products:
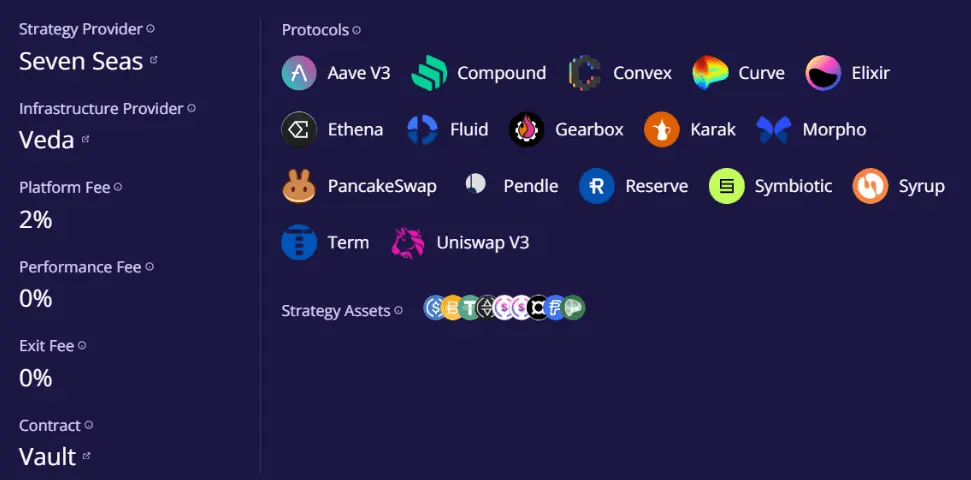
Ether.Fi, as the leading protocol for Liquid Restaking, actively embraces changes and has transformed its products to offer various yield products in BTC, ETH, and stablecoins after the saturation and downward trend in the Restaking track, maintaining its leading position in the entire DeFi industry.
In its stablecoin Market-Neutral USD pool, it offers a basket of stablecoin yield products for users, including lending income (Syrup, Morpho, Aave), liquidity mining (Curve), funding rate arbitrage (Ethena), yield tokenization (Pendle), etc. This approach is an effective method for users seeking stable on-chain yields, with insufficient funds and unwilling to operate frequently, balancing high returns and risk diversification.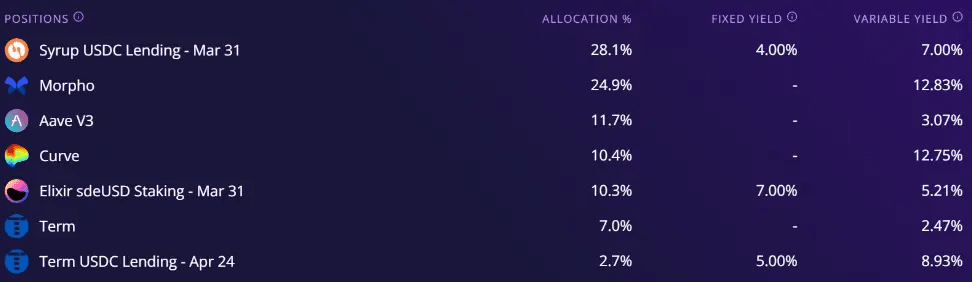
 8. Stablecoin Staking Yield:
Stablecoin assets do not possess staking properties like ETH in POS public chains. However, the AO network launched by the Arweave team accepts on-chain staking of stETH and DAI under the Fair Launch issuance model, and staking DAI offers the highest AO yield capital efficiency. We can classify this type of stablecoin staking model as an alternative stablecoin yield model, allowing users to earn additional AO token rewards while ensuring the safety of DAI assets, but the core risk lies in the development of the AO network and the uncertainty of token prices.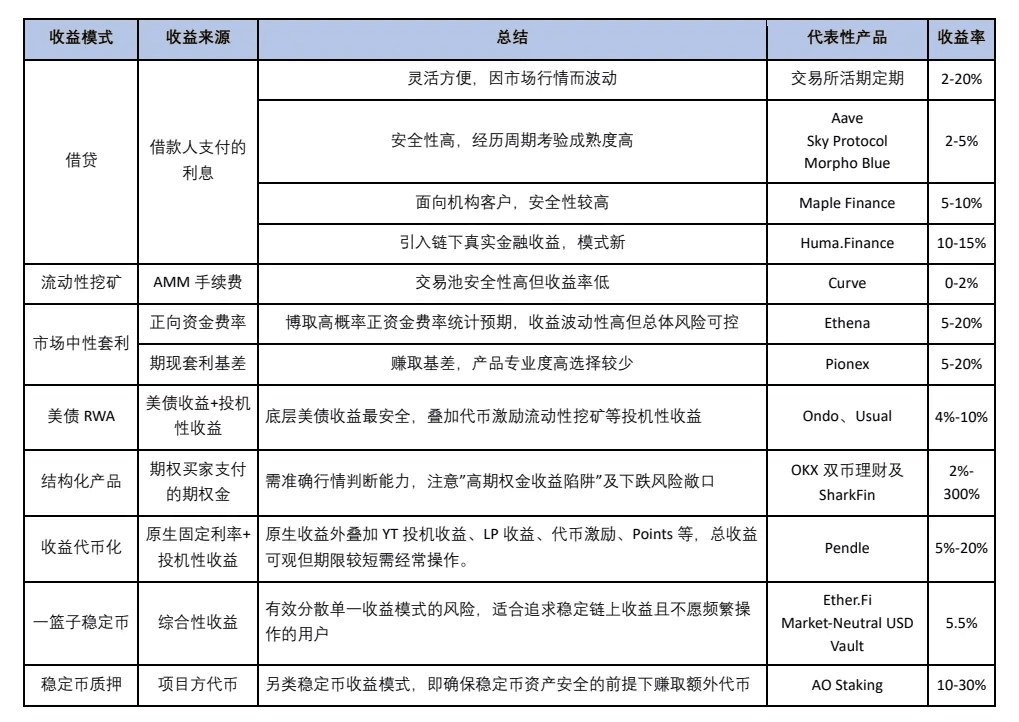 In summary, we have summarized the mainstream stablecoin yield models currently present in the crypto market in the table above. Stablecoin assets are the most familiar yet easily overlooked market for crypto market practitioners. Understanding stablecoin yield sources and rational allocation will enable a more confident response to the uncertainty risks in the crypto market based on a solid financial foundation.

Article
Research: Stablecoin Yield Guide - Which of the 8 Types is Best?


--