


Original author: vik0nchain, Cyber Capital researcher
Original translation: Luffy, Foresight News
From the fourth quarter of 2024 to early 2025, the competitive landscape of Solana's DeFi ecosystem is gradually becoming apparent, primarily reflected in the rise of aggregators, the abstraction of user experience (UX), significant integrations, and the evolving standards of token economics. Although these changes were not initially obvious, recent data has clearly shown their impact, particularly highlighted by the redistribution of liquidity, fee generation, and changes in market share.
This analysis delves deeply into the liquidity positioning of major decentralized exchanges (DEX) on Solana—Raydium, Jupiter, Orca, and Meteora—focusing on their advantages, disadvantages, and potential investment impacts relative to existing and emerging competitors.
Investment analysis framework
Raydium (RAY) outlook is optimistic: deep liquidity and buyback advantages
Dominance in liquidity and trading volume: Raydium remains the strongest and most frequently used decentralized exchange in the Solana ecosystem. Over 55% of trades routed through Jupiter are settled on Raydium. Additionally, Raydium holds a market-leading position among decentralized exchanges across all blockchains, alongside the long-standing leader Uniswap, sometimes even surpassing Uniswap, while its fully diluted valuation (FDV) and market cap are only about one-third of Uniswap's.
Raydium/Uniswap fully diluted valuation ratio: $2.872828346 billion / $9.102379018 billion = 31.5%
Raydium/Uniswap market cap ratio: $1.505604427 billion / $5.465824531 billion = 27.5%
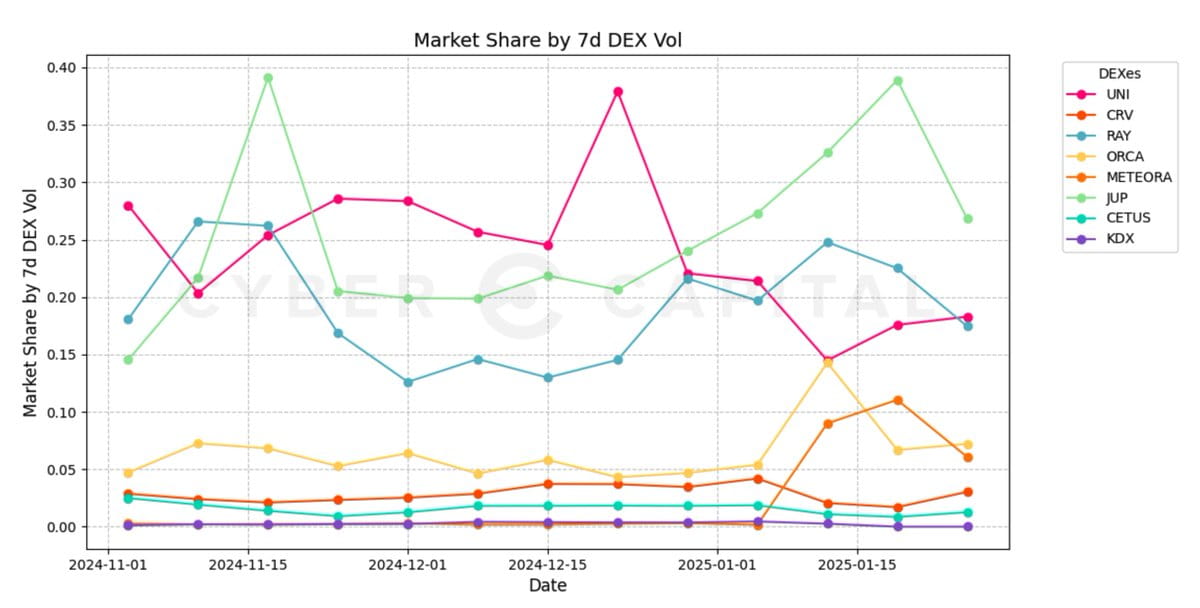
Pump.fun integration: Key partnerships, including integration with Pump.fun, have enhanced trading volume and protocol stickiness due to the migration of all new Meme pools to Raydium.
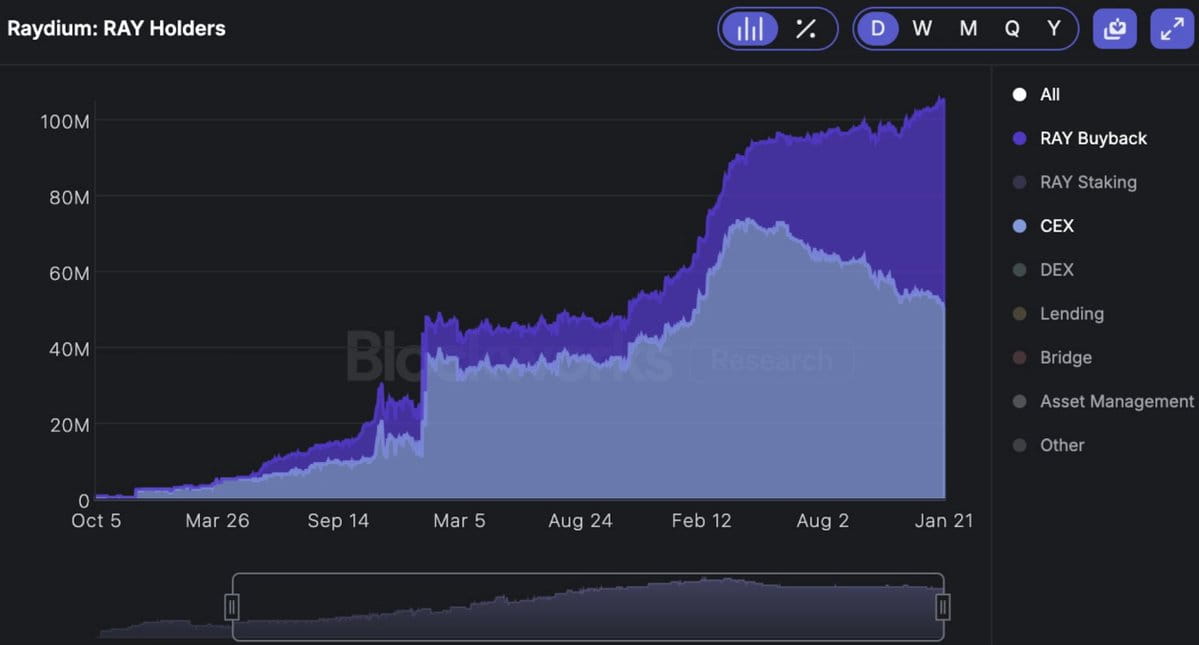
Token buyback: Raydium's 12% fee buyback plan has repurchased over 10% of the total supply of tokens, significantly alleviating sell pressure. Notably, the amount repurchased by Raydium far exceeds that held by centralized exchanges.
Jupiter (JUP) outlook is optimistic: market-leading aggregator
Liquidity aggregation advantage: Jupiter plays a key role as the dominant aggregator on Solana.
Acquisition of Moonshot: The acquisition of Moonshot allows Jupiter to integrate deposit/withdrawal channels within its decentralized exchange, enhancing competitiveness by simplifying the user experience.
Unlocking pressure: Jupiter faces a 127% increase in supply due to token unlocks, posing mid-term inflation risks. Despite a recently announced buyback mechanism, the internal estimated annual buyback rate is 2.4%, which provides some support for the token economy, but has limited impact in competition with Raydium.
Business model: Since aggregator fees are charged in addition to base protocol fees, the aggregator model faces challenges in low-fee dimensions.
Lack of competitors: As the first aggregator on Solana, Jupiter lacks strong competitors.
Meteora outlook is optimistic: rising liquidity aggregator
Aggregated liquidity efficiency: Unlike independent decentralized exchanges, aggregators like Meteora inherently possess lower downside risk and more stable capital efficiency.
Token issuance catalysts: The successful issuance of Meteora tokens may change liquidity preferences and provide long-term support for its market positioning. Unlike industry LP leader Kamino, MET points are not publicly displayed on the user interface. Moreover, since the MET points system was first announced over a year ago, there has not been any official statement regarding airdrops. While liquidity providers can achieve higher yields elsewhere in the ecosystem (such as lulo.fi), market positioning and airdrop expectations may be the main drivers for liquidity providers.
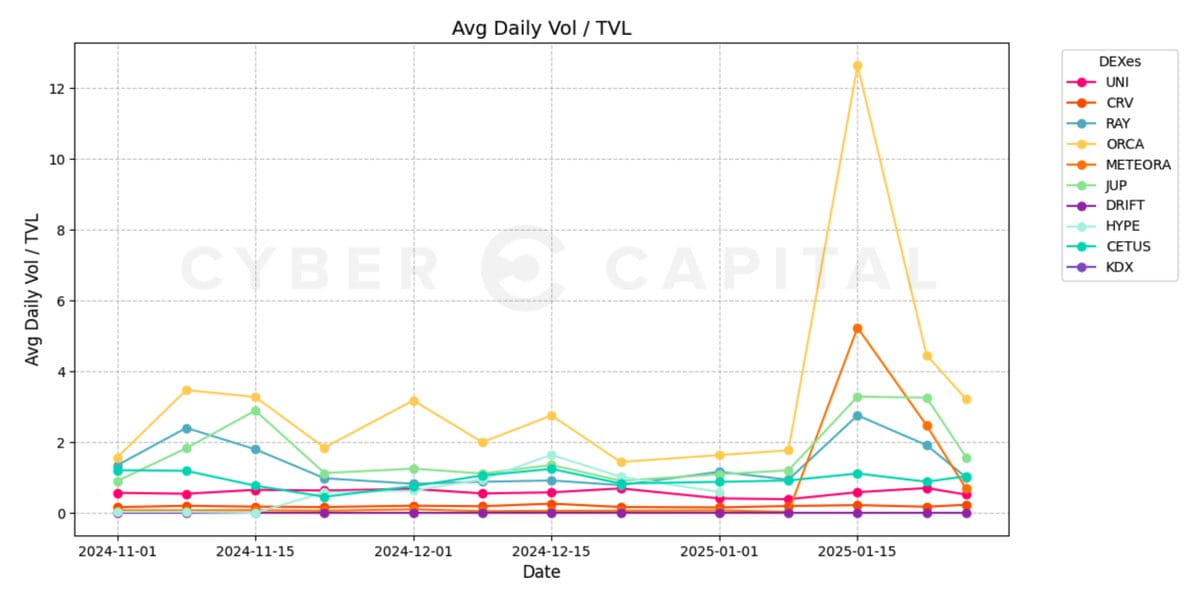
Total locked value (TVL) retention: Meteora has achieved development through significant events like the Pengu airdrop and the launch of Memecoins related to Trump and Melania. Although during the Memecoin launch, many trading pairs saw an increase in trading volume/total locked value (Vol/TVL) ratios due to temporary demand, Meteora's total locked value has continued to rise after the events, indicating good retention.
Integration development: Virtuals migrated to Solana in the first quarter of 2024 and announced integration with Meteora's liquidity pool.
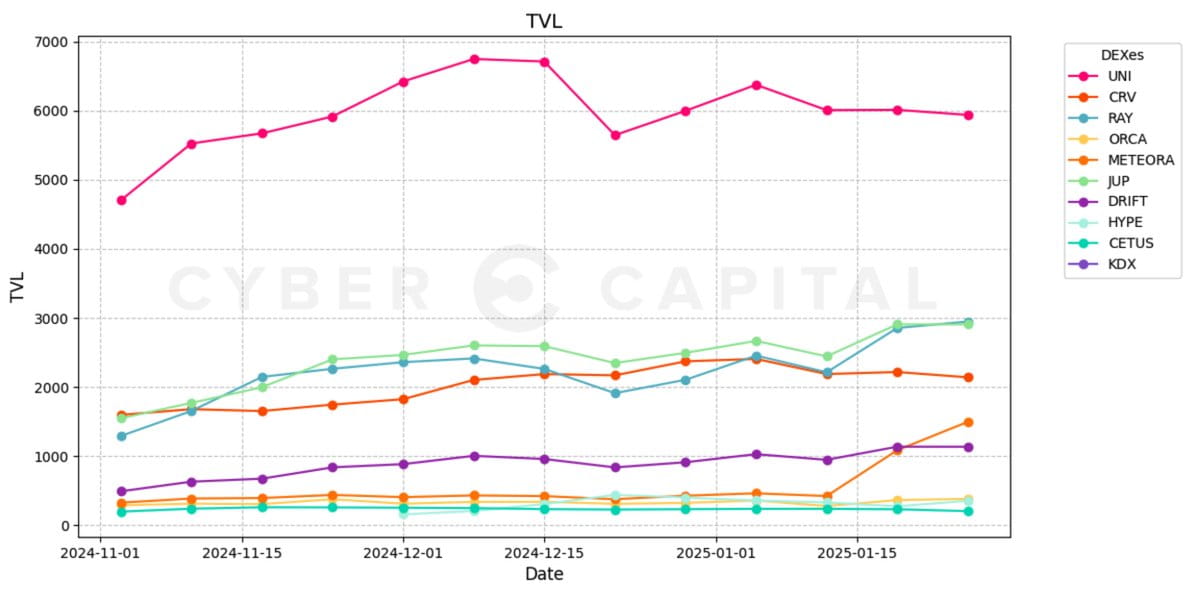
Orca's outlook is pessimistic: insufficient liquidity retention
Insufficient liquidity depth: Despite being highly efficient, Orca's pool size is significantly smaller than Raydium's, resulting in higher slippage for large transactions.
Market positioning issues: Jupiter's routing mechanism prioritizes trading platforms with deeper liquidity, leaving emerging low-liquidity decentralized exchanges and liquidity pools unappealing.
The emergence of Meteora as a liquidity aggregator further limits the competitive survival capacity of non-dominant decentralized exchanges within the routing framework, as they will only be routed if slippage costs are lower than Meteora's fee premium, which is extremely rare outside of spikes in market demand.
Limited incentives for liquidity providers: Orca lacks strong liquidity mining strategies, leading to low long-term liquidity provider retention rates.
Inefficient capital allocation: Unlike Meteora, Orca has not implemented automated yield optimization, requiring manual management of LPs, resulting in a more cumbersome user experience.
Pessimistic liquidity trends: The upcoming launch of Meteora's token may completely attract liquidity providers away from Orca, making its situation even more difficult.
Insufficient integration: Failing to reach a partnership with Pump.fun at the beginning of 2024 and recently missing the collaboration with Virtuals highlights its competitive disadvantage in acquiring orders from emerging retail-driven applications. Without upcoming catalysts to reverse this trend, liquidity migration may continue.
The above factors have led to Orca's inability to retain the additional user base acquired during peak network demand periods.
Key catalysts and risks
Catalysts to watch
RAY buyback compared to centralized exchange holdings: The buyback rate of RAY has now surpassed the total amount of RAY held by centralized exchanges, reinforcing token scarcity.
Trend of total locked value growth: The continued dominance of Raydium, Jupiter, and Meteora indicates the sustainability of long-term liquidity. Under high-pressure market conditions, the stickiness of emerging protocols is noteworthy and should not be overlooked.
Partnerships: Just as the integration of Pumpfun brought significant liquidity to Raydium, the integration of Meteora with Virtuals may yield similar effects. Given the impact of such scale partnerships on liquidity and total locked value, collaborations with less-known participants are closely watched.
Meteora's token issuance: This event may mark a turning point in the liquidity distribution of decentralized exchanges on Solana.
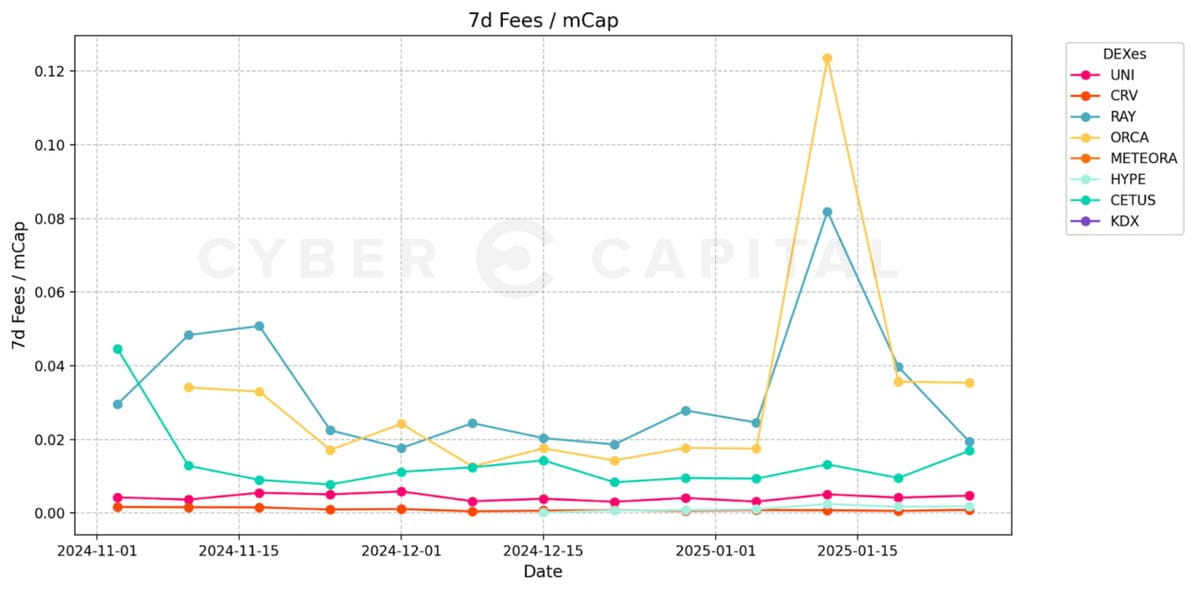
Fee to market cap ratio: Orca shows extremely high efficiency in months of strong demand, but its insufficient liquidity retention hinders long-term competitiveness. On the other hand, JUP faces the opposite situation, constrained by its business model. Compared to the latest 'hot project' Hyperliquid, Raydium generates ten times the fees at one-eighth of the fully diluted valuation.
Risks
Inflation pressure of JUP: Although Jupiter's position as an aggregator is solid, its large token supply may cause short-term price pressure.
Decline in Orca's market share: If the trend of liquidity providers migrating continues, Orca may face ongoing liquidity loss.
Meteora airdrop and token economics execution risks: Despite strong early growth in total locked value, its token economics and incentive structure remain untested.
Conclusion and investment outlook
The landscape of decentralized exchanges on Solana is shifting towards higher efficiency and deeper liquidity concentration. Raydium's outstanding liquidity positioning, proactive buyback mechanisms, and market dominance make it a highly confidence-inspiring decentralized exchange for investment. Jupiter's role as an aggregator remains crucial and provides competitive barriers, but token supply dilution poses resistance in the short term. Orca, once a competitive player, now faces severe challenges in liquidity retention and capital efficiency, becoming an increasingly fragile asset, indicating missed key integrations and difficulties in competing directly with mature players. Meteora is expected to rise after successfully launching its upcoming token. Based on our current theory, investment positions in decentralized exchanges should focus on the leading decentralized exchanges, decentralized exchange aggregators, and liquidity aggregators within a given ecosystem, while emerging participants that meet the catalyst criteria can also hold small positions.