


Original author: Maria, Electric Capital
Original text compiled by: 1912212.eth, Foresight News
The sixth annual Electric Capital developer report involved 829 contributors, analyzing a record 902 million code submissions across 1.7 million code repositories.
How is the crypto industry data performing in 2024?
Key points summary:
The crypto industry has a global nature, with developer momentum shifting from North America to other regions.
Developers and use cases are showing diverse development across different ecosystems.
Applications span all time zones, indicating widespread usage globally.
We underestimated the number of developers in the crypto space because our statistics only focus on open-source development activities.
Our methodology includes:
Combine developer profiles into a single standard identity.
Identify and exclude bot accounts.
Remove code repositories that do not reflect development activity, such as data lists.
Since Ethereum's launch in 2015, the crypto industry has grown at an average annual rate of 39%. In 2015, the number of monthly active developers was about 1,000. Today: the number of monthly active developers has risen to 23,613.
In the past year, the number of monthly active developers has slightly decreased by 7%.
However, the number of developers working in the crypto industry for over two years has grown by 27%.
These experienced developers drive industry growth as they contribute 70% of the code submission volume.
How has the crypto industry changed since 2015? Let's take a look at the global diversity of crypto developers.
The geographic focus of developer distribution has shifted from the US and Europe, which accounted for 82%, to other regions of the world.
Asia now has the highest proportion of developers, with one in three crypto developers residing in Asia. Europe ranks second. Since 2015, North America has dropped from first to third place.
We can identify the top ecosystems in these continents based on developer share.
In terms of developer share, Ethereum ranks first in every major continental block.
Solana ranks second.
Polygon ranks third in Asia and South America.
Polkadot ranks third in Europe.
Base ranks third in North America.
Dfinity ranks third in Africa.
The United States, India, the United Kingdom, China, and Canada hold the largest shares of global crypto developers.
The United States still has the highest share of crypto developers, but it has been declining steadily since 2015. India has risen from 10th to 2nd place.
Top three ecosystems by developer share by country:
Ethereum ranks first in the US, UK, China, and Canada, and second in India.
Solana ranks first in India and second elsewhere.
Base ranks third in the US and India.
Polygon ranks third in the UK.
NEAR Protocol ranks third in Canada.
Polkadot ranks third in China.
India welcomed the most new crypto developers in 2024. 17% of new crypto developers are from India.
Let's focus on new developers—39,148 new developers explored the crypto space in 2024. We can break down these new developers by ecosystem.
Solana became the ecosystem with the most new monthly developers added in July 2024.
Overview of new developers in 2024: Solana is the ecosystem with the most new developers, ranking first.
Ethereum ranks second. Dfinity, Aptos, Base, Bitcoin, SuiNetwork, NEAR Protocol, Polkadot, Polygon, and Starknet all have over 1,000 new developers joining.
Arbitrum, BNBCHAIN, Optimism, StellarOrg, and ton_blockchain all have over 500 new developers joining.
Who is growing the fastest in total developer numbers? Total developer numbers reflect the interest of new developers and hackathon participants.
According to data from Q3 2023 and Q4 2024, the top ten ecosystems with the fastest growth in total developer numbers are:
Who is growing the fastest in terms of full-time developer numbers? Full-time developers submit code for more than 10 days each month, thus contributing stable work to the ecosystem.
According to data from Q3 2023 and Q4 2024, the top ten ecosystems with the fastest growth in full-time developers are:
Many developers are active across multiple chains—now, one in three crypto developers works on multiple chains, and this trend is growing. The number of monthly active multi-chain developers has increased from less than 10% in 2015 to 34% in 2024.
The chain with the most multi-chain developers shares developer resources with Ethereum.
EVM chains share the most developers and have significant network effects: 74% of multi-chain developers work on EVM chains.
Since 2021, the proportion of EVM cross-chain deployers has increased fourfold.
Base is the most popular chain among EVM multi-chain deployers in 2024, but Base deployers tend to stay on the Base chain.
Since deployers publish code across multiple chains, where is most of the original code written?
Before 2020, almost all original on-chain code logic on EVMs was on Ethereum.
Currently, no EVM chain's code innovation share exceeds 30%.
Base now accounts for 25% of all original on-chain code logic across EVM chains, the most among all major EVM chains.
This is how the Ethereum ecosystem maintains its leading position in code innovation—through L2 chains. 65% of innovations occur on the mainnet and ETH L2 chains.
The Ethereum ecosystem demonstrates strong network effects through its dominance among EVM and multi-chain developers. How is this ecosystem performing?
Ethereum has 6,244 monthly active developers, down 17% year-on-year.
Most losses come from developers who joined after 2021. Among developers who have already worked on Ethereum, those with over 2 years of experience have increased by 21%.
Now more than half of Ethereum developers work on Ethereum L2 chains, up from 25% in 2022.
Ethereum L2 chains have experienced significant growth in developers over the past 4 years. The total number of monthly active developers on Ethereum L2 chains is 3,592, with an average annual growth of 67% since Arbitrum launched in 2021.
Base is the largest Ethereum L2 chain.
Arbitrum, Starknet, and Optimism each had over 2,000 developers in 2024.
In 2024, the number of monthly active developers for Bitcoin is 1,200, remaining stable. The number of experienced Bitcoin developers (those who have worked on Bitcoin development for more than 2 years) is steadily increasing. Currently, the number of monthly active experienced Bitcoin developers has reached 672, setting a new record.
42% of Bitcoin developers—almost half—are working on Bitcoin scaling solutions.
Zero-Knowledge Proofs (ZK) is a developer-centric field derived from research. How is its development?
Over 2,000 monthly active developers work in the ZK ecosystem, of which 823 are full-time developers who submit code for more than 10 days each month.
On-chain deployments of Zero-Knowledge Proofs (ZK) have also increased from 40 in 2020 to 639 in 2024.
Although the numbers remain fairly flat, they show clear growth. The number of deployers has also increased.
ZK is also gaining traction—contracts using ZK precompiles have increased from 47 in 2020 to 680 this year.
When are Zero-Knowledge Proof (ZK) developers and users active?
Deployers of ZK Rollup contracts are active during working hours in the Eastern Hemisphere, and ZK users are likewise.
ZK users and deployers seem to be concentrated in the Eastern Hemisphere, particularly in Eastern Europe, Africa, and Asia.
NFT and DeFi are established application scenarios in the crypto space—most top smart contracts relate to NFTs or DeFi. How are these application scenarios developing? Let's start with NFTs.
On all major NFT active chains (Bitcoin, Ethereum, Polygon, Solana, Zora, Base), NFT deployments have increased more than threefold year-on-year.
NFT deployments have reached an all-time high. 87% of new deployments occur on Base and Zora.
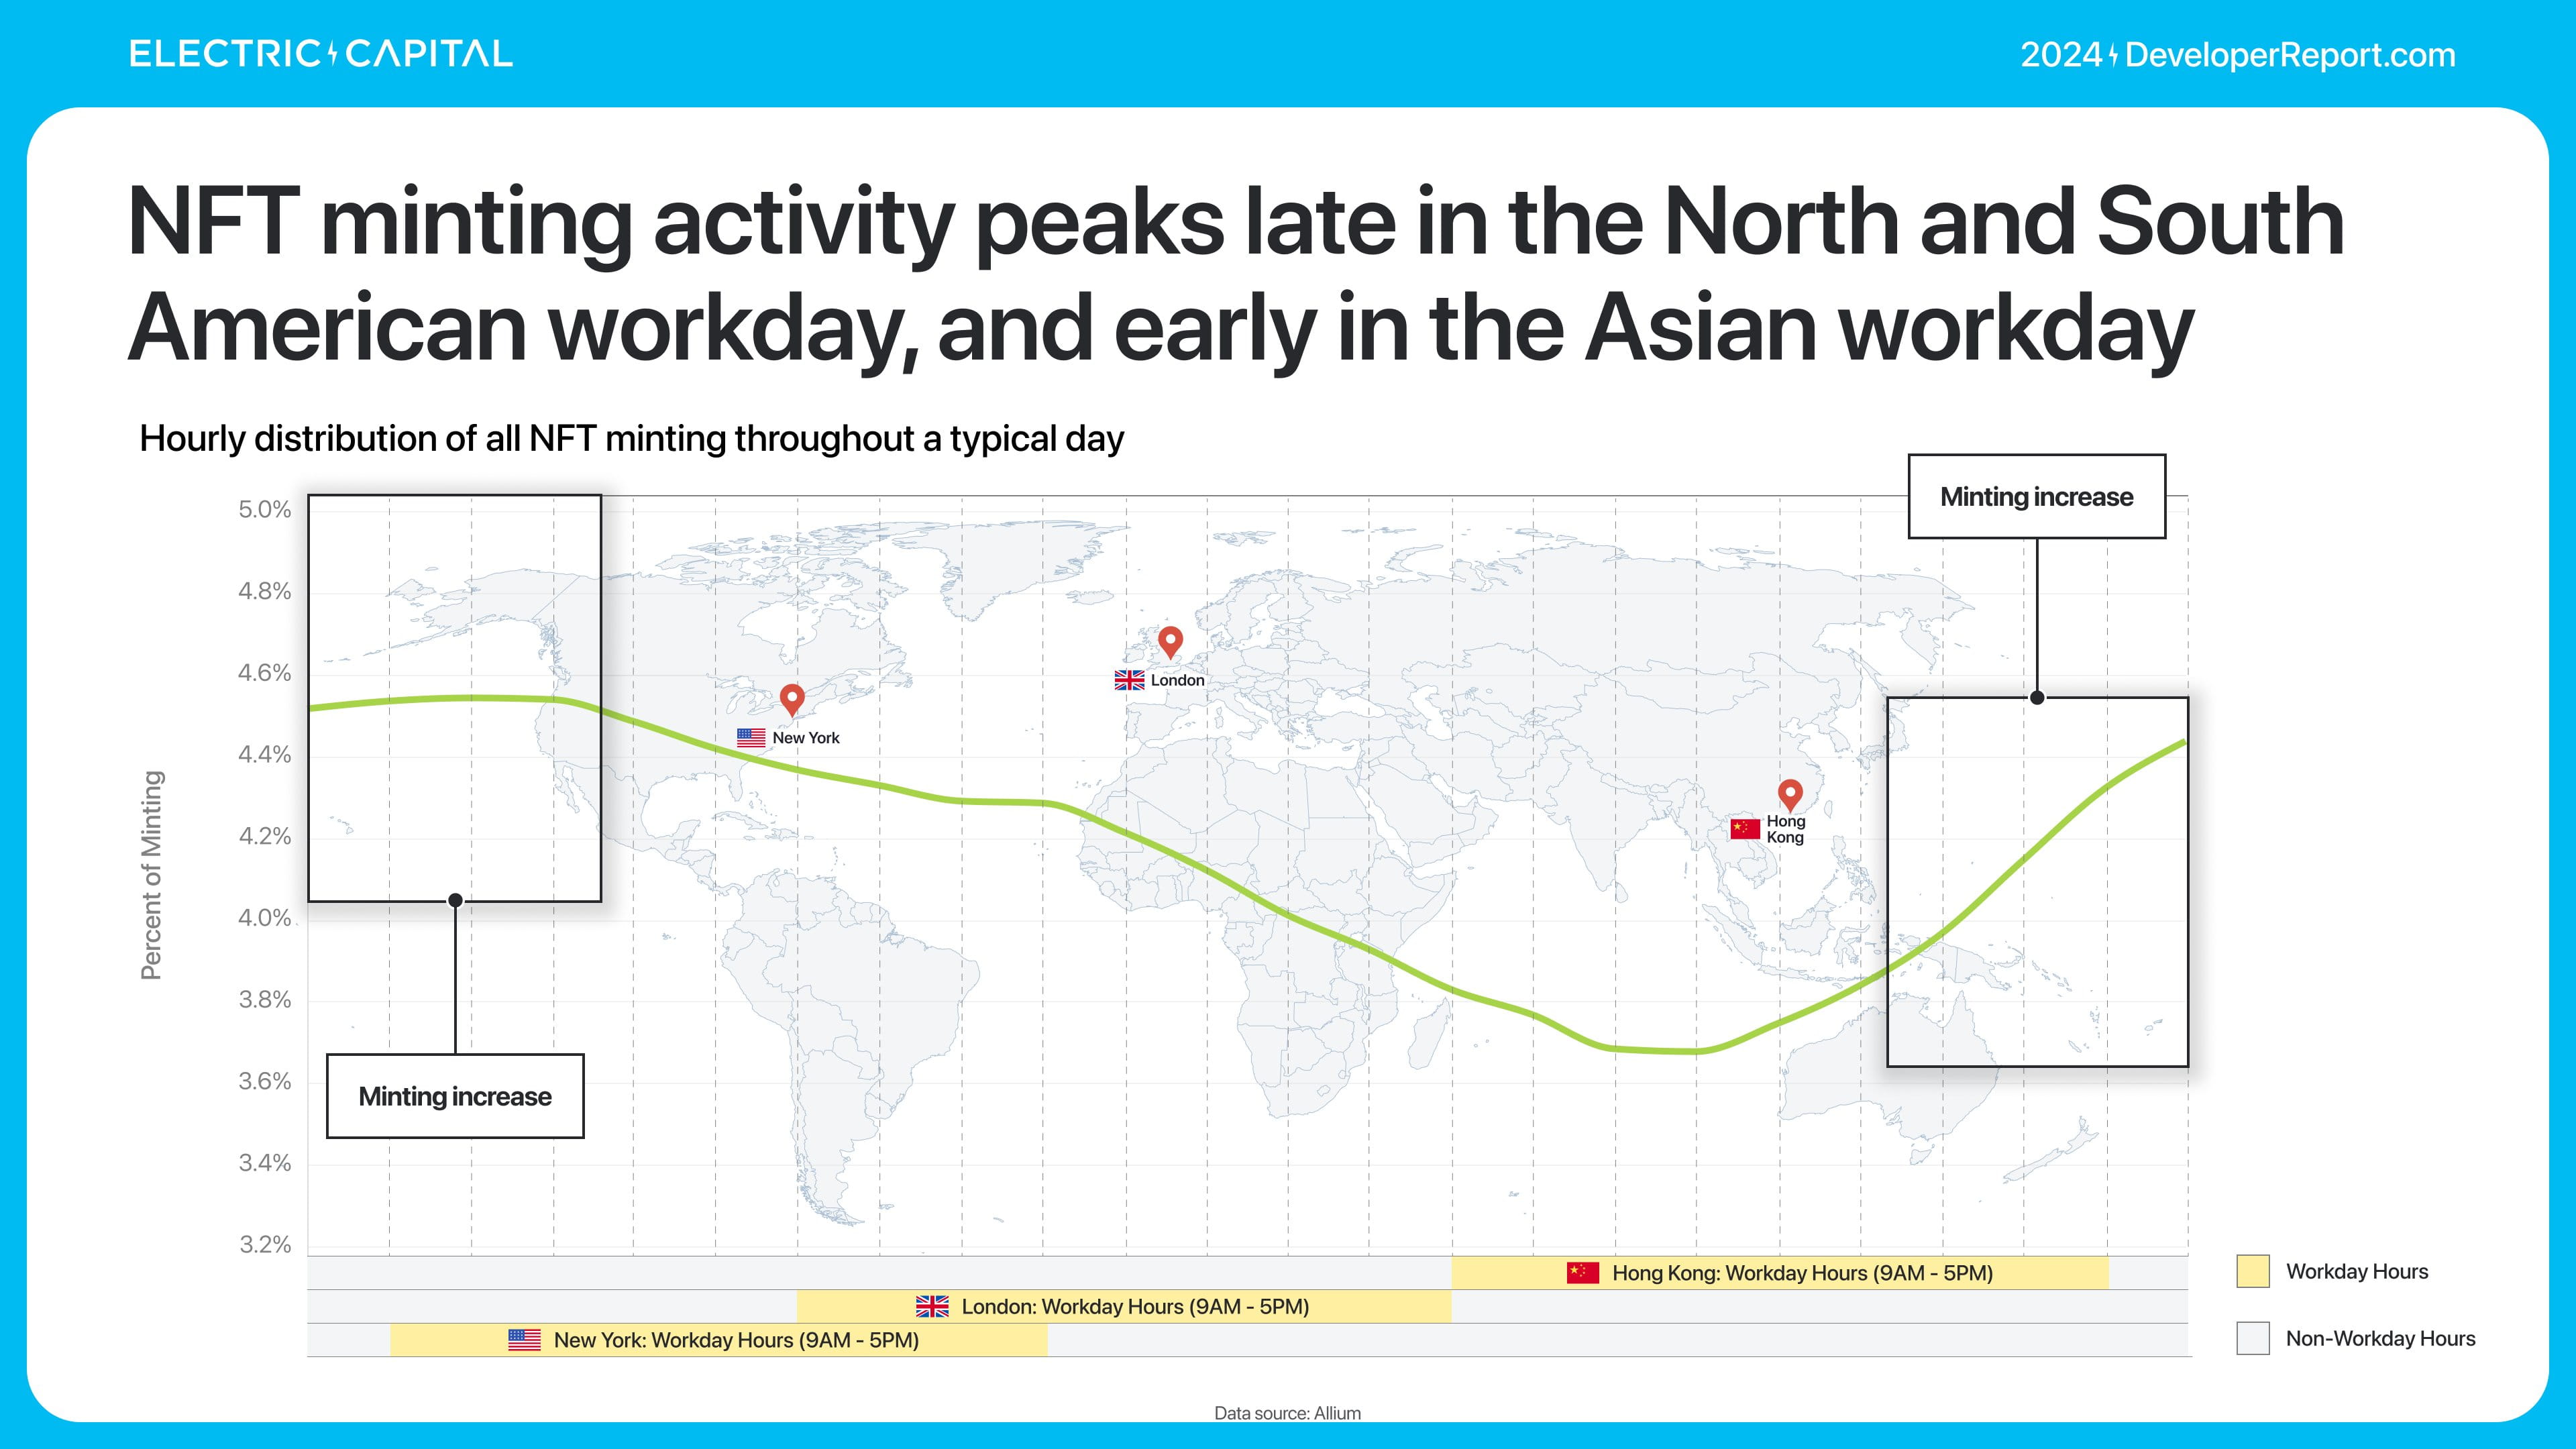
NFT activity has significantly shifted towards minting.
In 2024, NFT minting reached an all-time high, with 97% of minting occurring on Base.
Solana has 57% of minting wallets, capturing 64% of minting transactions.
The increase in minting activity is because NFTs have surpassed the art domain in 2024, covering more application scenarios.
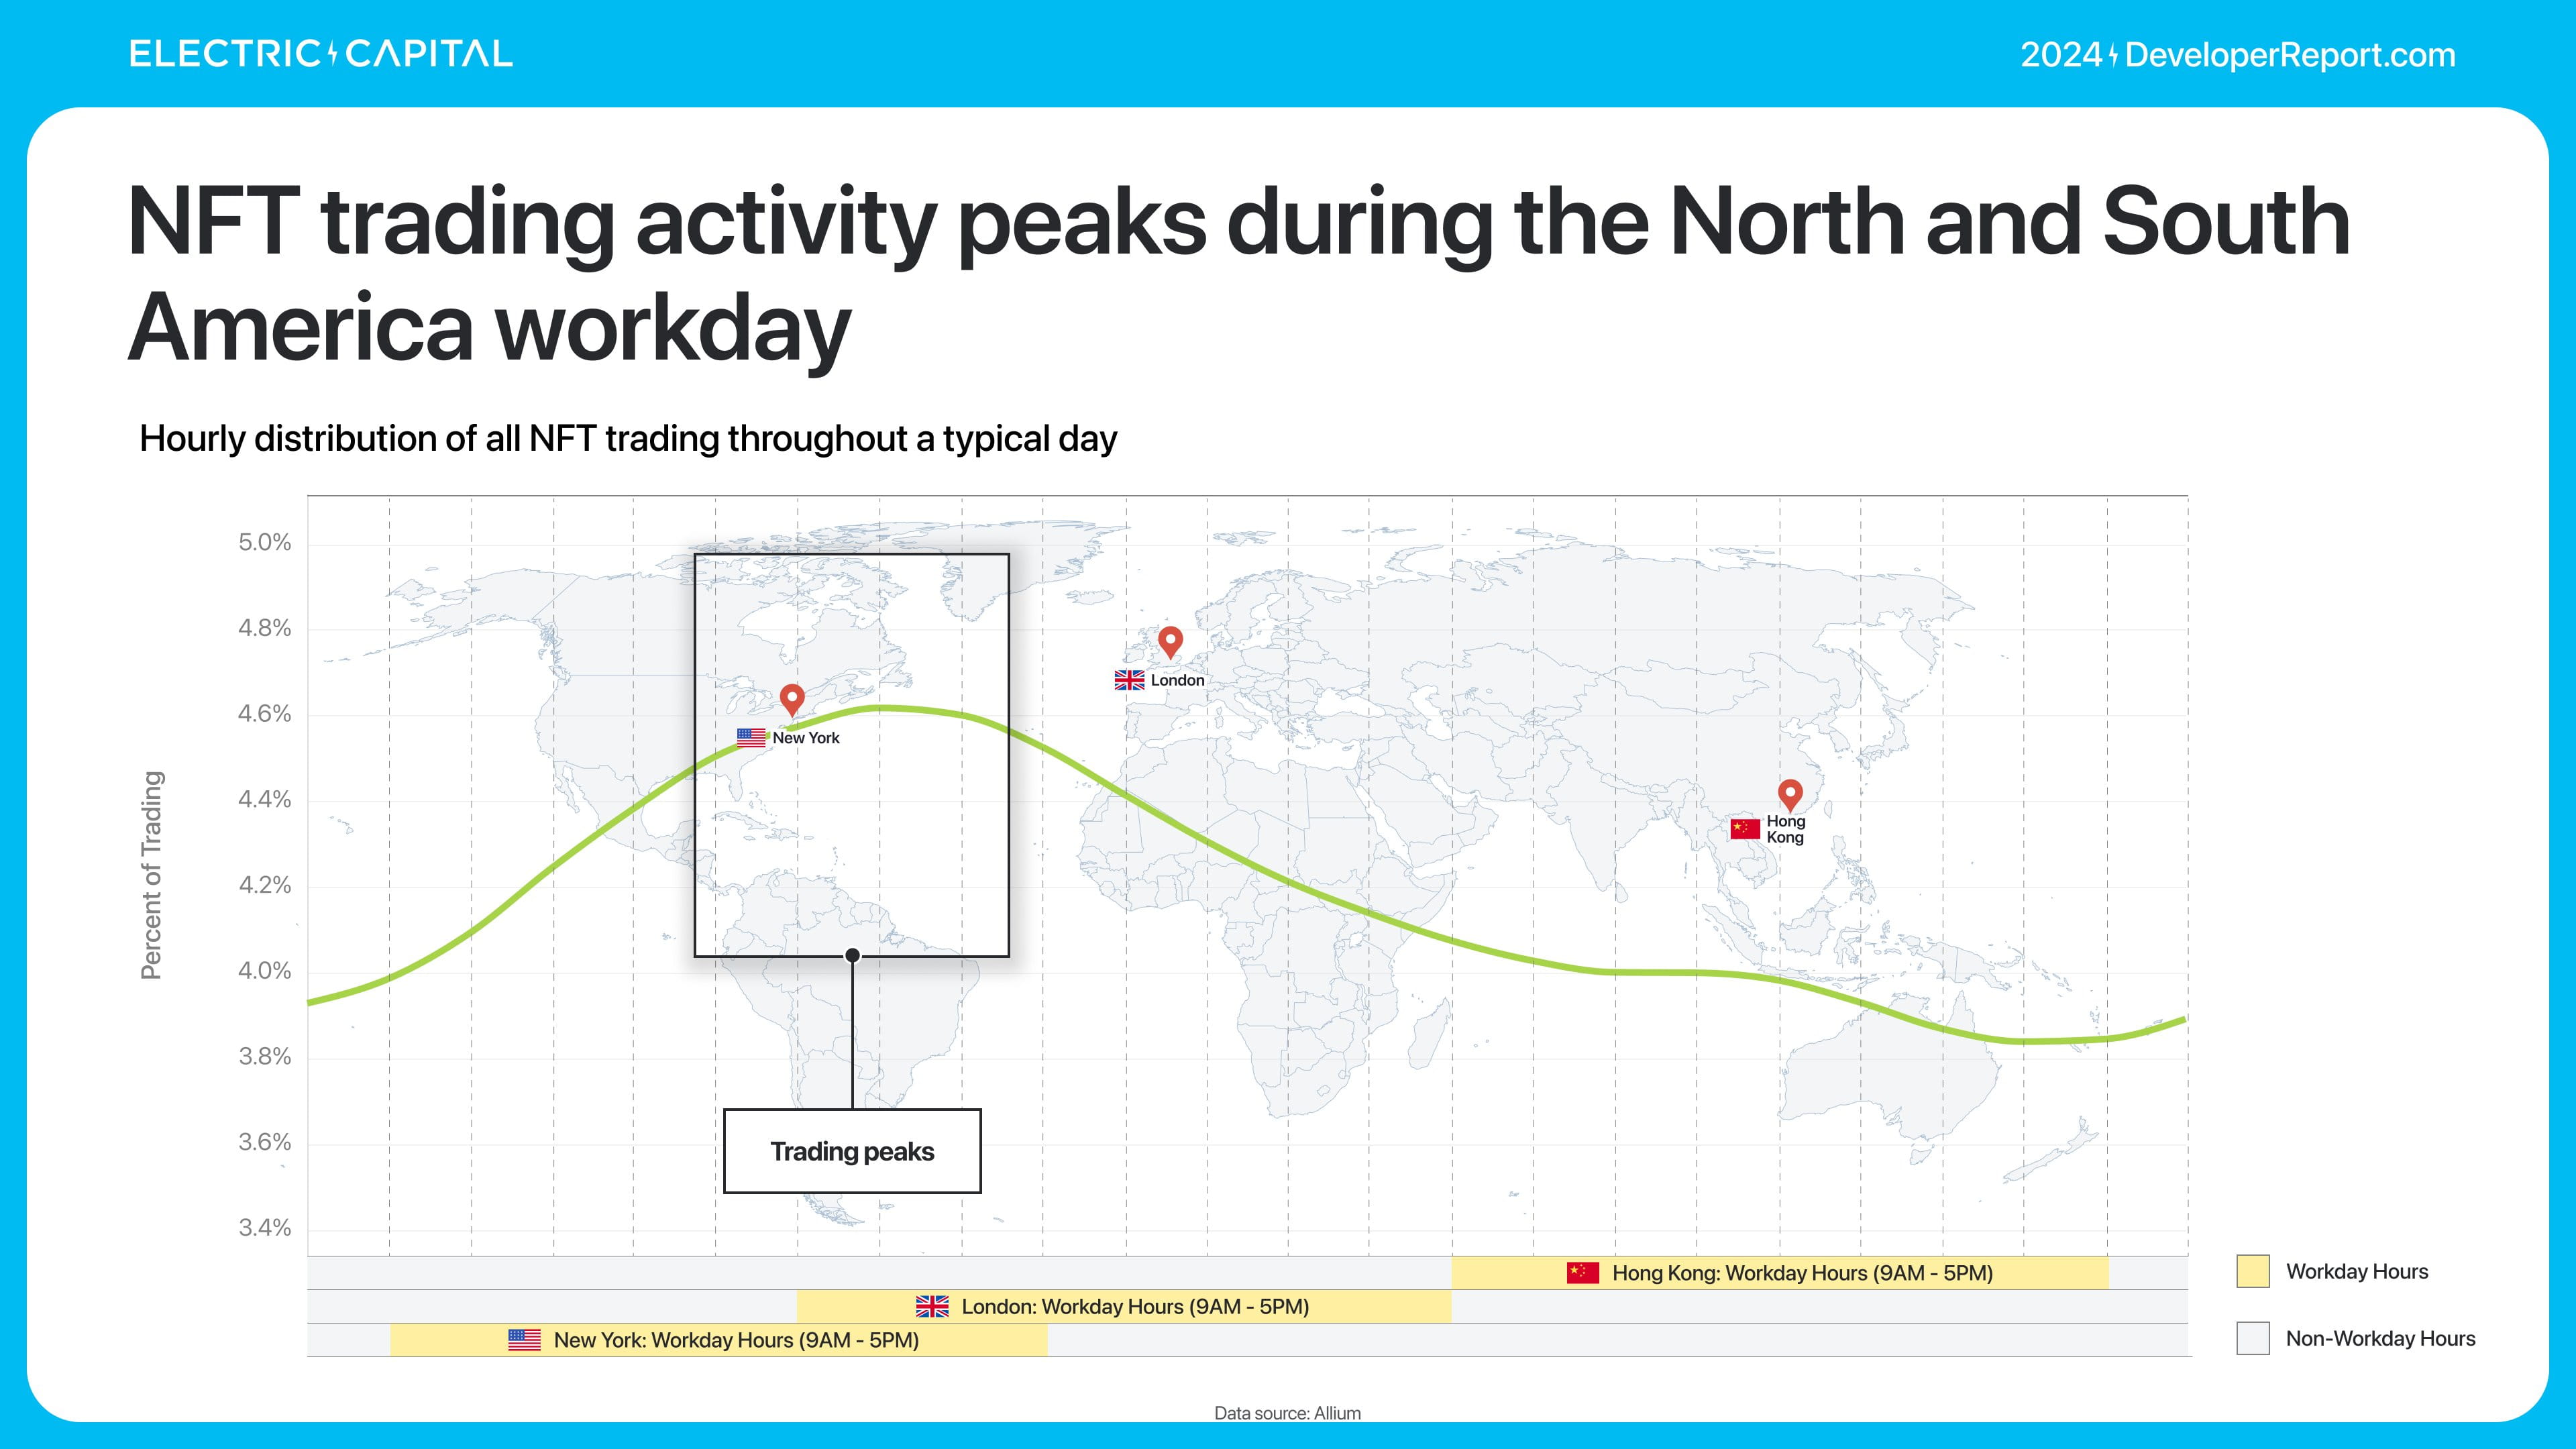
NFT trading remains an important foundational application and has expanded from OpenSea to platforms like Magic Eden and Tensor.
The trading volume of NFT minting and trading peaks in different regions—indicating different user groups.
3,532 monthly active developers are engaged in DeFi development. DeFi developers are experienced—of these, 2,097 (59%) have worked in DeFi for over 2 years.
53% of DeFi developers work on Ethereum and its L2 chains.
In 2024, the total value locked (TVL) in DeFi grew by 89%.
Ethereum's TVL is dominant, being 7 times that of the second largest chain.
Most of the TVL has consistently been concentrated in Ethereum.
Non-Ethereum TVL has grown from 3% to 36% in 3 years.
The largest leap in TVL share occurred in Solana.
What is driving the growth of all this TVL? We can classify DeFi developers by developer type.
In the past year, restaking has grown by $29 billion in TVL.
LRTs have grown to over 3.5 million ETH.
46% of LRTs are used in DeFi.
Most LRTs are deposited in money markets, yield, interest rate derivatives, and bridging platforms.
Eigenlayer has facilitated the creation of LRTs as a field. So, how is the developer ecosystem of Eigenlayer developing?
There are 252 monthly active developers working in the Eigenlayer ecosystem. Eigenlayer's developers are highly engaged: 39% are full-time developers, and more than half have worked in this ecosystem for over 2 years.
TVL is not the only metric we use to understand DeFi usage. Although the TVL of lending platforms is three times that of DEXs, DEXs have more unique address transaction volume. For example, the unique address interactions of DEXs compared to lending platforms in 2024 show that Uniswap had 72 times the unique address interactions of AAVE.
In 2024, DEX transaction volume nearly doubled, reaching $209 billion monthly.
Solana and Ethereum processed the most transaction volume—over twice that of the second-largest chain.
Solana settled the most transaction volume in 2024, reaching $574 billion. The total DEX transaction volume for Ethereum mainnet and its L2 chains was $931 billion.
Solana dominated the application scenario of low-fee DEXs. In 2024, its transaction volume increased more than threefold, reaching 646 million transactions in a single month.
81% of DEX transactions come from Solana.
In terms of trading wallets, excluding wallets with only 1 transaction and amounts below $1, Solana has the most independent trading wallets, seven times that of the second-largest chain.
Base has the second most independent trading wallets, excluding Solana.
Base and Solana are very popular for small transfers. The average amount of wallet transactions on these chains is the smallest.
Ethereum is the most favored for high-value transfers. The average amount of wallet transactions on Ethereum is the largest.
Where are all these DEX users? We can understand DeFi usage through DEX, as financial activities often start or end with DEX.
Global activity varies across different chains—the more evenly distributed the activity, the more global the usage. Ethereum and Solana have the most evenly distributed usage.
Stablecoins are one of the largest global crypto application scenarios. How are stablecoins performing? The usage of stablecoins has reached an all-time high: the total amount of stablecoins in circulation is currently $196 billion, with a daily trading volume of $81 billion—both of which are historical records for stablecoins.
USDC and USDT account for 95% of the trading volume.
Ethereum is the first ecosystem for stablecoins—59% of stablecoins are issued on Ethereum.
What is the global activity status of stablecoins?
Stablecoins remain active, but trading volume has increased by 2-3% during working hours in Asia, Europe, and Africa.
Despite stablecoin trading peaking during working hours in the Eastern Hemisphere, the trading volume is more inclined to the Western Hemisphere.
Bitcoin and Ethereum ETFs launched this year, providing a convenient way for off-chain capital to enter on-chain assets. The Bitcoin ETF attracted over $50 billion in net inflows, becoming one of the most successful ETFs in history.
The majority of trading volume for Bitcoin ETFs comes from retail investors.
Despite being in the early stages, Bitcoin ETFs are being purchased by institutional investors at a record pace.
Ethereum ETFs were launched this July. Currently, the Assets Under Management (AUM) for Ethereum ETFs is $13 billion, attracting $3.5 billion in net inflows. This performance is comparable to the most successful ETF launches since 2022 (excluding Bitcoin ETFs) and is mainly driven by retail investors.
Bitcoin and Ethereum ETFs set historical records. In their first year, the cumulative inflows have exceeded twice that of the most successful ETFs in history.