


Original title: "CRYPTO THESES 2024"
Original source: Messari
Original translation: TechFlow
As promised, the well-known crypto data and research organization Messari released "Messari Theses 2024". We have compiled and translated the first chapter for you, the top ten investment trends in 2024.
In the author's opinion, Web3 is a very stupid concept. When people stopped using this term and returned to the "Crypto" narrative, the total market value of cryptocurrency doubled.
In this year's investment trend forecast, Messari expressed strong optimism about Bitcoin. At the same time, it was bearish on Ethereum, thinking that the "ultrasonic currency" (referring to continued deflation leading to continued growth) narrative is nonsense, and Ethereum does not have an overwhelming advantage over Solana. In addition, Messari is strongly optimistic about the combination of AI and cryptocurrency. Judging from the subsequent disclosed analyst positions, many people hold tokens such as AKT\TAO. Messari is also optimistic about the three emerging narratives of DePIN, DeSoc, and DeSci.
Welcome to read the full text:
1.0 Investment Trends
Last December, I abolished the term Web3 on behalf of everyone in the cryptocurrency space.
It’s a bullshit, PR-speak word that undermines every interesting thing we’re trying to build.
NFT PFP Collection is Web3, DeFi 2.0 is Web3, Sam Bankman-Fried is Web3...
In the crypto world, I want more things like personal wallets, transaction privacy, infrastructure advancements, DeFi, DePIN, and DeSoc that don’t rely entirely on Ponzi schemes.
This year, it did not disappoint.
Since the cold-blooded murder of the word Web3, the cryptocurrency market cap has nearly doubled. The biggest fraudsters in our industry are either in jail or headed there soon.
Great products with sleek design are launched, and I am even more excited about the prospects for cryptocurrencies in 2024.
In short, the state of the crypto market is strong.
I realize there are some newcomers reading this, so I want to remind you that this is an advanced course, not an introduction for beginners.
I'm going to assume you already have the relevant knowledge and I'm going to be brief because time is an important factor.
This opening “Investment Trends” section is for those of you who want to tell your friends you read the entire report. I don’t feel the need to start a victory lap on the first three sections of my report last year, but we are seeing tailwinds in various market segments and evidence to support the recent much-needed optimism after a long crypto winter.
We’ll start this article with the bull case for Bitcoin in 2024.
1.1 BTC and digital gold
“Where are we now? It’s a bit like January 2015, or December 2018, but it’s more like selling a kidney to buy more Bitcoin.”
The above is my view on Bitcoin as of December 2022.
While predicting where Bitcoin will trade in the short term is difficult, its appeal over longer timescales is almost undisputed.
We don’t know if the Fed will raise rates further, or slam on the brakes, reverse course, and begin QE in earnest. We don’t know if we’ll be facing a commercial real estate-driven recession, or if we’ll successfully achieve a “soft landing” for the economy after post-COVID monetary and fiscal whiplash. We don’t know if stocks will fall or oscillate, or if Bitcoin will prove correlated with tech stocks or gold.
On the other hand, the long-term thesis for Bitcoin is straightforward. Everything is being digitized. Governments are over-indebted and profligate, and they will continue to print money until they fail. There are only 21 million Bitcoins that investors can acquire. The most powerful MEME on the market is the upcoming Bitcoin halving in 2024, which is its quadrennial marketing event.
Sometimes you just have to keep it simple!
For year-over-year consistency, let’s revisit the MVRV chart I wrote last year that will make you want to sell your kidney to buy it. Recall that the chart compares Bitcoin’s current market value (MV, which is price * total supply) and realized market value (RV, which is the sum of the products of price * unit supply at the time each unit was last moved on-chain).
In the calculation theory above, if the ratio of the two is below 1, it is the golden zone. A ratio above 3 always marks the peak of a cycle.
After a 150% rally this year, is Bitcoin still a good “buy”?
The answer is quite affirmative.
Perhaps we are no longer in deep value territory, but given some of the institutional tailwinds currently supporting us (ETF approvals, FASB accounting changes, new sovereign buyers, etc., see Chapter 4.1), it is clearly no longer a blind leap of faith for investors to buy Bitcoin at an MVRV ratio of 1.3.
Keep in mind that as more Bitcoin inevitably gets locked up in ETF products, the MVRV ratio will also be artificially higher, as new buyers will not be appearing on-chain as often compared to trading recorded on the NYSE and Nasdaq. An MVRV ratio just above 1 is well below the historical median.
You know what’s more fascinating, assuming you’re interested in cryptocurrencies as an asset class.
Bitcoin tends to lead recoveries. We recently saw new multi-year highs in Bitcoin dominance, but it’s still not close to the highs we reached in 2017 and at the start of the 2021 bull run. In 2017, Bitcoin’s dominance shrank from 87% to 37%. It recaptured 70% before its consolidation phase and run to $40,000 in 2021, then fell to 38% at the peak of the bubble. We just hit 54%. There’s room for consolidation.
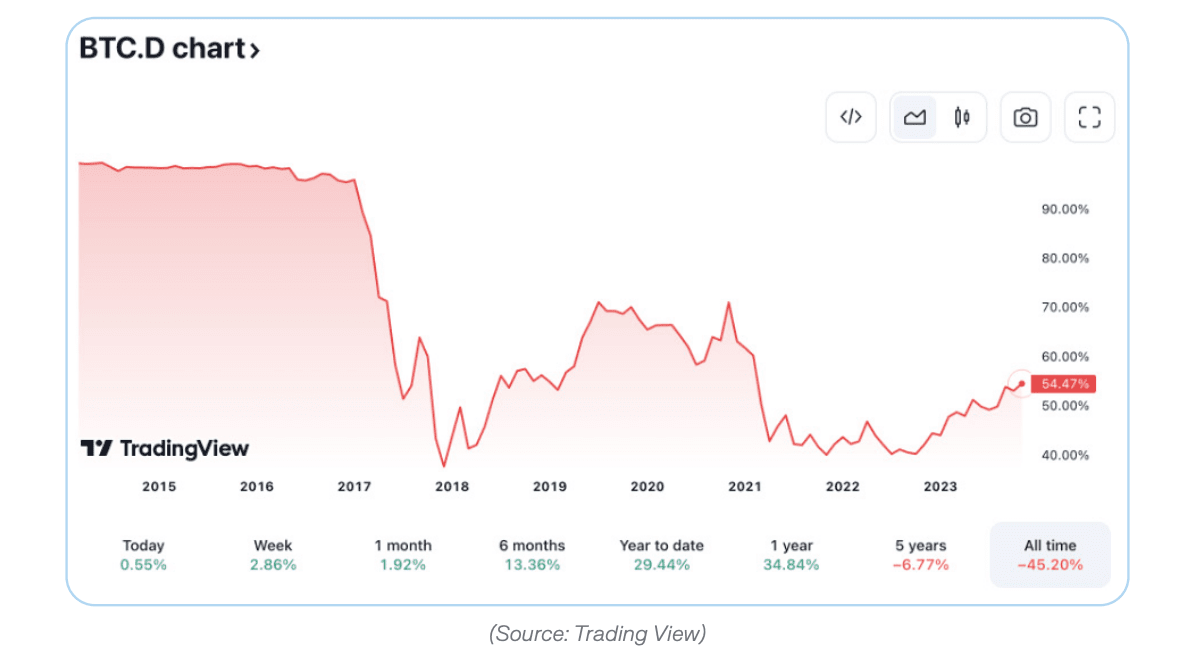
Honestly, it’s hard to see the catalyst for another crypto boom not starting with a sustained surge in Bitcoin.
DeFi faces continued regulatory headwinds that will limit growth in the short term. NFT activity is essentially dead. Other upcoming sectors (stablecoins, gaming, decentralized social and infrastructure, etc.) are more likely to rise slowly and steadily rather than sharply and suddenly.
Large money managers agree. Binance did some excellent research recently showing that “Bitcoin” sentiment overwhelmed “crypto” sentiment among asset allocators during the summer (although perhaps that sentiment is shifting as ETHBTC underperforms).
With momentum like this, my bet is that Bitcoin dominance will revisit 60% during either an ETF-driven rally (leading the way up) or severe macro pressure (consolidating on the way down).
Even if I am wrong and we have seen the highs for Bitcoin dominance this cycle, I feel the likelihood of a nominal and relative decline in Bitcoin price is extremely low.
In the early stages of the crypto bull market, the highest expectation play has been betting on the leaders, and this cycle has been (and will continue to be) the same.
I will reiterate what I said last year: I find the “ultrasonic money” argument for Ethereum completely unconvincing. If such a MEME had strength, the liquidity data would not look like this, even after the approval of the ETH futures ETF:
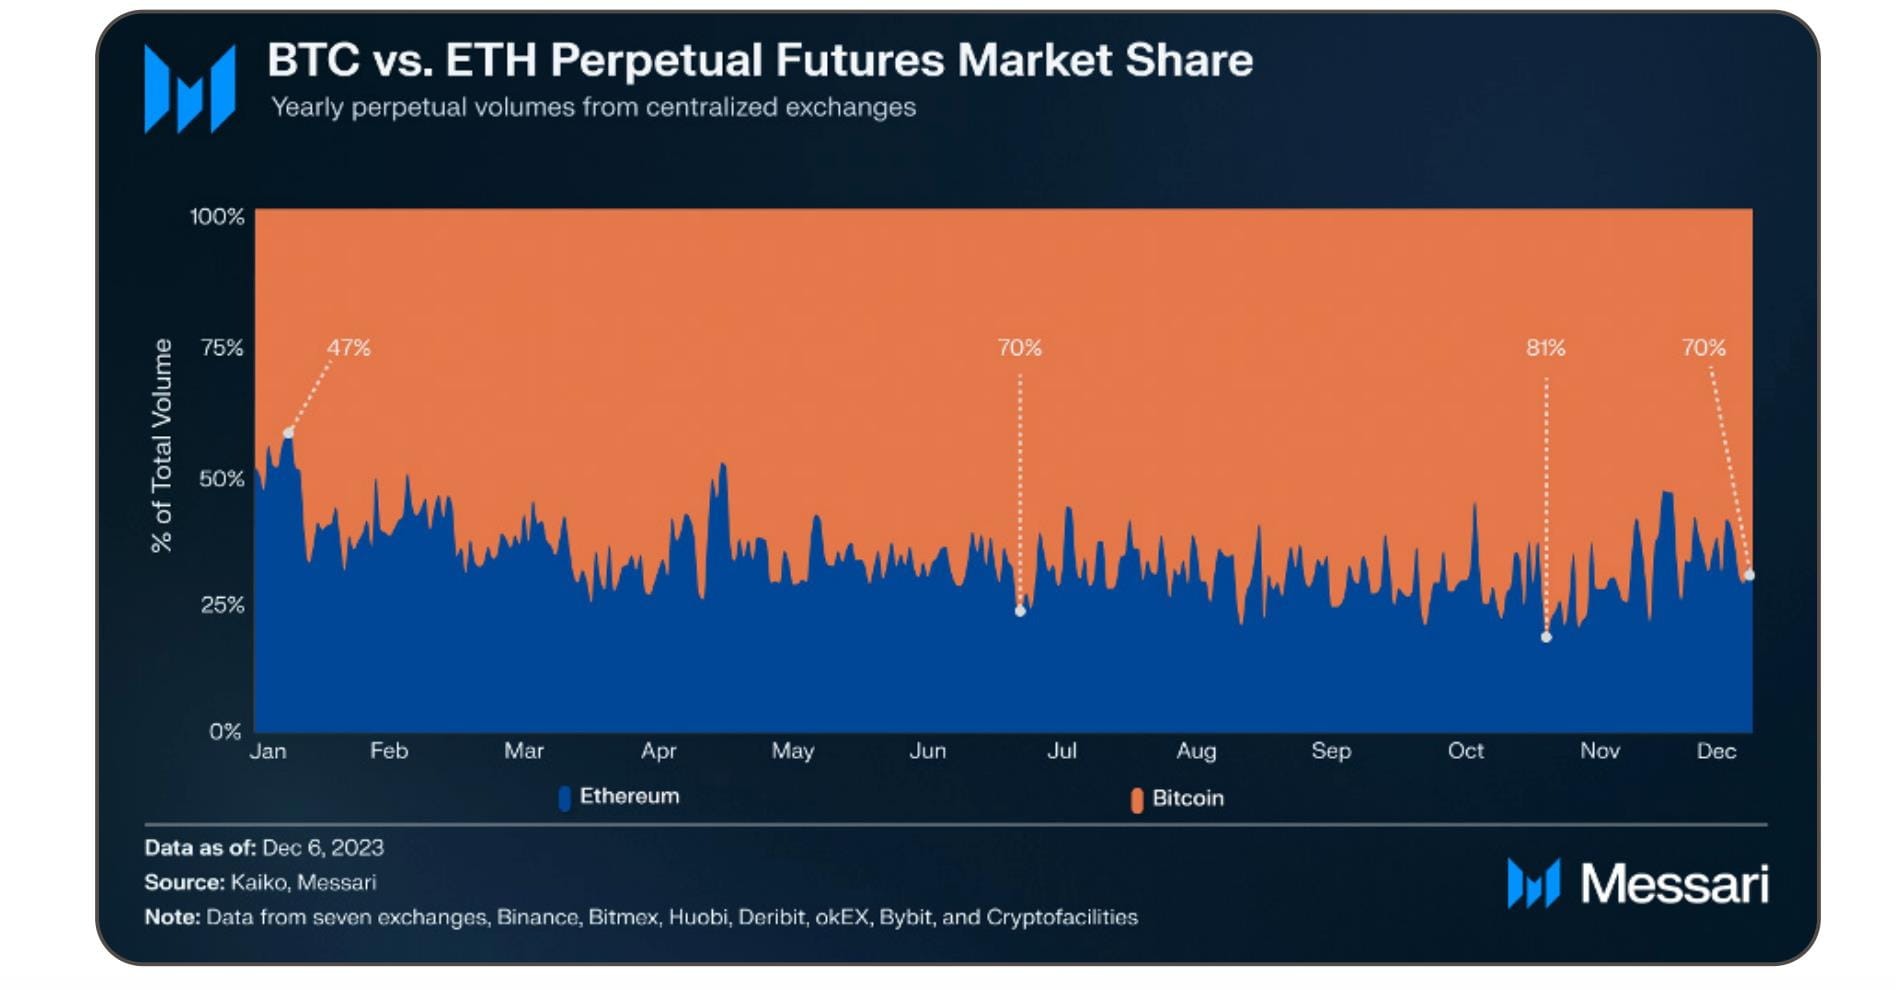
We may not see another 100x rally in Bitcoin, but the asset could easily outperform other established asset classes again in 2024. Eventual parity with gold would put the price of each BTC at over $600, 000. Remember: gold shares many of the same macro tailwinds, so that price is not necessarily a ceiling.
If a currency crisis is severe enough, cryptocurrencies will become worth something: 1 BTC is worth 1 BTC.
[Related reading: BTC Q3 report]
1.2 Ethereum
Ethereum’s successful “Merge” in September 2022 and “Shapella” upgrade in April 2023 are among the most technically impressive upgrades ever. The “Merge” also kicks off a new era for Ethereum as a net deflationary digital asset. I love Ethereum and everything that has spawned it. Messari itself wouldn’t exist without the cryptoasset ecosystem Vitalik built. But in the long run, the investment case for ETH is more like Visa or JPMorgan than Google or Microsoft, or commodities like gold or oil. ETH is in between. BTC outperforms ETH in digital currencies due to institutional allocators’ interest in the “pure play” of digital gold, while widely available Ethereum alternatives (L0s, L1s, L2s) may outperform as they absorb on-chain transaction volume relative to the Ethereum main chain. I don’t see a case for ETH to outperform Bitcoin and the upcoming high beta. That being said, on a nominal basis, I wouldn’t be against ETH. It has withstood multiple technical challenges and market cycles. It (arguably) has better supply dynamics than Bitcoin today. I agree that any ETH bridged to other Rollups is probably gone forever and “will not come back to accept bids.” Being pessimistic about ETH is not an accusation against Ethereum, but a sobering realization that ETH as an asset is so far dominant, and it is difficult for its network token to continue to maintain a market share of more than 60% among its peers.
When I think about Ethereum vs. Solana, I think about Visa vs. Mastercard, not Google vs. Bing. Even if I give ETH geeks a fair chance, I still have to point to the relevant data metrics and note that ETH is poorly valued compared to BTC.
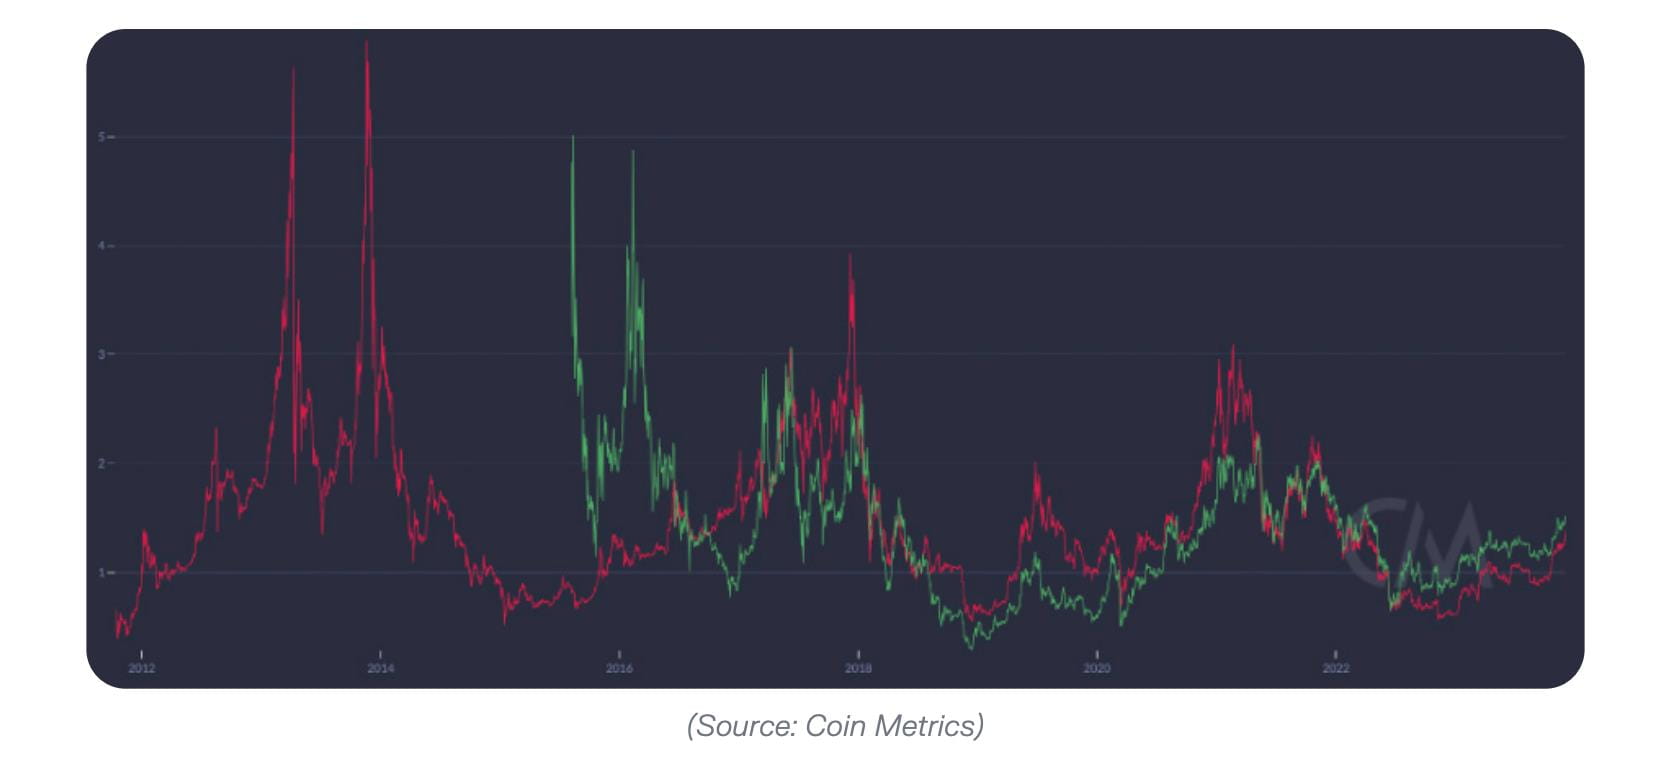
I’ll talk more about the technology later, but I know you’re not sitting around the fireplace coveting my thoughts on sharding. You want a no-brainer bullish/bearish recommendation, and betting on ETH is right in the middle of the bell curve. I’m sure I’ll be arguing with the guys at Bankless soon. (Note: While I hate to bet on it, this firm opinion has weakened since I first drafted this section. With BTC now up ~150% and SOL up over 6x year-to-date, we’ve reached a point where ETH needs some mean reversion as it has been a stablecoin for many months and has lagged significantly.) [Must-read: ETH Q3 Quarterly Report]
1.3 (Liquidity) Area
Bitcoin (BTC), Ethereum (ETH), and dollar-backed stablecoins now account for 75% of the $1.6 trillion overall cryptocurrency market. However, this situation will not remain unchanged.
I founded a company based on the premise that the remaining 25% of the crypto market will grow 100x over the next decade, and investors will need more sophisticated due diligence tools to analyze thousands of crypto assets instead of just two. At current market size, this 100x growth in “the rest” would make liquid crypto capital markets slightly larger than private capital markets ($20-25 trillion) and about 30-35% of global bond and equity capital markets.
More critically: if you agree with me that blockchain is essentially an accounting innovation, then eventually all assets will become "crypto" assets traded on public blockchains, rather than relying on traditional clearing and settlement systems, whether they are "utility tokens" or "equity tokens." Over time, the relationship between cryptocurrencies and traditional finance (TradFi) will become closer and closer, and eventually almost merge into one.
Of course, sticking with market-cap-weighted indices to invest in BTC and ETH also has its advantages.
First, historically, this has proven to be a successful strategy. If you had attended the North American Bitcoin Conference in Miami in 2014 and bought into the products Vitalik was pitching (Ethereum ICO and Bitcoin), you would have enjoyed 75% of the market’s growth over the past decade. These blue-chip assets are now the most solid “hard investments” in the cryptocurrency market because you don’t have to worry about the risk of supply dilution over time.
In contrast, many other top projects have large treasury reserves, which may be gradually sold by insiders over time. Therefore, although their "market value" may increase, the price of their tokens may remain the same or even decrease.
Of course, this is not investment advice. But as a historian, I understand:
A. While BTC and ETH may be the current market leaders, they are not untouchable;
B. Although there are 26,000 stocks traded on the market, only 86 of them have accounted for more than half of the value added in the U.S. market since 1926.
Many of the stock market leaders of the 1920s are no longer around today, and the cryptocurrency market will be no exception. So what are passive index fans like me to do?
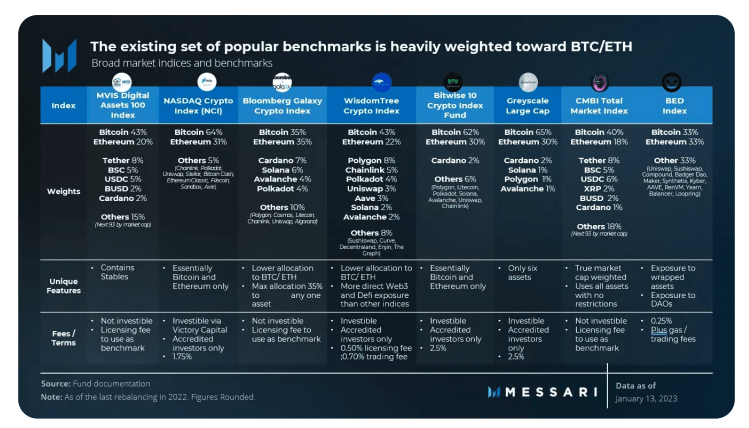
To be honest, there isn’t a lot that can be done right now. Existing alternatives to crypto index products aren’t very appealing, and I doubt that will change in 2024.
A low-fee, automatically rebalancing index would undoubtedly be a great investment vehicle given the oversupply of tokens and market liquidity, but to get index exposure today, your options are either paying exorbitant AUM fees (e.g. 200-250bps for Grayscale’s product), trading fees (actively managed crypto funds), or complex methodologies (there are significant regulatory and technical risks in properly implementing on-chain operations).
For investing in crypto assets ranked 3rd to 1000th, a "cheap" way is to rely on your own investment capabilities. I can give you an example.
A simple index investing strategy to implement at home might be to monitor Kaiko’s liquidity list and rebalance quarterly. If you buy green assets where liquidity ranks higher than market cap rank, and sell red assets where market cap rank higher than liquidity rank, you’ve essentially replicated my year-to-date long/short list of large-cap assets (of course, this is not investment advice).
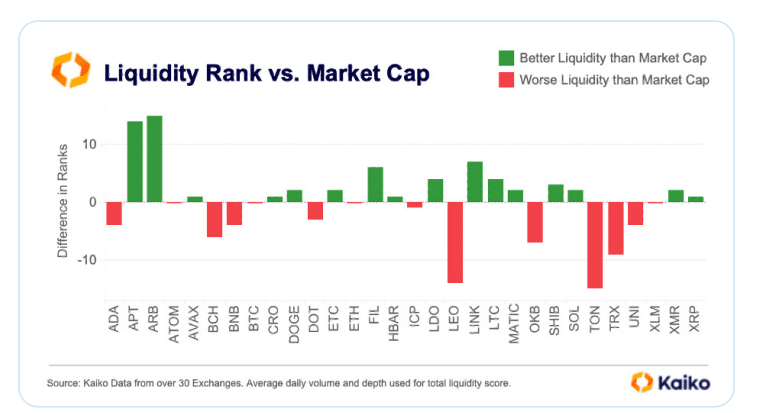
Source: Kaiko
1.4 Is the private cryptocurrency market recovering?
A few years ago, I wrote that crypto fund managers were unhappy because their business model was nothing more than “losing alpha” on behalf of their clients. It turns out I was right.
(I’m not touting myself as such, I’m just convincing myself that I made the right decision to walk away from the most profitable business model in the world, even though I could have continued to do 2% management fee + 20% profit share since 2017 without having to consider the yield of Bitcoin/Ethereum.)
Many crypto investors have not only underperformed, but have exited the market. Some liquidity investors got into trouble because of bad leveraged positions (such as 3AC), bad counterparties (such as Ikigai), or both (we discussed DCG in detail in Chapter 6). You should know all of this, so I won’t repeat last year’s crisis.
So what will happen in 2024? The liquid crypto market is still a jungle full of technical and counterparty risks, high transaction fees, and fierce competition. And adjacent to this jungle is a real "death valley" - the private crypto venture capital market.
The VC market in general has been hit hard by the Fed’s shocking monetary policy over the past few years. Crypto infrastructure has been hit even harder by fraud and widespread regulatory crackdowns. New users and customers are being shut out of exposure to the “long tail” of crypto assets until much-needed legal clarity is achieved, while old ones cut spending to survive the winter as long as possible. This has led to brutal demand destruction: lower service revenues, faster burn rates, further budget cuts, and more.
To make matters worse, AI has become the new darling of the tech world. Once again, we are on the sidelines. (As I explained in Chapter 1.8, I think this is a stupid MEME and a bad choice; AI and cryptocurrencies actually go well together.)
Despite this, I remain optimistic about new crypto Tier 1 investors. The 2023 funds are likely to outperform the S&P in the medium to long term, and many may even outperform the BTC/ETH benchmark with their unusually low entry prices this year. Liquid markets have regained their vitality, and there are some signs of a rebound in the venture market.
Private venture funding (Seed to Series D+) reached its highest level since May, with deals over $500M announced (track them in our funding filter):
Here is a partial list of crypto funds I’ve been watching this year:
Multicoin: I wrote a trilogy about their legendary performance in 2021. However, it is unclear how their LPs will cope with the harsh reality of SOL's 96% plunge in 2022. Even if Multicoin's AUM rebounds sharply again this year, I'm not sure if there are any fund LPs that have experienced a bigger roller coaster.
1confirmation: Nick Tomaino is one of the most honest crypto investors I have come across. He writes candidly about the benchmark issues I mentioned above, the need for better accountability in crypto investing, and his role as one of the few contrarian investors to question the Sams. First SBF, then Altman. He also backs up his arguments with his actions, even sharing his fund's DPI, which is rare in the venture capital market.
There are also some “bottom bullish” investors whose tweets turn out to be correct in hindsight. Framework (Vance) and Placeholder (Burniske) are two examples of people who expressed specific opinions and were not simply perpetual bulls. (Even people who were bullish at the top may prove to be prophets in the long run.)
a16z and Paradigm may be at a disadvantage in terms of valuations for their private portfolios, depending on how much capital they had deployed at the top of the market in 2021, but I wouldn't want to bet against Chris Dixon, Matt Huang and their team. In fact, I'm somewhat thankful that they (may) have mediocre or temporarily losing money in some years. This makes them excellent fighters for their industry in Washington, and their policy teams are doing a great job.
Syncracy Capital has outperformed the crypto market by a wide margin since inception. The team includes three former Messari analysts, including co-founder Ryan Watkins. Full disclosure, I am an LP in this fund and will not be ashamed to promote those who helped build Messari and continue to make money for me after they left. They are one of the few new liquidity funds I know of that has consistently outperformed the BTC/ETH benchmark since inception.
1.5 IPO and M&A
In the world of cryptocurrency, three companies stand out for their positioning, team, and access to capital: Coinbase, Circle, and Galaxy Digital.
Coinbase remains the most important company in the cryptocurrency space. As the most valuable and most strictly regulated cryptocurrency exchange in the United States, Coinbase deserves a separate introduction. Coinbase is unlikely to encounter major competitors in the U.S. market next year, but one of its major partners, Circle, may go public in 2024.
Circle CEO Jeremy Allaire shared on Mainnet that Circle reached $800 million in revenue and $200 million in EBITDA in the first half of 2023 — a figure equivalent to the company’s full-year 2022 numbers — and that revenue could grow further in a “higher and longer” interest rate environment.
Circle could take advantage of developments in U.S. stablecoin policy or a boom in international stablecoin growth and thus be well-positioned in cryptocurrencies. The company's valuation rests almost entirely on the trust the market places in its product and technology growth, rather than its "we earn interest on your float" economics (*Tether is even stronger financially, Tether has regained its market share since the collapse of Silicon Valley Bank in March, but don’t expect its S-1 anytime soon).
I used to think DCG was a good candidate for an IPO due to its diverse portfolio of services. But DCG is under siege and may not go public for a long time. At the very least, DCG will face a difficult challenge to rebuild its institutional reputation after the bankruptcy proceedings of its subsidiary Genesis (a public scandal) and the rapid liquidation of its core assets in the past 12 months (GBTC, CoinDesk divestiture, etc.).
Meanwhile, another New York-based crypto-finance conglomerate is seeing its share price rise (both figuratively and literally). Galaxy Digital’s venture portfolio, trading arm, mining operations, and research arm may help it replace DCG in the crypto industry narrative: Mike Novogratz’s (Galaxy’s CEO) company is already listed on the Toronto Stock Exchange with a market cap of $3 billion.
That’s enough to give Novogratz’s team the option of pursuing an aggressive consolidation strategy in 2024, if they so choose. Some major assets are bound to struggle under continued venture capital pressure, and Novogratz already has a full team of investment banking advisors.
Apart from the above companies, I would not place too much hope on any other cryptocurrency IPOs. I doubt that IPOs of other companies will be allowed before the 2024 US election. Therefore, under the current regulatory regime, the path to liquidity for cryptocurrencies is still achieved through the token market.
1.6 Policy
(Editor's note: This paragraph mainly discusses the possibility of the United States' success in the global encryption market and the challenges it currently faces. The author mentions some important historical events and trends, including the encryption wars in the 1990s, government regulation of digital privacy, and the changes in the United States' position in global competition. It emphasizes that the younger generation's attitudes towards digital privacy and personal freedom may be different from previous generations, which may have an impact on encryption policy. It may contain some ideological content and is a bit boring, so you can skip it)
As for Senator Elizabeth Warren and Chairman Gary Gensler of the Securities and Exchange Commission, we will talk about these outstanding people in the following chapters. Don't worry.
But first, we need to step back and look at the whole situation. The United States has the technical talent, financial markets, and regulatory policies to win the global cryptocurrency market and ensure that the United States is a financial and technological powerhouse in the 21st century, but I don’t think we have enough cypherpunks to save us this time.
The past 30 years have been more than just the formative years for us millennials, they also provide clues and context for what crypto policy we might expect in the short and medium term. Of the most influential events and changes in cryptocurrencies over the past few decades, one historical analogy and two major trends stand out for our attention:
1. The original crypto wars of the 90s included an unfair fight with NSA diehards, legislative proposals to install a literal government chip in all your devices to unlock on demand, and a popular, developer-led grassroots rebellion against government overreach. This is where the term "cypherpunks write code" comes from. You should read this book about the crypto wars, or at least this paper.
It accelerates crypto history. It’s a story of an underdog triumphing over a weak opponent, though it seems unlikely that victory will be repeated in our cryptocurrencies because of profound cultural changes in the United States.
2. Complacency and the awakening mantra: Unfortunately, Generation X (people born between 1964 and 1980) have aged, and have since joined forces with the Baby Boomers to do some pretty horrible and unconstitutional things. Today’s “encryption” poses a major threat to the national order of “surveillance and control.” The problem when we look at our younger protagonists, the Millennials and Generation Z (1995 to 2009), is that they may not care to fight. They are used to the erosion of civil liberties in a post-Patriot Act, post-COVID-19 era. They have never lived with an inward-looking national security apparatus after 20 years of a $7 trillion global military disaster. Many of them even give a shit about Twitter files and the censorship industrial complex of Big Tech. Peter Thiel and David Sacks wrote a predictive article in the early 90s about the dangers of cultural conformity on campuses, and SBF is just a reminder of what we already knew, that such conformity can be performative but is now harmful.
3. The end of American hegemony: When you combine#1and #2, what you really need to understand is that a large portion of the government truly believes that tech policy in the 90s was a mistake, and that the miracle of the open internet, and the economic growth it enabled, has had a net negative impact on American society. Tech has become a scapegoat.
While our concerns about emptying our manufacturing base and over-financialized economy have some validity, it is a bit scary that many people envy China’s closed internet and only see “missed opportunities to curb disinformation.” We are no longer the only superpower, as the bureaucracies of competitors like China seem to be playing in certain areas, and our leaders want more control.
Our culture is weakened, our gerontocracy is paranoid, and this time we have a strong opponent. We have to play a different game and focus on the "Moneyball" election. The good news on this front is: we will win. (More on how this will happen in Chapter 5) (I know you may think these trends are completely unrelated, or at most vaguely related to cryptocurrencies, but that's what they said about Pepe Silvia. We are in a life-or-death information war.)
1.7 Is there anything developers can do?
Despite the two years of a deep cryptocurrency market recession, falling trading volumes, and regulatory headwinds, cryptocurrency developer activity has continued to perform well this year. Mid-year, Alchemy found that the number of smart contracts deployed on the EVM chain grew 300% quarter-on-quarter, while crypto wallet installations hit an all-time high.
Electric Capital found that as of October, monthly active developers contributing to open source projects had fallen sharply year-over-year, but attributed this to a variety of factors: regulatory coolness towards the open source ecosystem following this year’s Ooki DAO ruling; more innovation and development at the application and infrastructure layers; and a more cautious attitude toward competitive threats in a bear market.
a16z’s State of Crypto Market Index is perhaps the best indicator for looking at the overall market health. Its tracker also highlights a 30% drop in the number of open source developers, but it also records some positive data for the market: Developer library downloads hit an all-time high in the third quarter, and active addresses and mobile wallet activity hit all-time lows. Is this the spark that ignites the fire of the 2024 crypto adoption explosion? If I could blindly invest in crypto based on a single chart, it would be this one:
Once AI developers realize that cryptocurrency is another battleground for them, that’s when the market really starts to turn around.
1.8 AI Cryptocurrency
In this digital age marked by an abundance of AIGC, technologies that provide reliable, global, mathematically guaranteed provenance and digital scarcity are essential.
Take deepfakes as an example: Cryptocurrency is extremely important in timestamping and verifying devices and data. Without cryptocurrencies, it is difficult to verify whether certain images or texts are from AI or non-AI, or from Washington or Beijing. In addition, without the fees required by public chains, it will also be a challenge to prevent generative DDOS attacks.
The rise of AI is seen as a "threat" to cryptocurrencies, just as mobile technology was once seen as a threat to the internet, which is patently absurd. Advances in AI will only increase the need for cryptocurrency solutions. While we may debate whether AI is good or bad for humanity (just like we debate whether iPhones are good or bad... but we still know they are clearly beneficial), AI is fantastic for cryptocurrencies.
Personally, I welcome our machine overlords, who have brought forth the perfect machine currency: Bitcoin.
There’s no need to overthink this, but it’s worth noting what Arthur Hayes (founder of BitMEX) wrote on this topic this summer. The two most critical elements for any AI are data and computing power. So it seems reasonable that “AI will trade a currency that maintains its energy purchasing power over time,” which perfectly describes Bitcoin.
Some criticize this view as being too simplistic, especially considering that two potential AI application scenarios - micropayments and smart contract execution - have not yet developed significantly on Bitcoin. Some believe that AI agents will Choose the lowest-cost blockchain, not necessarily Bitcoin, because Bitcoin’s POW mechanism has transaction friction.
Dustin (Messari researcher) believes that the idea of "energy-denominated currency" may be the opposite: AI agents may prefer to purchase Gas tokens (related computing resources) directly.
1.9 DePIN、DeSoc、DeSci
I am perma-bullish on Decentralized Finance (DeFi), but I am not necessarily “overweighting” it because I think other market segments will perform better over the coming year.
I do think some of the top DeFi protocols in the space (particularly in the decentralized exchange space) will see a rebound after a year of flat volumes, but it’s not clear to me that DeFi’s unit economics and product-market fit are strong enough to offset the looming regulatory crackdown.
In addition, the type of assets driving DeFi trading volume is also a question. This year's trading peak was mainly driven by MEME coins, rather than the breakthrough of new applications. Maybe I think too much about the DeFi doomsday scenario in Washington (see Chapter 8 for more).
My eyes have turned to a few key non-financial sectors in crypto. I like DePIN (Physical Infrastructure Networks), DeSoc (Social Media), and DeSci (yes, science!) because they seem less driven by rampant hype and instead revolve around key solutions for our industry that extend far beyond finance.
Sami (Messari researcher) helped popularize the term DePIN last year, and no one is better at mapping the landscape of these hardware networks or articulating how these networks can scale to truly compete with big tech companies.
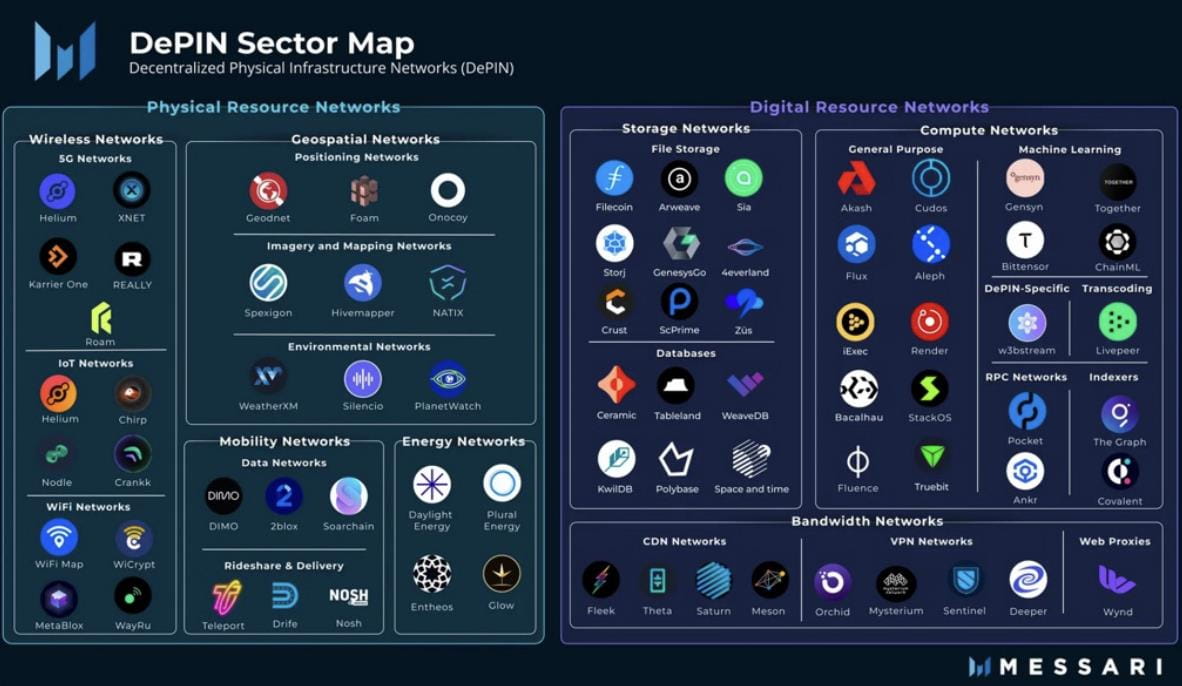
Cloud infrastructure services are a $5 trillion industry in traditional markets, and DePIN accounts for only 0.1% of that. Even assuming 0% of online services use DePIN as their primary stack, the need for decentralized redundancy alone could lead to a surge in demand. A 1% "insurance premium" to eliminate big tech platform risk would result in a 10x increase in DePIN utilization. It doesn't take much to change the status quo, especially with AI-driven demand for GPUs and computing resources.
A similar opportunity exists in social media, where major players generated $230 billion in revenue last year (half of which came from the Meta family of companies), while only a tiny percentage of creators are able to make enough money from content creation.
We’re already seeing this changing (YouTube’s continued growth, Elon’s revenue sharing), and we’re seeing potential breakout DeSoc apps (Farcaster, friend.tech, and Lens) that feel more like the beginning of a barely perceptible J-curve than a false start.
Friend.tech shared $50 million with its creators within a few months of going live, which is a way to attract users. I think the DeSoc of 2024 will follow the "DeFi Summer" craze of 2020.
Finally, there’s Decentralized Science. 50% of the DeSci projects we track were built in the past year. One of the best OG crypto investors I know already spends 100% of his time here.
In this market, the incentives of cryptocurrency make sense: trust in our scientific institutions is probably at an all-time low, and the current system is rife with bureaucratic inefficiencies, broken data methods, and poor incentives (tenure-track jobs require peer-reviewed papers), while cryptocurrency has demonstrated its ability to fund… scientific experiments.
To scale, token sales and DAOs are designed to revolutionize the way we conduct research, and interest in longevity, rare disease treatments, and space exploration is large enough to drive growth in the field.
You can invest directly in DePIN and start using the DeSoc app right now. However, I don’t know of any way to lazily express DeSci’s investment thesis yet. (VitaDAO?)
If you think of it, feel free to DM me.
Original link