



By Jay Jo and Yoon Lee, Tiger Research
Translated by: Aiying
The stability of Japan's stablecoin market is mainly due to the establishment of a clear regulatory framework. Government support and the policies of the ruling Liberal Democratic Party have further accelerated the development of the Web3 industry. Compared with many countries' uncertain or restrictive stance on stablecoins, Japan's positive and open attitude is in stark contrast. As a result, people are full of optimism about the future of Japan's Web3 market. This article will explore the current status of stablecoin regulation in Japan and analyze the potential impact of yen-backed stablecoins.
1. Regulation drives the Japanese stablecoin market to take off
In June 2022, Japan laid the foundation for amending the Payment Services Act (PSA) to establish a regulatory framework for stablecoin issuance and brokerage. These amendments were officially implemented in June 2023, marking the official start of stablecoin issuance. The new law provides a detailed definition of stablecoins, clarifies the issuing entity, and stipulates the licenses required for related businesses.
1. Definition of Stablecoin
Under the revised Payment Services Act, stablecoins are classified as “electronic payment instruments” (EPI) and can be used to pay for goods or services to an unspecified majority of persons.
However, not all stablecoins fall into this category. According to Article 2, Item 5, Paragraph 1 of the revised PSA, only stablecoins whose value is backed by fiat currency can be considered electronic payment instruments. This means that stablecoins based on cryptocurrencies such as Bitcoin or Ethereum, such as MakerDAO’s DAI, are not considered electronic payment instruments. This distinction is an important feature of Japan’s regulatory framework.
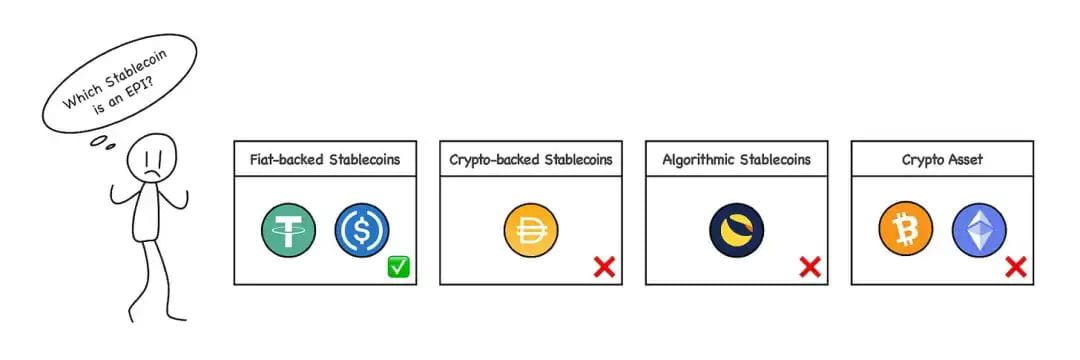
(Source: Tiger Research)
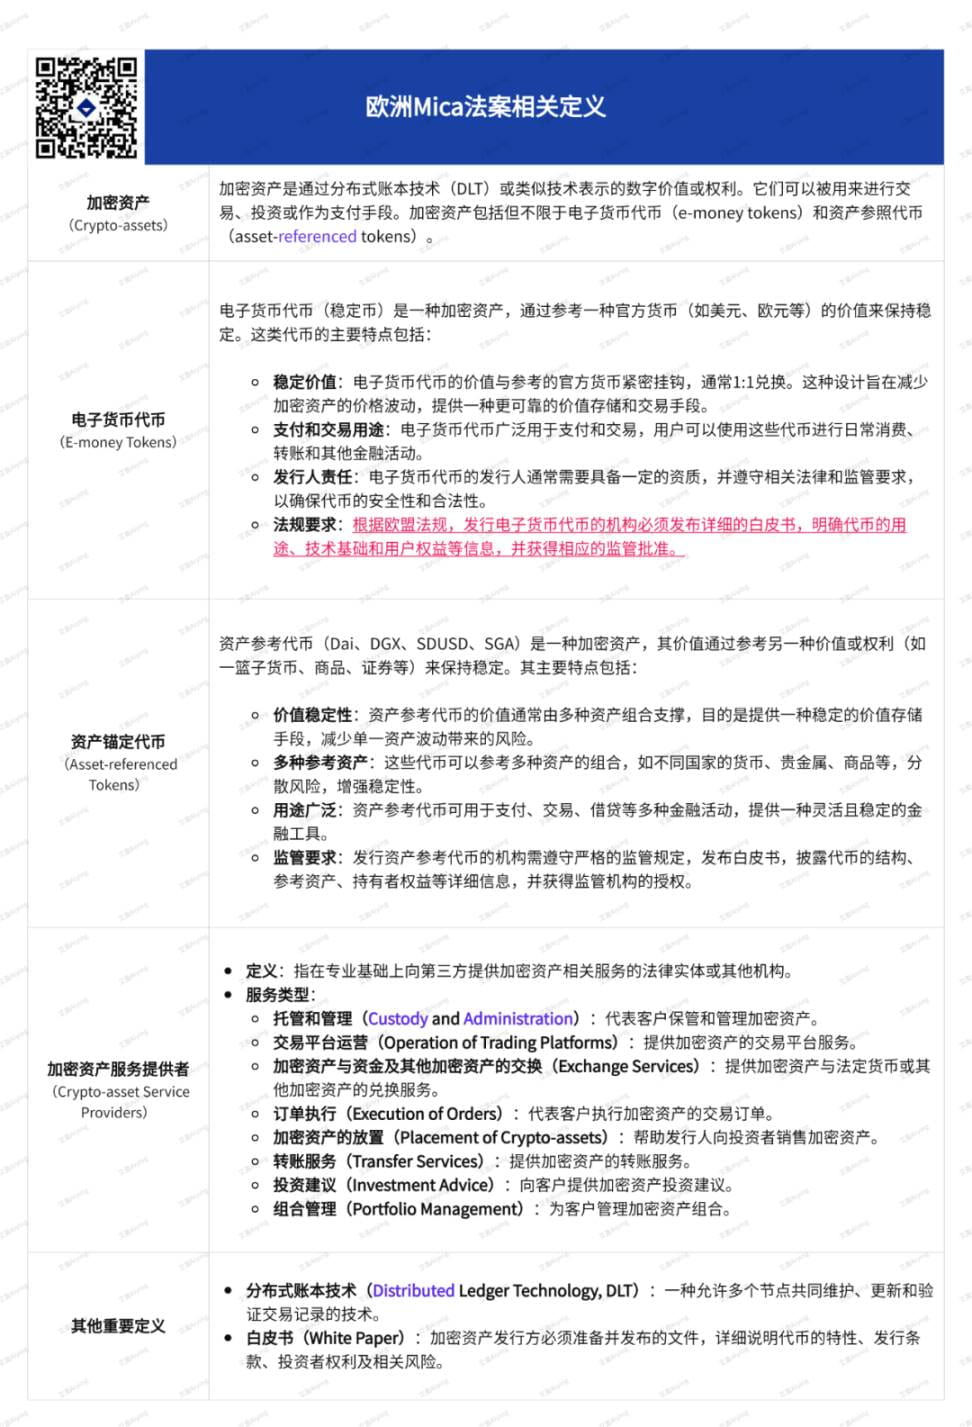
Aiying Aiying added: Japan’s classification of stablecoins is somewhat similar to the European MICA Act. Stablecoins backed by legal tender are classified as “E-money Tokens” in the MICA Act, while asset-anchored stablecoins like DAI are “Asset-referenced Tokens”. For details, please read “10,000-word research report on the European MiCA Act: a comprehensive interpretation of the far-reaching impact on the Web3 industry, DeFi, stablecoins and ICO projects”
2. Stablecoin issuer
Under the revised PSA, stablecoins can only be issued by three types of entities:
bank,
Money transfer service providers
Trust Company
The stablecoins issued by each entity differ in functionality, such as transfer limits and recipient restrictions.
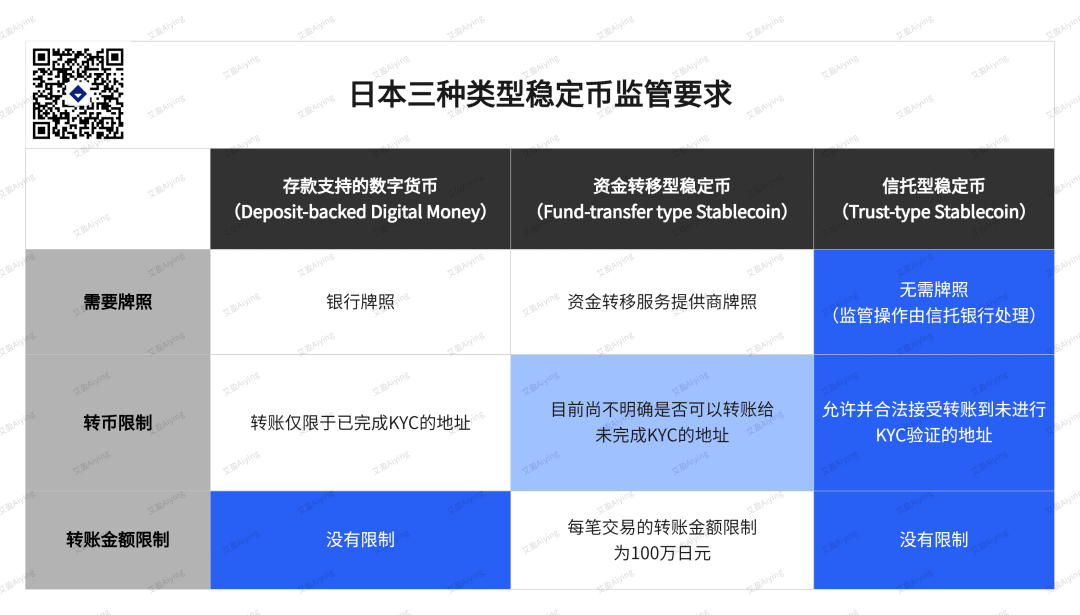
Among them, trust-type stablecoins issued by trust companies are the most worthy of attention, as they are expected to be most in line with Japan's current regulatory environment and are very similar in characteristics to common stablecoins such as USDT and USDC.
Bank-issued stablecoins will be subject to some restrictions. Because banks need to maintain the stability of the financial system, regulators say bank-issued stablecoins need to be carefully considered and may require further legislation.
Fund transfer service providers are also subject to some restrictions, with the transfer amount capped at 1 million yen per transaction, and it is unclear whether transfers can be made without KYC (know your customer) verification. Therefore, this type of stablecoin may require further regulatory updates. Based on these conditions, the most likely form of stablecoin will be a stablecoin issued by a trust company.
3. Stablecoin-related licenses
To conduct stablecoin-related business in Japan, an entity must register as an Electronic Payment Instrument Service Provider (EPISP) and obtain the relevant license. This requirement was introduced after the revision of the Payment Services Act in June 2023. Stablecoin-related business includes activities such as buying, selling, exchanging, brokering or acting as an agent for stablecoins. For example, virtual asset exchanges that support stablecoin transactions or custodial wallet services that manage stablecoins for others need to be registered. In addition, these businesses must also meet user protection and anti-money laundering (AML) compliance requirements.
2. Japanese Yen-backed Stablecoins
As Japan's stablecoin regulatory framework improves, multiple projects are actively researching and testing yen-backed stablecoins. The following will introduce several major Japanese stablecoin projects to help understand the current status and characteristics of the yen stablecoin ecosystem.
1. JPYC: Prepaid payment tool
JPYC is Japan's first issuer of digital assets pegged to the yen, established in January 2021. However, JPYC is currently classified as a prepaid payment instrument rather than an electronic payment instrument as defined in the revised Payment Services Act, and is therefore not considered a stablecoin. The use of JPYC is restricted, for example, it only supports the conversion of fiat currency into JPYC (listed), but cannot convert JPYC back into fiat currency, which is equivalent to a recharge card, which limits its use scenarios to a certain extent.
However, JPYC is actively working to issue a stablecoin that complies with the requirements of the new law, planning to issue a money transfer stablecoin by obtaining a money transfer license and expanding its uses, such as exchanging it with Tochika issued by Hokkoku Bank.
In addition, JPYC also plans to register as an EPISP to operate a stablecoin business. In the long run, the company also plans to issue and operate a trust-type stablecoin based on Progmat Coin to support business activities related to cash or bank deposits.
2 Tochika: Deposit-backed digital currency
Tochituka is Japan's first digital currency backed by bank deposits, launched by Hokkoku Bank in Ishikawa Prefecture in 2024. Tochituka is backed by bank deposits and can be easily accessed by users through the "Tochituka" app and used at partner merchants in Ishikawa Prefecture.
Tochituka is easy to use and has a merchant fee of only 0.5%. However, it is currently limited to use within Ishikawa Prefecture, and there is only one free cash withdrawal opportunity per month. If the number exceeds this, a fee of 110 Tochituka (equivalent to 110 yen) will be charged. In addition, Tochituka runs on a private blockchain and has a limited scope of use.
In the future, Tochika plans to expand its service offering, including linking accounts with other financial institutions, expanding its geographic coverage, and introducing peer-to-peer remittance capabilities.
3 GYEN: Offshore Stablecoin
GYEN is a Japanese yen stablecoin issued by GMO Trust, a New York-based subsidiary of Japan's GMO Internet Group. It is regulated by the New York State Department of Financial Services and is on the state's green list. GYEN is pegged 1:1 to the Japanese yen, but since it is not issued through a Japanese trust company, it cannot be circulated within Japan.
However, GYEN may be included in Japan's regulatory framework in the future and become part of compliant stablecoins.
Is the stablecoin business really feasible?
Although stablecoins have been legally approved for more than a year, Japan’s stablecoin projects have made limited progress. Stablecoin projects like USDT or USDC are still scarce in the Japanese market, and no company has yet completed EPISP registration.
Additionally, stablecoin issuers are required to manage all reserves as demand deposits, which poses significant constraints on business operations. Demand deposits can be withdrawn at any time, and the profit is meager, so it is difficult to bring revenue to the stablecoin business. Although the Bank of Japan recently raised interest rates from 0%, the short-term interest rate of 0.25% remains low, eroding the profitability of the stablecoin business. As a result, market demand for competing stablecoins backed by other assets such as Japanese government bonds has increased.
Despite these challenges, Japan’s large financial institutions and corporate groups are actively involved in the stablecoin business. This includes large banks such as Mitsubishi UFJ Bank (MUFG), Mizuho Bank, and Sumitomo Mitsui Banking Corporation (SMBC), as well as companies such as Sony and DMM Group.
Conclusion
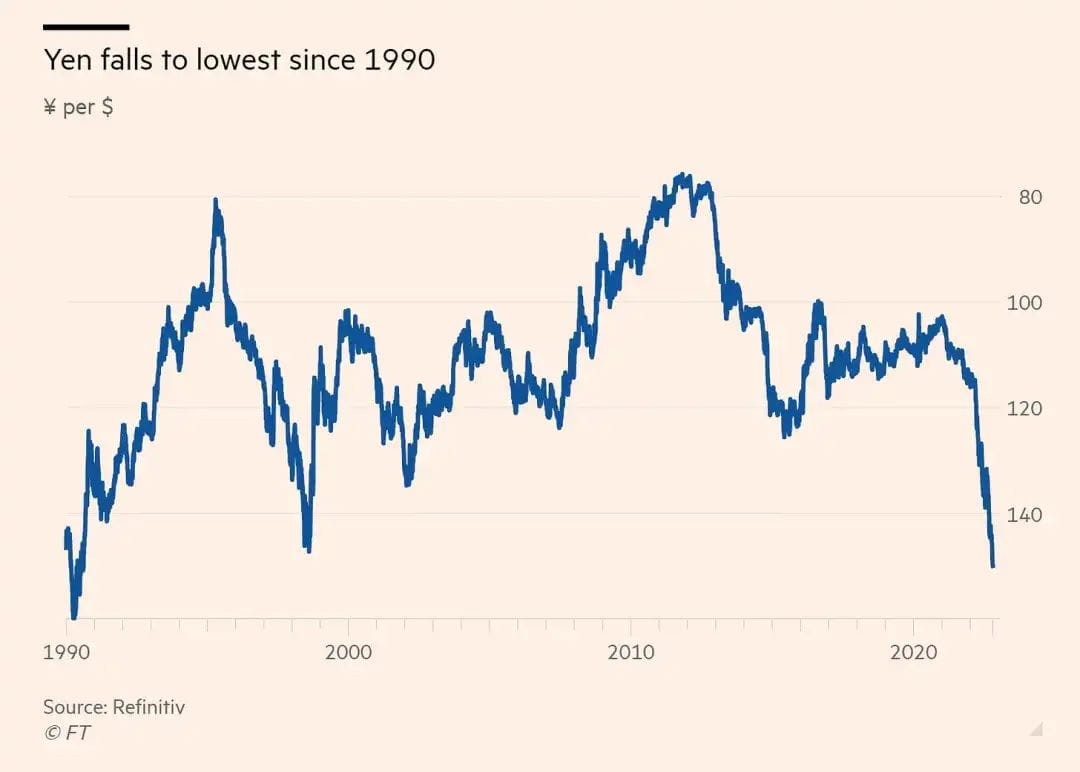
Source: Financial Times, Refinitiv
In recent years, Japan has been struggling to cope with the weakness of the yen and has implemented a variety of strategies to enhance its competitiveness. Stablecoins are part of this as an attempt to enhance the scale and competitiveness of the yen. By adopting advanced stablecoins, Japan is expected to be able to not only apply them domestically, but also open up new application scenarios in the global payment field, which will provide new opportunities for Japan to expand its influence in the international financial market.
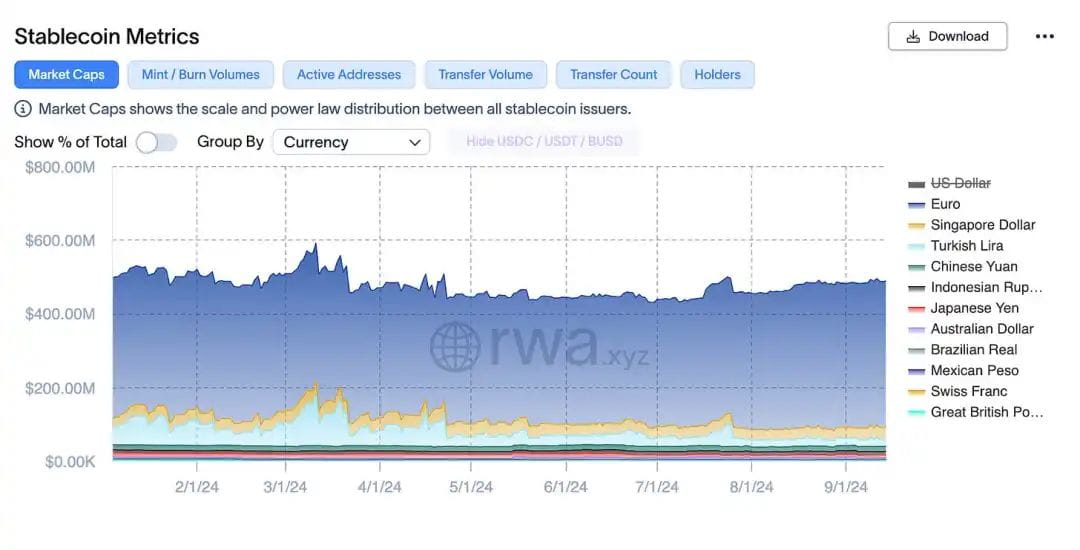
Source: rwa.xyz
Although the regulatory framework for stablecoins has been established for some time, the influence of the yen on the stablecoin market is still limited. There are few actual application cases of stablecoins, and no company has yet completed EPISP registration. The decline in support for the Kishida Cabinet and the Liberal Democratic Party also makes it difficult to promote strong Web3-related policies. Nevertheless, the establishment of a regulatory framework is a meaningful step forward. Although progress may be slow, the changes it will bring are worth looking forward to.