


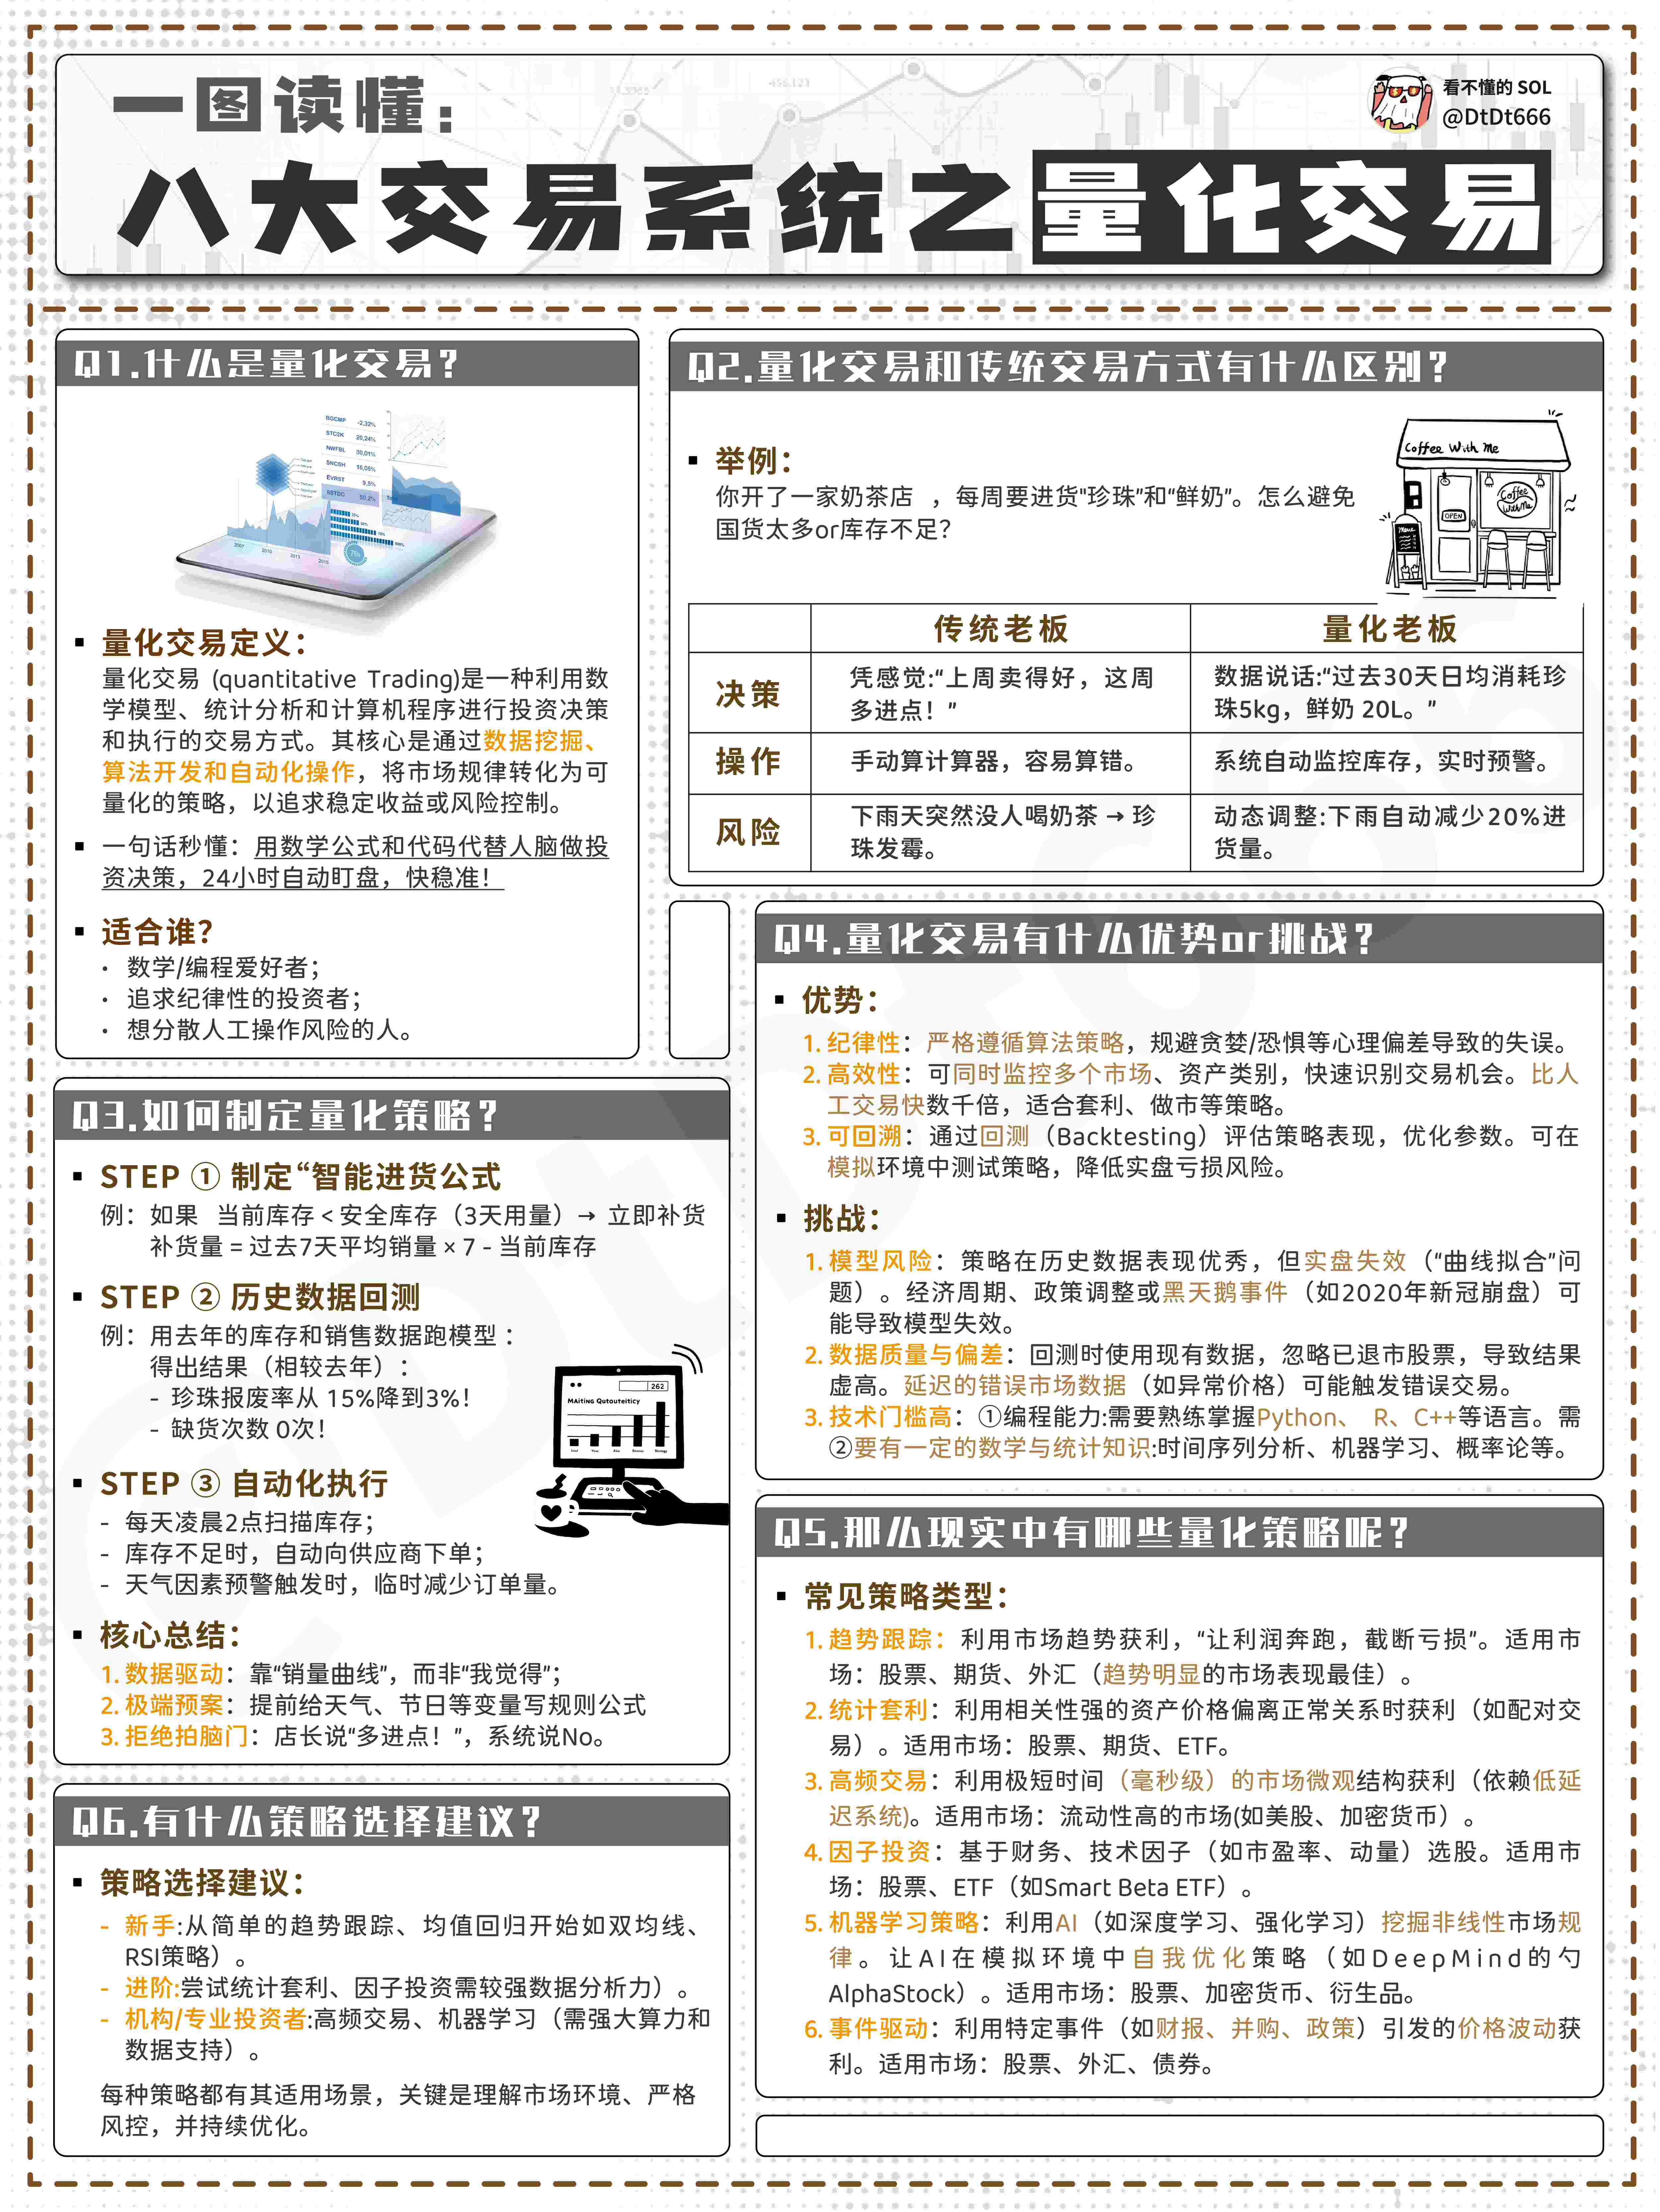
So what is quantitative trading?
Traditional trading: Old fishermen rely on experience to judge where the fish are (watch K-line charts/listen to news)
Quantitative trading: Using sonar to scan the seabed terrain (mathematical models), automatically deploying and retrieving nets (programmatic trading)
Advantages: Include discipline, systematic, real-time, diversification, etc.
Disadvantages: Include sample error and sample bias, strategy resonance, incorrect attribution, black box, etc.
01. Why is quantitative trading necessary?
Traditional investment methods often rely on experience and intuition, but humans can be influenced by emotions such as panic and greed, which makes it unwise to manage assets based solely on personal feelings.
Quantitative trading, on the other hand, analyzes large amounts of data and models to identify market patterns, reducing the interference of subjective factors. It finds investment targets, establishes reusable and repeatedly optimized investment strategies, and guides the investment decision-making process.
In terms of application, quantitative investment covers nearly the entire investment process, including quantitative stock selection, quantitative timing, index futures arbitrage, commodity futures arbitrage, statistical arbitrage, algorithmic trading, asset allocation, risk control, and of course, also includes the cryptocurrency market, among others.
02. Advantages of quantitative trading
Discipline
Traditional investments are often significantly influenced by human emotions such as greed and fear, making it difficult to ensure disciplined execution of trades.
Quantitative models typically execute investment instructions strictly as given, without arbitrary changes due to fluctuations in investor emotions, thus maintaining relatively strict trading discipline.
Systematic
The systematic characteristics of quantitative trading mainly include multi-layered quantitative models, multi-angle observations, and massive data processing.
Multi-layered models mainly include asset allocation models, industry selection models, and stock selection models.
Multi-angle observations primarily involve analyzing multiple aspects such as macro cycles, market structures, corporate valuations, growth potential, profitability quality, and market sentiment.
Massive data processing refers to the ability of quantitative investment to utilize computers to achieve data and information processing capabilities far beyond those of the human brain, thus capturing more investment opportunities.
Real-time
It can quickly track market changes, continuously discover new statistical models that can provide excess returns, and find new trading opportunities. Quantitative trading continuously seeks valuation lows through comprehensive and systematic scanning, capturing opportunities arising from mispricing and misvaluation.
Diversification
The diversification of quantitative trading can also be described as winning by probability.
This is manifested in two aspects:
First, discovering patterns from historical data, where these historical patterns often represent strategies that had a high probability of success in the past.
Second, winning by selecting a combination of stocks/cryptocurrencies rather than relying on a single stock or a few stocks/cryptocurrencies. From the perspective of portfolio investment, it captures stocks/cryptocurrencies with a high probability of success rather than betting on a single stock/cryptocurrency.
03. Disadvantages of quantitative trading
Sample error and sample bias
Many quantitative strategies heavily rely on historical data, but historical data may lack sufficient diversity and long-term accumulation. Therefore, sample sampling may produce errors due to insufficient quantity or bias due to non-random sampling.
The correlation patterns obtained based on this may become invalid once they leave the sample range, losing their reference value.
Strategy resonance
Many quantitative strategies, similar to technical analysis strategies, lose effectiveness as they become more widely used. Once a certain strategy is proven effective, its effectiveness diminishes with the increase in users due to strategy resonance.
Incorrect attribution
In widely applied multi-factor quantitative strategies, the cause is inferred from the results of the data. As long as enough factors are constructed, it is likely to achieve a specific known outcome.
However, when a quantitative strategy built on this multi-factor combination is used for actual trading, it may fail due to incorrect attribution. Because attributing causes from the results makes it challenging to accurately distinguish between random factors and decisive causal factors.
Black box
Various quantitative strategies, including high-frequency, hedging, or arbitrage, often lack inherent causal relationships. Their effectiveness is largely based on strong correlations in historical data. The logic of the strategy is that if there is a 55% or greater probability of being effective based on historical data, then as long as enough data is repeated, the odds will accumulate.
04. How does quantitative trading work?
Collecting data
Collecting historical data of financial products such as stocks, cryptocurrencies, bonds, and futures, including prices, trading volumes, company financial statements, etc.
Developing models
Discovering patterns from the data, such as 'certain cryptocurrencies often rise after 3 PM, trading orders, order volumes, funding rates, etc.'. Transforming these patterns into mathematical models, such as specific formulas or rules.
Backtesting strategies
Testing whether these rules are effective using historical data to see if money could have been made in the past using this method.
Executing trades
Using computer programs to automate trade execution, such as automatically placing orders when certain rules are met.
05. Two approaches to building strategies
One is data mining, discovering stable structures through statistics and induction from a pile of data, commonly used in technical analysis. Since price data is randomly fluctuating, it is unlikely to have a consistently stable structure, requiring continuous iteration and optimization. However, with fewer new data generated in the future, it becomes difficult to find new stable structures in a small amount of data. Therefore, once the statistical patterns in historical data become invalid, the strategy essentially loses its value.
The development path of this strategy involves having data first, then mining for patterns, and continuously optimizing and iterating.
The second is logical reasoning, deriving a conclusion through mathematical deduction. For example, the theory of arbitrage pricing leads to an arbitrage boundary; as long as the price exceeds this boundary, there is an arbitrage opportunity. Regardless of how the price changes, as long as it exceeds the arbitrage boundary, there is an arbitrage opportunity.
The development path of this strategy involves deducing patterns through logic first, then selecting underlying conditions, such as changes in interest rates or storage costs, leading to different calculation results and waiting for price-triggered trading opportunities.
Tomorrow I will release a video to see how top traders on Wall Street use quantitative arbitrage to earn hundreds of billions!