
#vertiv
vertiv
545 views
9 Discussing
Hot
Latest

·
--
Partly True
$VRT Data center cooling and power giants surge! Tokenized stock VRT jumps 10% to $235!
Vertiv, a data center power and cooling giant, saw its tokenized stock (VRT) rise 10.21% today to $235.63!
Market drivers: No new earnings reports were released today. As a leader in AI data center infrastructure, its price action is entirely tracking broader sentiment across global AI computing, optical modules, and liquid cooling.
Conclusion: Perpetual contracts for traditional financial stocks are 100% tied to the order book of the underlying U.S. stock. Do not trade them independently of traditional stock markets.
#VRT #Vertiv #数据中心
$VRT
{future}(VRTUSDT)
$VRT Data center cooling and power giants surge! Tokenized stock VRT jumps 10% to $235!
Vertiv, a data center power and cooling giant, saw its tokenized stock (VRT) rise 10.21% today to $235.63!
Market drivers: No new earnings reports were released today. As a leader in AI data center infrastructure, its price action is entirely tracking broader sentiment across global AI computing, optical modules, and liquid cooling.
Conclusion: Perpetual contracts for traditional financial stocks are 100% tied to the order book of the underlying U.S. stock. Do not trade them independently of traditional stock markets.
#VRT #Vertiv #数据中心
$VRT
Vertiv, a data center power and cooling giant, saw its tokenized stock (VRT) rise 10.21% today to $235.63!
Market drivers: No new earnings reports were released today. As a leader in AI data center infrastructure, its price action is entirely tracking broader sentiment across global AI computing, optical modules, and liquid cooling.
Conclusion: Perpetual contracts for traditional financial stocks are 100% tied to the order book of the underlying U.S. stock. Do not trade them independently of traditional stock markets.
#VRT #Vertiv #数据中心
$VRT
1
2
239

·
--
Another AI pick-and-shovel play just delivered a blockbuster report: Vertiv (NYSE: VRT) Q3 revenue rose 61% year over year, while orders doubled.
The earnings report was released before the market opened on 10-28 Eastern Time. Key figures (sources: Vertiv official IR / PR Newswire):
1️⃣ Q3 revenue was $4.313 billion, up 61% year over year, including 55% organic growth
2️⃣ Organic orders rose more than 100% year over year; Americas revenue was up 75%
3️⃣ Adjusted EPS was $2.21, up 78% year over year; adjusted operating margin was 25.2%, up 290 bp
4️⃣ Full-year revenue guidance was raised to $14.45–14.85 billion, with the midpoint up $650 million; full-year adjusted EPS guidance is $7.10–7.20
The CEO said: “We are in the middle of the largest infrastructure buildout and it's accelerating.” According to Yahoo Finance / Investing.com, the stock rose more than 15% in premarket trading.
My take: GPUs are the engines of AI, but data center infrastructure—power, cooling, and racks—is what keeps those engines from burning out. Orders doubling says more than revenue: it signals demand over the next several quarters, not a one-off number.
AI capex is still accelerating, and the engine of technological civilization that is the U.S. stock market keeps running. Stop constantly thinking about shorting the Nasdaq—the bears weren’t even given a chance to buy the dip.
Risk warning: One quarter of strong growth doesn’t mean growth will stay strong forever; premarket gains could be given back, and the valuation is already far from cheap. This is for informational purposes only and does not constitute investment advice.
#Vertiv #AI #美股 #DataCenter
Another AI pick-and-shovel play just delivered a blockbuster report: Vertiv (NYSE: VRT) Q3 revenue rose 61% year over year, while orders doubled.
The earnings report was released before the market opened on 10-28 Eastern Time. Key figures (sources: Vertiv official IR / PR Newswire):
1️⃣ Q3 revenue was $4.313 billion, up 61% year over year, including 55% organic growth
2️⃣ Organic orders rose more than 100% year over year; Americas revenue was up 75%
3️⃣ Adjusted EPS was $2.21, up 78% year over year; adjusted operating margin was 25.2%, up 290 bp
4️⃣ Full-year revenue guidance was raised to $14.45–14.85 billion, with the midpoint up $650 million; full-year adjusted EPS guidance is $7.10–7.20
The CEO said: “We are in the middle of the largest infrastructure buildout and it's accelerating.” According to Yahoo Finance / Investing.com, the stock rose more than 15% in premarket trading.
My take: GPUs are the engines of AI, but data center infrastructure—power, cooling, and racks—is what keeps those engines from burning out. Orders doubling says more than revenue: it signals demand over the next several quarters, not a one-off number.
AI capex is still accelerating, and the engine of technological civilization that is the U.S. stock market keeps running. Stop constantly thinking about shorting the Nasdaq—the bears weren’t even given a chance to buy the dip.
Risk warning: One quarter of strong growth doesn’t mean growth will stay strong forever; premarket gains could be given back, and the valuation is already far from cheap. This is for informational purposes only and does not constitute investment advice.
#Vertiv #AI #美股 #DataCenter
The earnings report was released before the market opened on 10-28 Eastern Time. Key figures (sources: Vertiv official IR / PR Newswire):
1️⃣ Q3 revenue was $4.313 billion, up 61% year over year, including 55% organic growth
2️⃣ Organic orders rose more than 100% year over year; Americas revenue was up 75%
3️⃣ Adjusted EPS was $2.21, up 78% year over year; adjusted operating margin was 25.2%, up 290 bp
4️⃣ Full-year revenue guidance was raised to $14.45–14.85 billion, with the midpoint up $650 million; full-year adjusted EPS guidance is $7.10–7.20
The CEO said: “We are in the middle of the largest infrastructure buildout and it's accelerating.” According to Yahoo Finance / Investing.com, the stock rose more than 15% in premarket trading.
My take: GPUs are the engines of AI, but data center infrastructure—power, cooling, and racks—is what keeps those engines from burning out. Orders doubling says more than revenue: it signals demand over the next several quarters, not a one-off number.
AI capex is still accelerating, and the engine of technological civilization that is the U.S. stock market keeps running. Stop constantly thinking about shorting the Nasdaq—the bears weren’t even given a chance to buy the dip.
Risk warning: One quarter of strong growth doesn’t mean growth will stay strong forever; premarket gains could be given back, and the valuation is already far from cheap. This is for informational purposes only and does not constitute investment advice.
#Vertiv #AI #美股 #DataCenter
88
The AI bubble debate had barely been raging for two days when the pick-and-shovel sellers clapped back with their earnings: Vertiv brought in $4.31 billion in third-quarter revenue, up 61% year over year, and earned $2.21 per share—well above the $1.82 expected. Orders more than doubled, and the stock jumped 16% premarket. The CEO’s exact words: “This infrastructure buildout is still accelerating.” The irony? The people calling it an AI bubble don’t own any shovels, while the shovel sellers are raking in cash. Pick a side: A) If shovel stocks are rising, AI hasn’t cooled off yet; B) Selling the picks and shovels doesn’t mean the miners will make money.
$BTC $ETH $SOL #Vertiv #AI #Earnings
The AI bubble debate had barely been raging for two days when the pick-and-shovel sellers clapped back with their earnings: Vertiv brought in $4.31 billion in third-quarter revenue, up 61% year over year, and earned $2.21 per share—well above the $1.82 expected. Orders more than doubled, and the stock jumped 16% premarket. The CEO’s exact words: “This infrastructure buildout is still accelerating.” The irony? The people calling it an AI bubble don’t own any shovels, while the shovel sellers are raking in cash. Pick a side: A) If shovel stocks are rising, AI hasn’t cooled off yet; B) Selling the picks and shovels doesn’t mean the miners will make money.
$BTC $ETH $SOL #Vertiv #AI #Earnings
$BTC $ETH $SOL #Vertiv #AI #Earnings
25
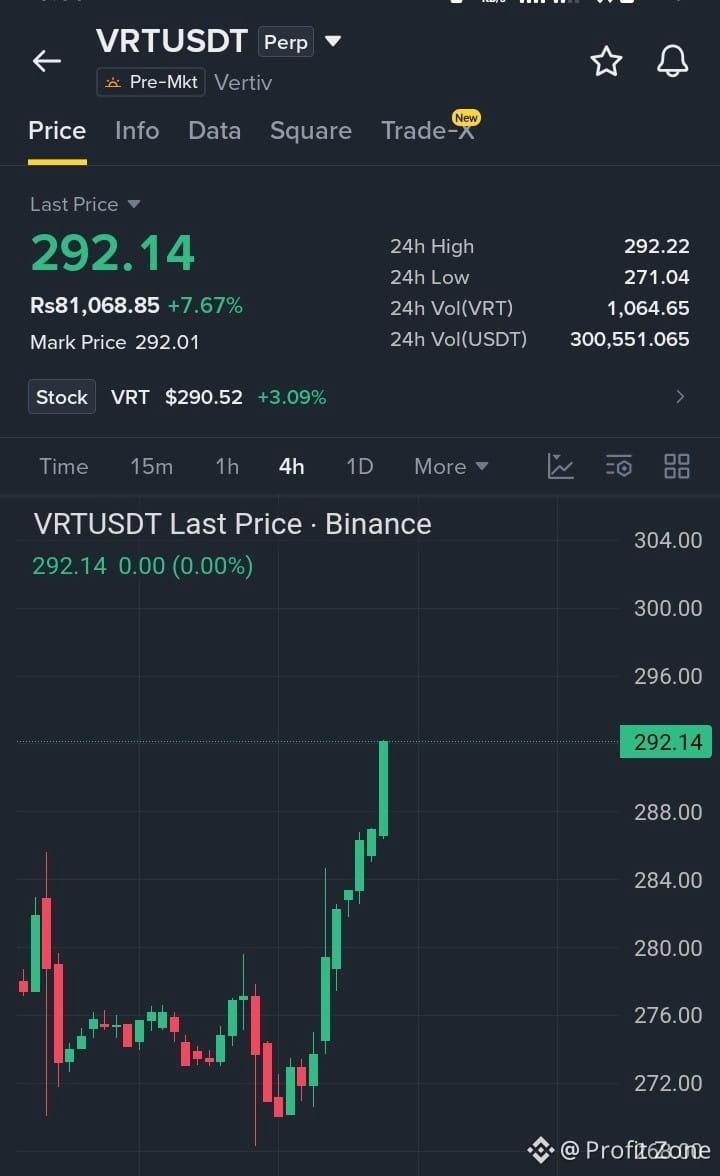
·
--
See translation
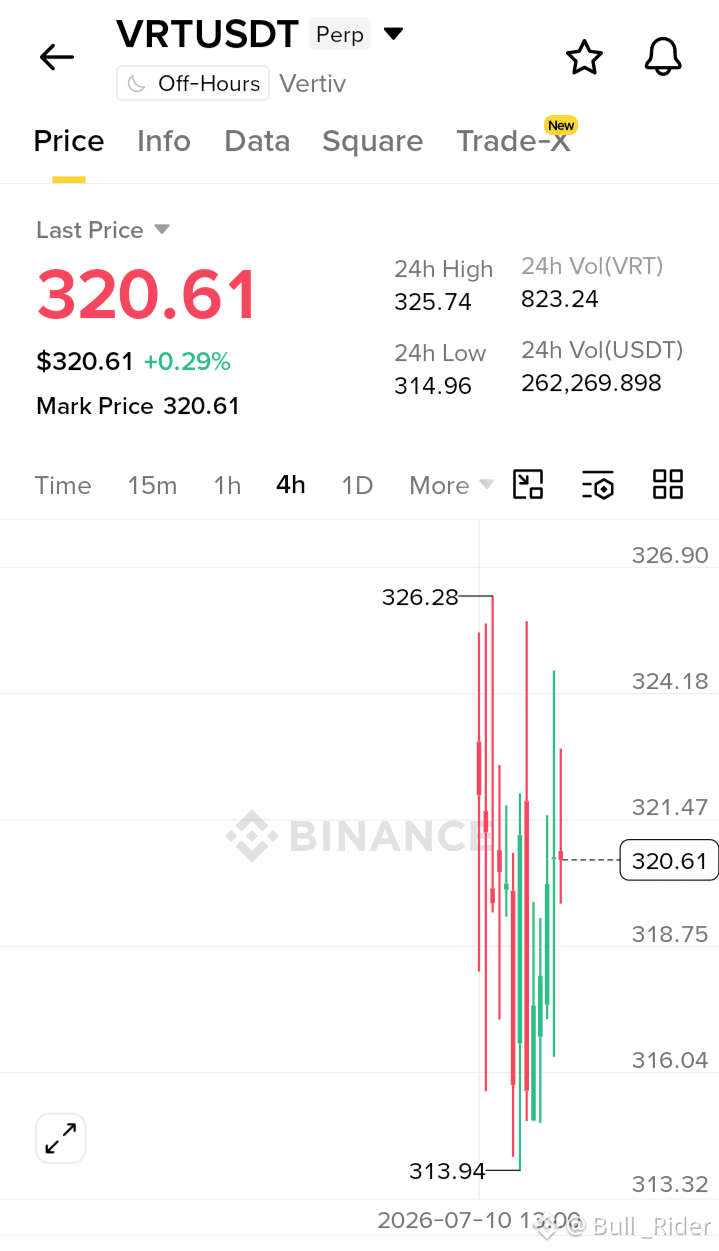
$VRT is showing steady momentum after holding above key support, with buyers defending the recent pullback. Price action around the current range suggests growing interest, and a successful move above nearby resistance could open the door for another bullish leg. Traders will be watching volume and confirmation before the next breakout attempt.
🎯 Target 1: $325.70
🎯 Target 2: $332.00
🎯 Target 3: $340.00
#VRT #VRTUSDT #Vertiv
$VRT is showing steady momentum after holding above key support, with buyers defending the recent pullback. Price action around the current range suggests growing interest, and a successful move above nearby resistance could open the door for another bullish leg. Traders will be watching volume and confirmation before the next breakout attempt.
🎯 Target 1: $325.70
🎯 Target 2: $332.00
🎯 Target 3: $340.00
#VRT #VRTUSDT #Vertiv
🎯 Target 1: $325.70
🎯 Target 2: $332.00
🎯 Target 3: $340.00
#VRT #VRTUSDT #Vertiv
1
139
·
--
Bullish
See translation
$VRTon
{alpha}(560x9cea8a7be1ab0320b709d368ad60d8500f55995f)
Vertiv is quietly climbing (+0.57%, $248.81). It's the "picks and shovels" play behind every AI data center. The cooling gear has to come from somewhere. 🔥
📊 Overview: Steady strength, and the buyers look patient.
🛡 Support: $240 / $228
🚧 Resistance: $258 / $270
⏱ Short term: A break above $258 could open a fast move.
📅 Long term: Data center buildouts are a multi-year trend.
🎯 Targets: T1 $258 | T2 $270 | T3 $290
💡 Pro tip: Slow, steady climbers reward patience. Trail your stop up as price moves.
#VRTon #Vertiv #AIInfrastructure
$VRTon
Vertiv is quietly climbing (+0.57%, $248.81). It's the "picks and shovels" play behind every AI data center. The cooling gear has to come from somewhere. 🔥
📊 Overview: Steady strength, and the buyers look patient.
🛡 Support: $240 / $228
🚧 Resistance: $258 / $270
⏱ Short term: A break above $258 could open a fast move.
📅 Long term: Data center buildouts are a multi-year trend.
🎯 Targets: T1 $258 | T2 $270 | T3 $290
💡 Pro tip: Slow, steady climbers reward patience. Trail your stop up as price moves.
#VRTon #Vertiv #AIInfrastructure
Vertiv is quietly climbing (+0.57%, $248.81). It's the "picks and shovels" play behind every AI data center. The cooling gear has to come from somewhere. 🔥
📊 Overview: Steady strength, and the buyers look patient.
🛡 Support: $240 / $228
🚧 Resistance: $258 / $270
⏱ Short term: A break above $258 could open a fast move.
📅 Long term: Data center buildouts are a multi-year trend.
🎯 Targets: T1 $258 | T2 $270 | T3 $290
💡 Pro tip: Slow, steady climbers reward patience. Trail your stop up as price moves.
#VRTon #Vertiv #AIInfrastructure
158
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
1
#NvidiaBoardNotConsideringHuang’sReturnasCEO
0 views
0 Discussing
2
#A Packed Week of Earnings and Data Tests Markets
63,729 views
399 Discussing
3
#AnthropicIPOTestsInvestorAppetiteForAI
119,774 views
1,380 Discussing
4
#BitcoinExtendsLosingStreakToSixWeeks
93,836 views
742 Discussing
5
#XRPFallsTo$0.89LowestSinceNovember2024
14,843 views
74 Discussing
6
#SP500AndNasdaqFuturesHitQuarterlyLows
27,001 views
245 Discussing
7
#CaliforniaVotersBackProp42BarringNewCryptoTaxes
18,811 views
228 Discussing
8
#HKPlansDigitalAssetRegulatoryBillByYearEnd
17,225 views
166 Discussing
9
#MUFGSMFGMizuhoPlanYenBackedStablecoin
33,087 views
298 Discussing
10
#HKMAAndSwiftExploreTokenizedDepositInteroperability
2,654 views
19 Discussing