
#consumer
consumer
900 views
8 Discussing
Hot
Latest

·
--
Article
See translation
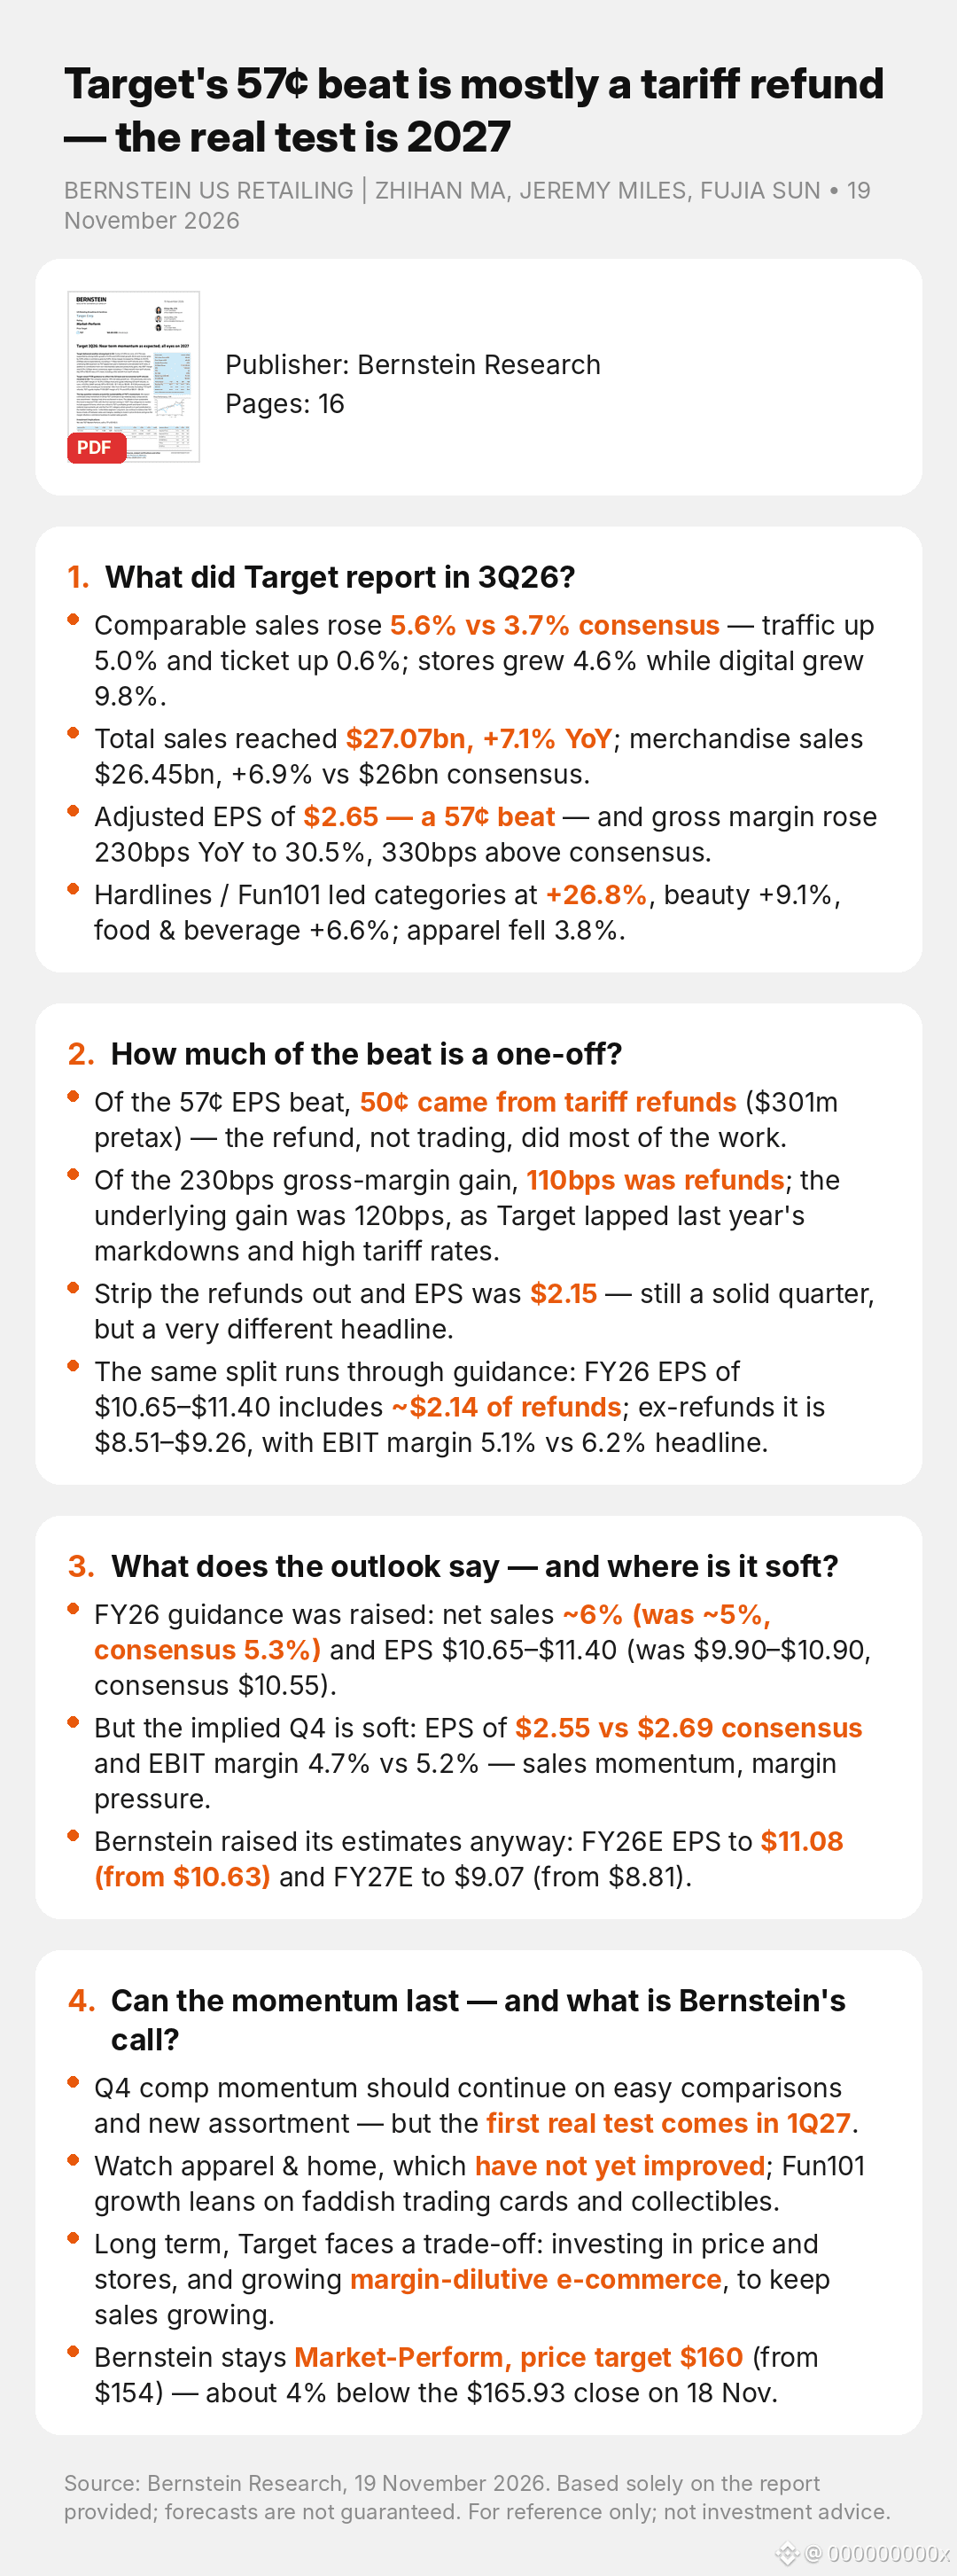
Target's 57¢ beat is mostly a tariff refund — the real test is 2027Target's 57¢ beat is mostly a tariff refund — the real test is 2027
$TGT
BERNSTEIN US RETAILING | ZHIHAN MA, JEREMY MILES, FUJIA SUN • 19 November 2026
1. What did Target report in 3Q26?
• Comparable sales rose 5.6% vs 3.7% consensus — traffic up 5.0% and ticket up 0.6%; stores grew 4.6% while digital grew 9.8%.
• Total sales reached $27.07bn, +7.1% YoY; merchandise sales $26.45bn, +6.9% vs $26bn consensus.
• Adjusted EPS of $2.65 — a 57¢ beat — and gross margin rose 230bps YoY to 30.5%, 330bps above consensus.
• Hardlines / Fun101 led categories at +26.8%, beauty +9.1%, food & beverage +6.6%; apparel fell 3.8%.
2. How much of the beat is a one-off?
• Of the 57¢ EPS beat, 50¢ came from tariff refunds ($301m pretax) — the refund, not trading, did most of the work.
• Of the 230bps gross-margin gain, 110bps was refunds; the underlying gain was 120bps, as Target lapped last year's markdowns and high tariff rates.
• Strip the refunds out and EPS was $2.15 — still a solid quarter, but a very different headline.
• The same split runs through guidance: FY26 EPS of $10.65–$11.40 includes ~$2.14 of refunds; ex-refunds it is $8.51–$9.26, with EBIT margin 5.1% vs 6.2% headline.
3. What does the outlook say — and where is it soft?
• FY26 guidance was raised: net sales ~6% (was ~5%, consensus 5.3%) and EPS $10.65–$11.40 (was $9.90–$10.90, consensus $10.55).
• But the implied Q4 is soft: EPS of $2.55 vs $2.69 consensus and EBIT margin 4.7% vs 5.2% — sales momentum, margin pressure.
• Bernstein raised its estimates anyway: FY26E EPS to $11.08 (from $10.63) and FY27E to $9.07 (from $8.81).
4. Can the momentum last — and what is Bernstein's call?
• Q4 comp momentum should continue on easy comparisons and new assortment — but the first real test comes in 1Q27.
• Watch apparel & home, which have not yet improved; Fun101 growth leans on faddish trading cards and collectibles.
• Long term, Target faces a trade-off: investing in price and stores, and growing margin-dilutive e-commerce, to keep sales growing.
• Bernstein stays Market-Perform, price target $160 (from $154) — about 4% below the $165.93 close on 18 Nov.
Since the report: shares rose 4% on 18 Nov to $165.93; $167.46 on 19 Nov; $165.83 at the 20 Nov close (Finnhub).
#Target #Retail #Earnings #Consumer #Tariffs
Source: Bernstein Research, 19 November 2026. Research summary for reference only; forecasts are not guaranteed. Not investment advice.
Target's 57¢ beat is mostly a tariff refund — the real test is 2027
Target's 57¢ beat is mostly a tariff refund — the real test is 2027
$TGT
BERNSTEIN US RETAILING | ZHIHAN MA, JEREMY MILES, FUJIA SUN • 19 November 2026
1. What did Target report in 3Q26?
• Comparable sales rose 5.6% vs 3.7% consensus — traffic up 5.0% and ticket up 0.6%; stores grew 4.6% while digital grew 9.8%.
• Total sales reached $27.07bn, +7.1% YoY; merchandise sales $26.45bn, +6.9% vs $26bn consensus.
• Adjusted EPS of $2.65 — a 57¢ beat — and gross margin rose 230bps YoY to 30.5%, 330bps above consensus.
• Hardlines / Fun101 led categories at +26.8%, beauty +9.1%, food & beverage +6.6%; apparel fell 3.8%.
2. How much of the beat is a one-off?
• Of the 57¢ EPS beat, 50¢ came from tariff refunds ($301m pretax) — the refund, not trading, did most of the work.
• Of the 230bps gross-margin gain, 110bps was refunds; the underlying gain was 120bps, as Target lapped last year's markdowns and high tariff rates.
• Strip the refunds out and EPS was $2.15 — still a solid quarter, but a very different headline.
• The same split runs through guidance: FY26 EPS of $10.65–$11.40 includes ~$2.14 of refunds; ex-refunds it is $8.51–$9.26, with EBIT margin 5.1% vs 6.2% headline.
3. What does the outlook say — and where is it soft?
• FY26 guidance was raised: net sales ~6% (was ~5%, consensus 5.3%) and EPS $10.65–$11.40 (was $9.90–$10.90, consensus $10.55).
• But the implied Q4 is soft: EPS of $2.55 vs $2.69 consensus and EBIT margin 4.7% vs 5.2% — sales momentum, margin pressure.
• Bernstein raised its estimates anyway: FY26E EPS to $11.08 (from $10.63) and FY27E to $9.07 (from $8.81).
4. Can the momentum last — and what is Bernstein's call?
• Q4 comp momentum should continue on easy comparisons and new assortment — but the first real test comes in 1Q27.
• Watch apparel & home, which have not yet improved; Fun101 growth leans on faddish trading cards and collectibles.
• Long term, Target faces a trade-off: investing in price and stores, and growing margin-dilutive e-commerce, to keep sales growing.
• Bernstein stays Market-Perform, price target $160 (from $154) — about 4% below the $165.93 close on 18 Nov.
Since the report: shares rose 4% on 18 Nov to $165.93; $167.46 on 19 Nov; $165.83 at the 20 Nov close (Finnhub).
#Target #Retail #Earnings #Consumer #Tariffs
Source: Bernstein Research, 19 November 2026. Research summary for reference only; forecasts are not guaranteed. Not investment advice.
$TGT
BERNSTEIN US RETAILING | ZHIHAN MA, JEREMY MILES, FUJIA SUN • 19 November 2026
1. What did Target report in 3Q26?
• Comparable sales rose 5.6% vs 3.7% consensus — traffic up 5.0% and ticket up 0.6%; stores grew 4.6% while digital grew 9.8%.
• Total sales reached $27.07bn, +7.1% YoY; merchandise sales $26.45bn, +6.9% vs $26bn consensus.
• Adjusted EPS of $2.65 — a 57¢ beat — and gross margin rose 230bps YoY to 30.5%, 330bps above consensus.
• Hardlines / Fun101 led categories at +26.8%, beauty +9.1%, food & beverage +6.6%; apparel fell 3.8%.
2. How much of the beat is a one-off?
• Of the 57¢ EPS beat, 50¢ came from tariff refunds ($301m pretax) — the refund, not trading, did most of the work.
• Of the 230bps gross-margin gain, 110bps was refunds; the underlying gain was 120bps, as Target lapped last year's markdowns and high tariff rates.
• Strip the refunds out and EPS was $2.15 — still a solid quarter, but a very different headline.
• The same split runs through guidance: FY26 EPS of $10.65–$11.40 includes ~$2.14 of refunds; ex-refunds it is $8.51–$9.26, with EBIT margin 5.1% vs 6.2% headline.
3. What does the outlook say — and where is it soft?
• FY26 guidance was raised: net sales ~6% (was ~5%, consensus 5.3%) and EPS $10.65–$11.40 (was $9.90–$10.90, consensus $10.55).
• But the implied Q4 is soft: EPS of $2.55 vs $2.69 consensus and EBIT margin 4.7% vs 5.2% — sales momentum, margin pressure.
• Bernstein raised its estimates anyway: FY26E EPS to $11.08 (from $10.63) and FY27E to $9.07 (from $8.81).
4. Can the momentum last — and what is Bernstein's call?
• Q4 comp momentum should continue on easy comparisons and new assortment — but the first real test comes in 1Q27.
• Watch apparel & home, which have not yet improved; Fun101 growth leans on faddish trading cards and collectibles.
• Long term, Target faces a trade-off: investing in price and stores, and growing margin-dilutive e-commerce, to keep sales growing.
• Bernstein stays Market-Perform, price target $160 (from $154) — about 4% below the $165.93 close on 18 Nov.
Since the report: shares rose 4% on 18 Nov to $165.93; $167.46 on 19 Nov; $165.83 at the 20 Nov close (Finnhub).
#Target #Retail #Earnings #Consumer #Tariffs
Source: Bernstein Research, 19 November 2026. Research summary for reference only; forecasts are not guaranteed. Not investment advice.
30
See translation
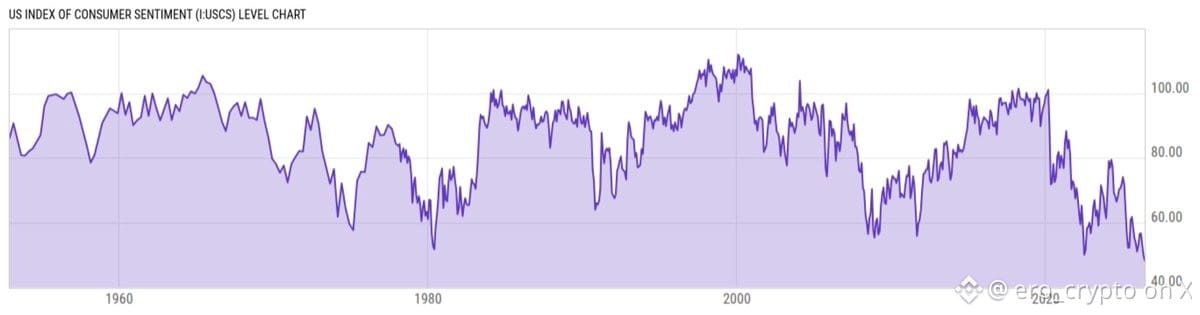
Live updates: Bitcoin ($BTC) in tight range near $84,000; consumer confidence plunged this month.
12 minutes ago · 11:17 a.m. EDT Stephen Alpher Share Share this post Copy link X (Twitter) LinkedIn Facebook Email Bitcoin gives up gains as yields turn higher again A sizable decline in bond yields overnight helped bitcoin BTC $84,117.13 to early gains on Tuesday, but that’s reversed in late-morning U.S. trade.
Down as low as 5.20% at one point, the 10-year U.S. Treasury yield is now higher by 3 basis points to 5.27%, the strongest level since the first half of 2007.
#MarketNews #Investing #Bitcoin #Confidence #Consumer
Live updates: Bitcoin ($BTC ) in tight range near $84,000; consumer confidence plunged this month.
12 minutes ago · 11:17 a.m. EDT Stephen Alpher Share Share this post Copy link X (Twitter) LinkedIn Facebook Email Bitcoin gives up gains as yields turn higher again A sizable decline in bond yields overnight helped bitcoin BTC $84,117.13 to early gains on Tuesday, but that’s reversed in late-morning U.S. trade.
Down as low as 5.20% at one point, the 10-year U.S. Treasury yield is now higher by 3 basis points to 5.27%, the strongest level since the first half of 2007.
#MarketNews #Investing #Bitcoin #Confidence #Consumer
12 minutes ago · 11:17 a.m. EDT Stephen Alpher Share Share this post Copy link X (Twitter) LinkedIn Facebook Email Bitcoin gives up gains as yields turn higher again A sizable decline in bond yields overnight helped bitcoin BTC $84,117.13 to early gains on Tuesday, but that’s reversed in late-morning U.S. trade.
Down as low as 5.20% at one point, the 10-year U.S. Treasury yield is now higher by 3 basis points to 5.27%, the strongest level since the first half of 2007.
#MarketNews #Investing #Bitcoin #Confidence #Consumer
BTC-5.76%
IEFETF+0.67%
104
See translation
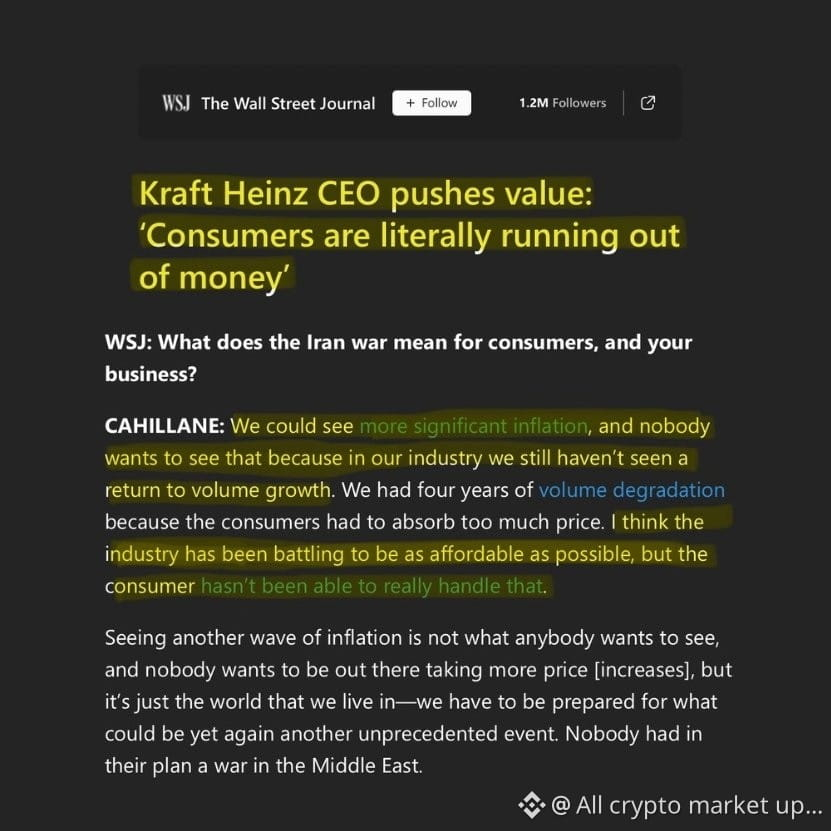
**Kraft Heinz CEO said it directly.** 🎯
*"Consumers are literally running out of money."*
This isn't an analyst guess.
This is real sales data from millions of homes. ⚡
Four years of food inflation.
Four years of volume losses. 💣
People didn't stop eating.
They stopped affording. 🎯
Industry spent two years cutting prices
and shrinking packages
just to get people buying again.
That recovery took two years.
It's not finished yet. 🌍
Now the Iran war threatens
another wave of food inflation
before households recovered from the last one. 📉
Fertilizer prices up 40%.
Energy costs rising.
Supply chains still fragile. 💣
S&P at all time highs.
Kraft Heinz CEO saying consumers
are literally out of money. 🎯
Both true. Same country. Same week.
The economy that looks strong in data
doesn't feel strong at the grocery store. 🌍
Corporate earnings beat estimates.
Families skip meals to make rent.
That gap is the most important
economic story nobody is leading with. 📉
When consumers run out of money —
spending drops.
Earnings follow.
Markets eventually catch up. 👇
#KraftHeinz #Consumer #Economy #Inflation #Recession #Macro #BreakingNews #Food #Markets
**Kraft Heinz CEO said it directly.** 🎯
*"Consumers are literally running out of money."*
This isn't an analyst guess.
This is real sales data from millions of homes. ⚡
Four years of food inflation.
Four years of volume losses. 💣
People didn't stop eating.
They stopped affording. 🎯
Industry spent two years cutting prices
and shrinking packages
just to get people buying again.
That recovery took two years.
It's not finished yet. 🌍
Now the Iran war threatens
another wave of food inflation
before households recovered from the last one. 📉
Fertilizer prices up 40%.
Energy costs rising.
Supply chains still fragile. 💣
S&P at all time highs.
Kraft Heinz CEO saying consumers
are literally out of money. 🎯
Both true. Same country. Same week.
The economy that looks strong in data
doesn't feel strong at the grocery store. 🌍
Corporate earnings beat estimates.
Families skip meals to make rent.
That gap is the most important
economic story nobody is leading with. 📉
When consumers run out of money —
spending drops.
Earnings follow.
Markets eventually catch up. 👇
#KraftHeinz #Consumer #Economy #Inflation #Recession #Macro #BreakingNews #Food #Markets
*"Consumers are literally running out of money."*
This isn't an analyst guess.
This is real sales data from millions of homes. ⚡
Four years of food inflation.
Four years of volume losses. 💣
People didn't stop eating.
They stopped affording. 🎯
Industry spent two years cutting prices
and shrinking packages
just to get people buying again.
That recovery took two years.
It's not finished yet. 🌍
Now the Iran war threatens
another wave of food inflation
before households recovered from the last one. 📉
Fertilizer prices up 40%.
Energy costs rising.
Supply chains still fragile. 💣
S&P at all time highs.
Kraft Heinz CEO saying consumers
are literally out of money. 🎯
Both true. Same country. Same week.
The economy that looks strong in data
doesn't feel strong at the grocery store. 🌍
Corporate earnings beat estimates.
Families skip meals to make rent.
That gap is the most important
economic story nobody is leading with. 📉
When consumers run out of money —
spending drops.
Earnings follow.
Markets eventually catch up. 👇
#KraftHeinz #Consumer #Economy #Inflation #Recession #Macro #BreakingNews #Food #Markets
61
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
1
#CanBTCReboundAfterFallingBelow60K?
408,703 views
1,764 Discussing
2
#GlobalStocksFaceLongestLosingStreakSince2023
138,776 views
1,235 Discussing
3
#BlackRockIBITPostsRecord$541MSingleDayOutflow
2,552 views
35 Discussing
4
#AnthropicPlungesTowardIPOPriceonDay2
65,962 views
686 Discussing
5
#TwentyOneCapitalAdds172.25BTC
17,923 views
233 Discussing
6
#HKBillWouldExcludeTokenizedDepositsFromVirtualAssets
2,016 views
25 Discussing
7
#BNBDropsBelow540USDTWith8.46%DailyDecline
38,365 views
336 Discussing
8
#HKBillProposesHK$100KFineForUnauthorizedCryptoTitles
1,289 views
19 Discussing
9
#BitMineFaces$10.1BUnrealizedETHLoss
2,315 views
23 Discussing
10
#StrategyReports$35BNetReserves
2,225 views
18 Discussing