#twentyonecapitaladds172.25btc Follow my profile. I write research for ordinary traders.
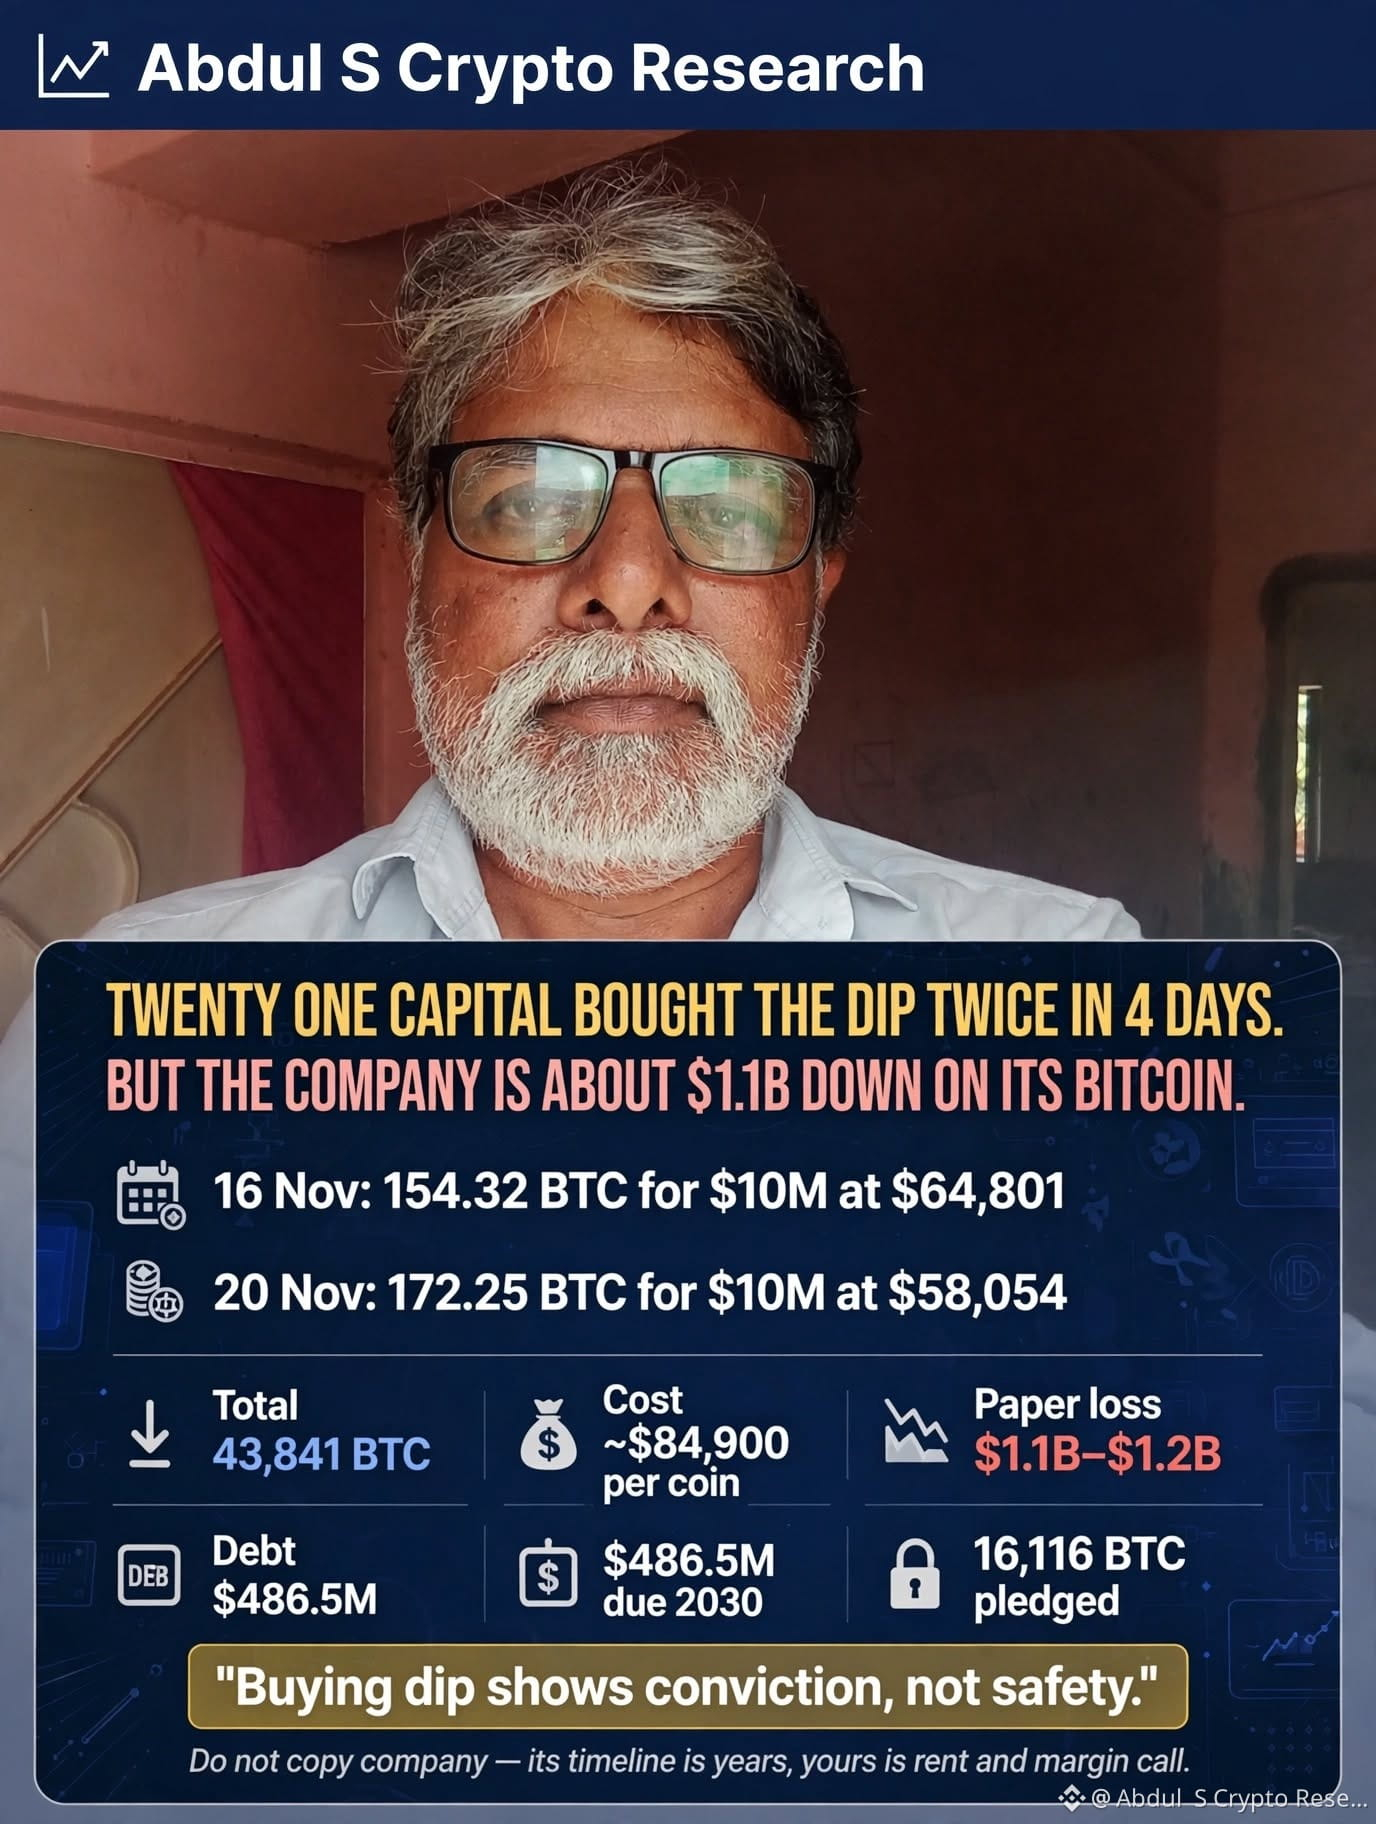
TWENTY ONE CAPITAL BOUGHT THE DIP TWICE IN 4 DAYS. BUT THE COMPANY IS ABOUT $1.1B DOWN ON ITS BITCOIN. WHAT DOES THAT TEACH US?
The facts:
16 Nov: 154.32 BTC for $10M at about $64,801 20 Nov: 172.25 BTC for $10M at about $58,054 Total now: about 43,841 BTC
Same $10M, but the second buy got about 18 more coins because the price fell about 10%.
Now the other side. Its 10-Q filing shows a cost of about $3.69B for 43,514 BTC at 30 Sept, roughly $84,900 per coin. Two $10M buys lower that average by only about $176. BTC must rise about 46% from $58,054 just to reach the company's break-even. At $58K the paper loss is about $1.1B to $1.2B (my math).
The balance sheet:
Cash was $102.8M at 30 Sept. About $20M went out in one week. The current cash is not disclosed. Debt: $486.5M of convertible notes due 2030. About 16,116 BTC is pledged against it.
My view: buying a dip shows conviction, but it does not show safety. A company with a 2030 debt can wait. I cannot wait on borrowed money.
I don't claim to predict every candle. I want to understand WHY.
To the 90% of retail traders: do not copy a company's dip buy. Its timeline is years. Yours is your rent, your family and your margin call. When I made 29,401 trades, I learned that staying power matters more than a brave entry.
Question: when you look at a treasury company, do you watch the BTC it holds or the cash and debt behind it?
Experience, not financial advice.
$BTC
$BNB
$ETH
$XXI #twentyonecapitaladds172.25btc #Bitcoin
TWENTY ONE CAPITAL BOUGHT THE DIP TWICE IN 4 DAYS. BUT THE COMPANY IS ABOUT $1.1B DOWN ON ITS BITCOIN. WHAT DOES THAT TEACH US?
The facts:
16 Nov: 154.32 BTC for $10M at about $64,801 20 Nov: 172.25 BTC for $10M at about $58,054 Total now: about 43,841 BTC
Same $10M, but the second buy got about 18 more coins because the price fell about 10%.
Now the other side. Its 10-Q filing shows a cost of about $3.69B for 43,514 BTC at 30 Sept, roughly $84,900 per coin. Two $10M buys lower that average by only about $176. BTC must rise about 46% from $58,054 just to reach the company's break-even. At $58K the paper loss is about $1.1B to $1.2B (my math).
The balance sheet:
Cash was $102.8M at 30 Sept. About $20M went out in one week. The current cash is not disclosed. Debt: $486.5M of convertible notes due 2030. About 16,116 BTC is pledged against it.
My view: buying a dip shows conviction, but it does not show safety. A company with a 2030 debt can wait. I cannot wait on borrowed money.
I don't claim to predict every candle. I want to understand WHY.
To the 90% of retail traders: do not copy a company's dip buy. Its timeline is years. Yours is your rent, your family and your margin call. When I made 29,401 trades, I learned that staying power matters more than a brave entry.
Question: when you look at a treasury company, do you watch the BTC it holds or the cash and debt behind it?
Experience, not financial advice.
$BTC
$BNB
$ETH
$XXI #twentyonecapitaladds172.25btc #Bitcoin