HBM repricing is moving fast: consensus just lifted SK Hynix's 2027 HBM revenue +25.3% in one month — and price did all the work.
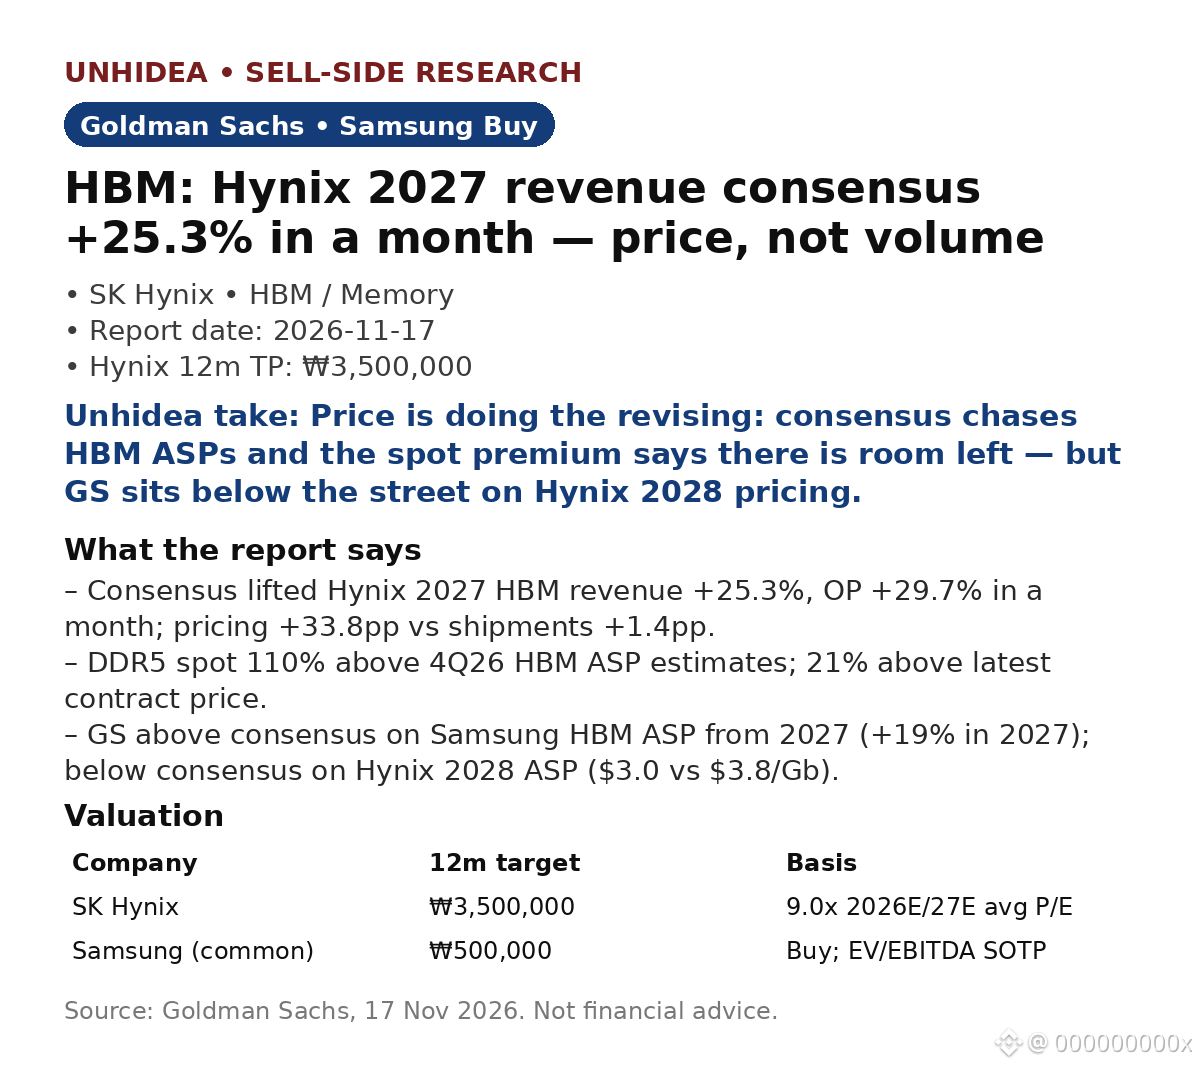
GS's Nov HBM tracker: consensus raised Hynix 2027 HBM revenue +25.3% and operating profit +29.7% vs a month ago. Pricing +33.8pp vs shipments +1.4pp. 2028: revenue +15.1%, OP +12.0%.
Spot prices back it: DDR5 spot is 110% above GS's 4Q26 HBM ASP estimate and 21% above the latest contract price.
GS is above consensus on Samsung HBM ASP from 2027 (+19% in 2027, +7% in 2028) but below consensus on Hynix 2028 ASP ($3.0/Gb vs $3.8/Gb street). Samsung Buy, ₩500,000 target; Hynix 12m target ₩3,500,000 at 9.0x P/E.
After the report: Nvidia Q3 revenue $115.8B, +103% YoY; Q4 guide $130B ±3% — demand just confirmed itself.
Unhidea take: this revision is price-led, not volume-led — memory pricing, not units, is the revision engine; the DDR5 spot premium is the number to watch.
Unhidea take: the street prices Hynix as the winner, Samsung as the laggard; if Samsung closes the HBM gap, consensus Hynix ASP has further to fall.
Risks: memory downturn; weaker device demand; lower AI capex. Source: Goldman Sachs, 17 Nov 2026. Not financial advice.
GS's Nov HBM tracker: consensus raised Hynix 2027 HBM revenue +25.3% and operating profit +29.7% vs a month ago. Pricing +33.8pp vs shipments +1.4pp. 2028: revenue +15.1%, OP +12.0%.
Spot prices back it: DDR5 spot is 110% above GS's 4Q26 HBM ASP estimate and 21% above the latest contract price.
GS is above consensus on Samsung HBM ASP from 2027 (+19% in 2027, +7% in 2028) but below consensus on Hynix 2028 ASP ($3.0/Gb vs $3.8/Gb street). Samsung Buy, ₩500,000 target; Hynix 12m target ₩3,500,000 at 9.0x P/E.
After the report: Nvidia Q3 revenue $115.8B, +103% YoY; Q4 guide $130B ±3% — demand just confirmed itself.
Unhidea take: this revision is price-led, not volume-led — memory pricing, not units, is the revision engine; the DDR5 spot premium is the number to watch.
Unhidea take: the street prices Hynix as the winner, Samsung as the laggard; if Samsung closes the HBM gap, consensus Hynix ASP has further to fall.
Risks: memory downturn; weaker device demand; lower AI capex. Source: Goldman Sachs, 17 Nov 2026. Not financial advice.