
The upcoming U.S. Consumer Price Index (CPI) report scheduled for November 10, 2026, serves as the definitive economic indicator shaping the Federal Reserve's final policy decision of the year at their December 8–9 meeting.
Following the October Nonfarm Payrolls report—which showed a surprisingly hot 165,000 jobs added and unemployment dipping to 4.1%—financial markets aggressively repriced the probability of a 25 bps Federal Reserve interest rate hike in December to near 80%.
The upcoming CPI reading will either solidify this hawkish pivot or offer room for a dovish pause.
1. Market Scenarios & Impact on the December Fed Decision
Scenario A: Hotter-Than-Expected CPI (Bullish USD / Bearish Risk Assets & Gold)
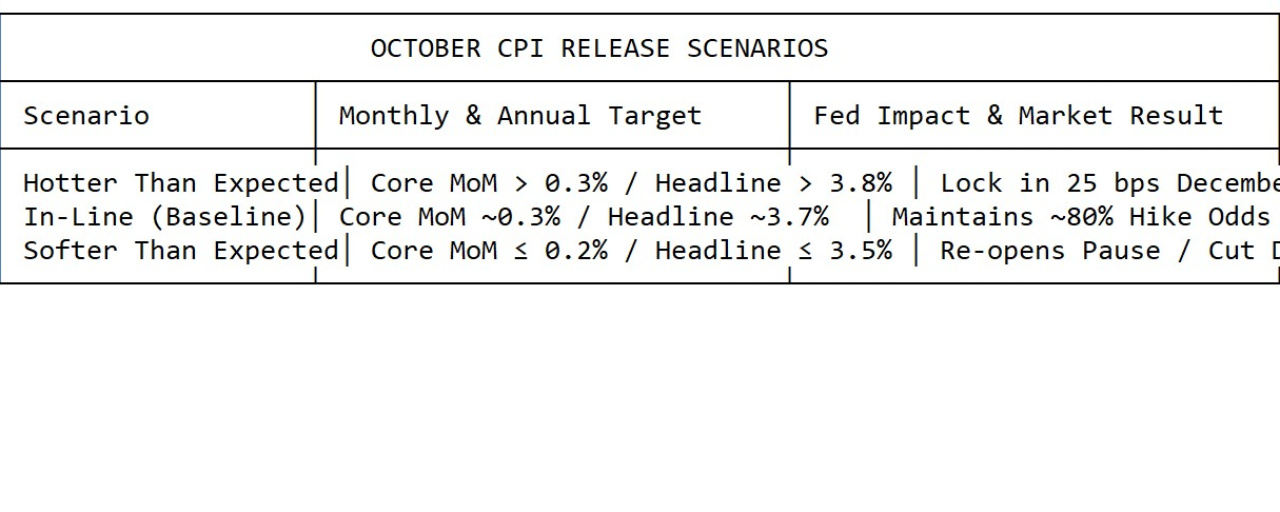
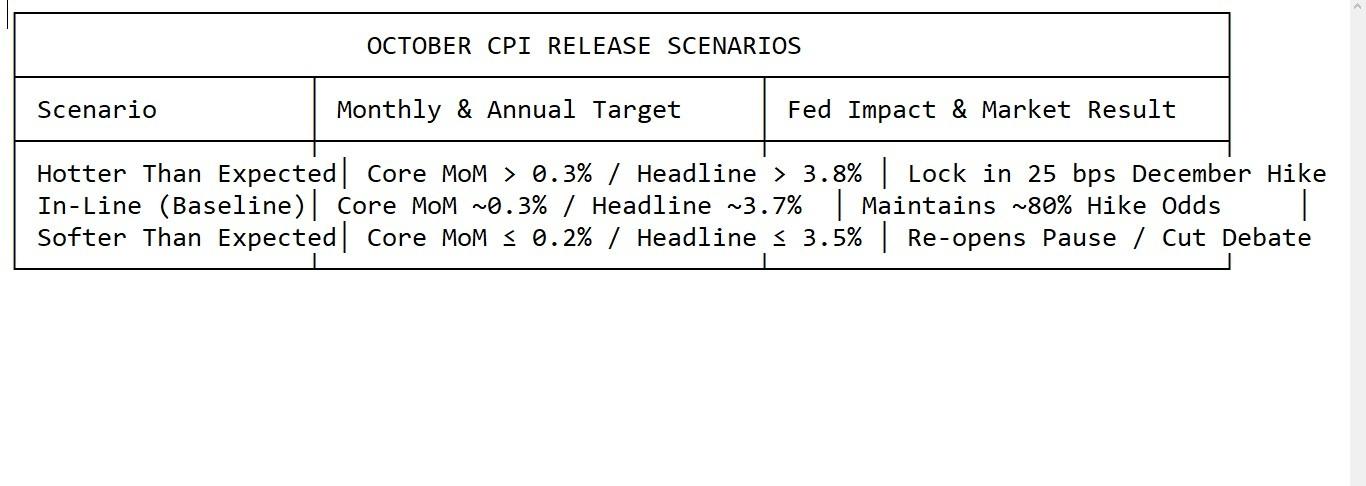
The Target: Core CPI rising > 0.3% MoM or Headline CPI exceeding 3.8%.
Fed Decision: Completely locks in a 25 bps rate hike on December 9. A combination of accelerating wage growth (+0.4% MoM) and persistent goods/shelter inflation would signal to the FOMC that monetary policy remains too accommodative.
Asset Class Reactions:
U.S. Dollar (DXY) & Yields: Surge to multi-month highs.
Crypto (BTC / ETH / BNB): Facing liquidity pressure; potential retest of major support levels (e.g., BTC toward $76,000).
Gold (XAU/USD): Real yield expansion would pressure Gold back down toward the $3,980 breakout support zone.
Scenario B: Softer-Than-Expected CPI (Dovish Shift / Bullish Risk Assets)
The Target: Core CPI cooling to ≤ 0.2% MoM or Headline dropping below 3.6%.
Fed Decision: Significantly lowers the December rate hike probability (dropping odds back toward 40%–50%). It provides the Fed with justification to hold rates steady, citing lagging transmission of previous tightening.
Asset Class Reactions:
Crypto: Immediate relief rally; BTC retesting high-volume resistance ($82,000+), ETH breaking out toward $2,450+.
Gold: Re-accelerates toward $4,080 – $4,120 ATH territory on falling real yields.
Equities (S&P 500 / Nasdaq): Aggressive short-covering bounce, extending post-midterm post-election rally momentum.
2. Key Sub-Components Fed Officials Are Watching
Supercore Inflation (Services Ex-Housing): Highly correlated with tight labor markets and wage growth. With October wage gains coming in hot (+0.4%), sticky service inflation is the Fed's biggest concern.
Energy & Gasoline Drivers: Gasoline pump prices averaged ~$4.15 per gallon leading into early November. While easing from early autumn peaks, energy stabilization dictates headline volatility.
Shelter & Rent Lag: Housing and rental metrics account for over 30% of the CPI basket. Any sustained deceleration here is required for inflation to trend back toward the Fed's 2.0% target.
3. Summary Trading Checklist Ahead of Nov 10
Volatility Positioning: Reduce leverage 24 hours prior to the release (8:30 AM ET on Tuesday, Nov 10).
Post-Release Key Levels to Watch:
BTC/USDT: Holding $79,200 keeps the broader structure bullish; losing it opens $76,000.
ETH/USDT: Reclaiming $2,425 confirms breakout continuation; losing $2,330 invalidates.
XAU/USD: Bullish above $3,980; downside risk toward $3,920 on a hawkish CPI spike.