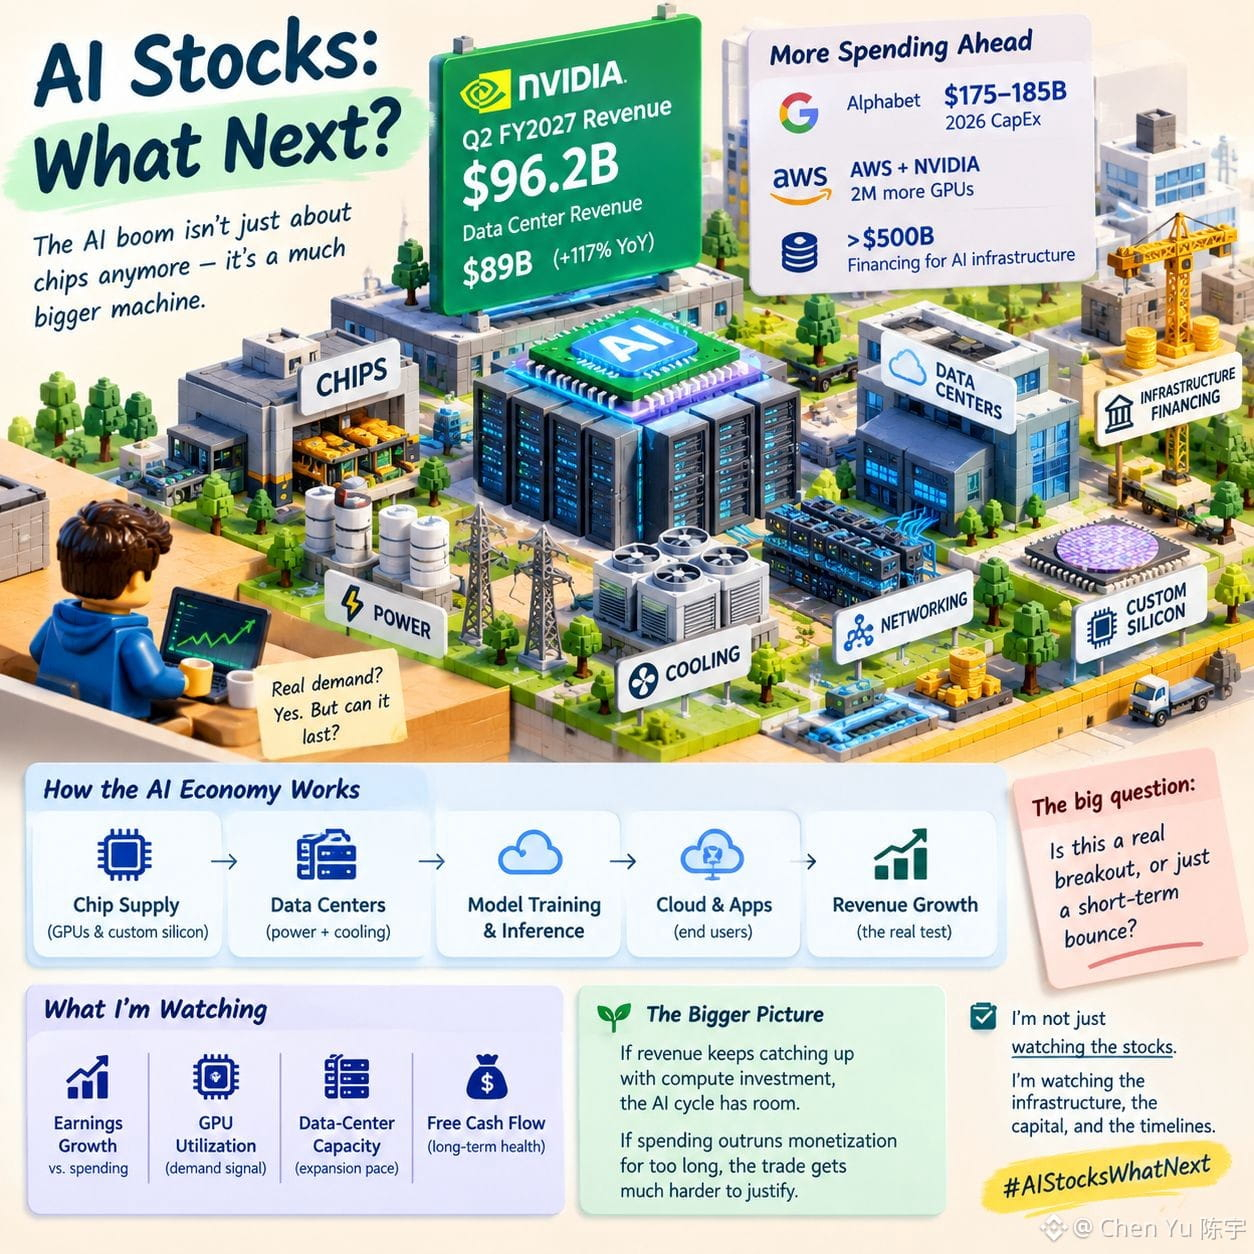
Last night I kept coming back to one number: NVIDIA reported $96.2B in quarterly revenue, with Data Center revenue hitting $89B, up 117% year over year. That makes the AI boom harder to dismiss as pure stock-market hype.
But there’s a catch. AI demand is not just a chip story anymore. Alphabet expects $175–185B of 2026 CapEx, while AWS and NVIDIA plan to deploy another 2 million GPUs.
That spending creates a second investment layer: power, cooling, networking, data centers, custom silicon and infrastructure financing. NVIDIA is even working with major financial firms to mobilize more than $500B for AI infrastructure.
So I’m watching earnings growth versus infrastructure spending, GPU utilization, data-center capacity and free cash flow. If revenue keeps catching up with compute investment, the AI cycle has room. If spending outruns monetization for too long, the trade gets much harder to justify.
#AIStocksWhatNext
$MUBARAK
$CHR
$4Stock
But there’s a catch. AI demand is not just a chip story anymore. Alphabet expects $175–185B of 2026 CapEx, while AWS and NVIDIA plan to deploy another 2 million GPUs.
That spending creates a second investment layer: power, cooling, networking, data centers, custom silicon and infrastructure financing. NVIDIA is even working with major financial firms to mobilize more than $500B for AI infrastructure.
So I’m watching earnings growth versus infrastructure spending, GPU utilization, data-center capacity and free cash flow. If revenue keeps catching up with compute investment, the AI cycle has room. If spending outruns monetization for too long, the trade gets much harder to justify.
#AIStocksWhatNext
$MUBARAK
$CHR
$4Stock